
Which stock return anomalies are trustworthy, and which are not? In the June 2007 draft of their paper entitled “Dissecting Anomalies”, Eugene Fama and Kenneth French apply both sorts and regressions to examine the robustness of the momentum, net stock issuance, accruals, profitability and asset growth anomalies. They note that sorts on an anomaly variable offer a simple picture of how average returns vary, but microcaps (a few big stocks) can dominate the performance of a sort-based equal-weighted (value-weighted) hedge portfolio. In addition, sorts are ill-suited to determinations of: (1) the exact relationship between an anomaly variable and returns, and (2) relationships among anomalies. They note also that extreme behavior by microcaps and outliers generally can distort inference from regressions. Using a robust set of firm data for a broad set of U.S. stocks allocated to three size groups (microcap, small and big) over the period 1963-2005, they conclude that:
- On average, microcaps are roughly 60% of sampled stocks, but they represent only about 3% of total market value (compared to 90% for big stocks). They boast a high average equal-weighted (EW) monthly return of 1.56% (1.07% for big stocks), but they also have the highest return volatility by far.
- Using sorts based on anomaly variables, adjusted for size and book-to-market (B/M) factors:
- Momentum, net stock issuance and accruals relate to large abnormal returns for all size groups. The EW and value-weighted (VW) abnormal hedge portfolio returns for these three variables are strong across all size groups.
- Abnormal returns after net stock issues and accruals derive mostly from extreme values of these variables.
- Higher positive profitability relates to higher abnormal returns, but negative profitability does not lead to abnormally low returns.
- There is no asset growth anomaly for big stocks.
- Using regressions of stock returns on anomaly variables:
- Size owes much of its predictive power to microcaps. Its effect is marginal for small and big stocks.
- The relationship between average returns and B/M is moderate and consistent across size groups.
- Momentum and net stock issuance exhibit the strongest average regressions across all size groups. Momentum effects are only about half as strong for microcaps as for small and big stocks.
- Positive accruals relate negatively to average returns for all size groups.
- Among profitable firms, profitability relates positively to average returns for all size groups.
- The negative relationship between asset growth and average returns is powerful for microcaps, weaker but statistically reliable for small stocks and largely non-existent for big stocks.
- All these anomaly variables are at least rough proxies for expected cash flows and therefore reasonably affect valuations.
The following chart organizes key findings from the paper.
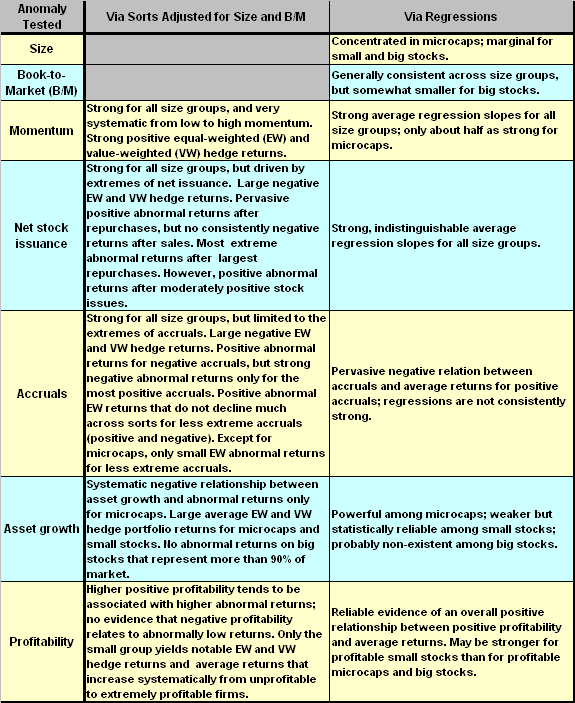
In summary, some anomalies are stronger and more consistent than others. Momentum appears to be the strongest and most consistent.
Frequently Asked Questions
What is a stock return anomaly in finance?
A stock return anomaly is a pattern in average stock returns, tied to a variable such as momentum, net stock issuance, accruals, profitability or asset growth, that is not explained by standard factors like size and book-to-market. Fama and French examined these five anomalies in U.S. stocks over 1963-2005. They note that all five variables are at least rough proxies for expected cash flows and therefore reasonably affect valuations.
Which stock return anomalies hold up across small and large stocks?
Momentum, net stock issuance and accruals produce large abnormal returns across all size groups (microcap, small and big) in U.S. stocks over 1963-2005. Momentum appears to be the strongest and most consistent anomaly. The asset growth anomaly is the exception, as it is powerful for microcaps, weaker but statistically reliable for small stocks and largely non-existent for big stocks.
How do researchers test whether a stock anomaly is robust using sorts and regressions?
Fama and French apply both sorts and regressions to U.S. stocks from 1963-2005, split into microcap, small and big size groups. Sorts rank stocks on an anomaly variable and form hedge portfolios with returns adjusted for size and book-to-market factors. Regressions of stock returns on anomaly variables then capture the exact relationship between each variable and returns and the relationships among anomalies.
Is the momentum anomaly weaker or stronger in microcaps than in big stocks?
Momentum effects in regressions are only about half as strong for microcaps as for small and big stocks, according to Fama and French (1963-2005). Even so, momentum shows among the strongest average regression results across all size groups. By contrast, the size effect owes much of its predictive power to microcaps and is marginal for small and big stocks.
Why can microcaps distort stock anomaly research results?
Microcaps are roughly 60% of sampled stocks but only about 3% of total market value (versus 90% for big stocks), so they can dominate the performance of equal-weighted sort-based hedge portfolios. They also have the highest return volatility by far, and extreme microcap behavior and outliers can distort inference from regressions. Sorts are also ill-suited to determining the exact relationship between an anomaly variable and returns, or relationships among anomalies.