
How exposed are hedge funds to “rogue” correlations, wherein returns of assets or asset classes that normally exhibit hedging cancellation instead exhibit hedge-killing reinforcement? In the June 2010 version of their paper entitled “‘When There Is No Place to Hide’: Correlation Risk and the Cross-Section of Hedge Fund Returns”, Andrea Buraschi, Robert Kosowski and Fabio Trojani investigate the exposure of hedge funds to correlation risk (risk of unexpected changes in the correlation between the returns of different assets or asset classes) and the implications of this risk for hedge fund returns. Using data for actual one-month-to-maturity S&P 500 correlation swaps (based on daily implied versus realized correlation), individual S&P 500 stock and index put and call options and a broad sample of 8,710 individual hedge funds spanning in combination January 1996 through December 2008, they find that:
- Rogue correlations tend to occur during market crashes or periods of economic crisis.
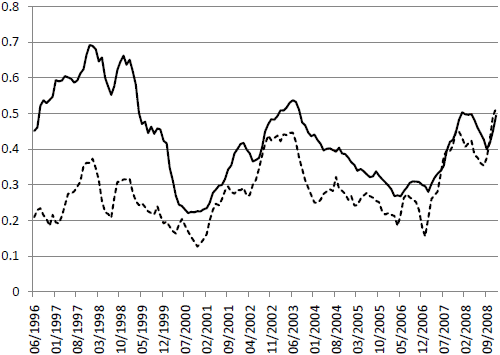
- The correlation risk premium over the entire sample period averages -14.3% per month, but declines over time (see the chart below). The bulk of the option-implied variance risk premium apparently derives from correlation risk.
- Because they seek to exploit correlation to dampen aggregate return volatility, hedge funds generally impound correlation risk. Adjusting for correlation risk (after adjusting for seven other commonly used hedge fund risk factors) reduces the alpha of a broad value-weighted hedge fund index from 5.36% to 3.47%.
- Correlation risk exposures are particularly high for Long/Short Equity, Option Trader, Merger Arbitrage and Multi-Strategy hedge funds. Adjusting for correlation risk (after adjusting for the seven other factors) reduces the alpha of a value-weighted index of these low net market exposure funds from 13.7% to 4.25%.
- Adding a correlation risk factor to a seven-factor hedge fund return model increases the model’s ability to explain hedge fund returns from 10.5% to 17.7%.
- Funds with large negative correlation risk exposures tend to have high returns. The tenth of hedge funds with the most negative correlation risk exposures (implicitly selling insurance against unexpected increases in correlations) have an average raw annualized return of 13.4% and a seven-factor alpha of 8.9%. However, correlation risk explains over 10% of the 13.4% return.
- Correlation risk exposure strongly affects hedge fund return distribution tail behavior and maximum drawdown. The typical maximum drawdown for the tenth of hedge funds with the largest negative correlation risk exposures are nearly three times bigger than the typical drawdown of the tenth of funds with the largest positive correlation risk exposure.
- Results are robust to use of alternative databases, equal weighting instead of value weighting and inclusion of liquidity factors.
The following chart, taken from the paper, shows the six-month moving average of the implied correlation (solid line) and the realized correlation (dashed line) derived from actual and modeled correlation swap quotes. The correlation risk premium (derived from realized minus implied) is persistently negative but generally declining in magnitude over time. Expanding use of strategies seeking to exploit the premium may be compressing it.
In summary, evidence indicates that hedge funds with low net market exposure may earn returns largely by assuming that correlations between assets and asset classes will behave predictably, and rogue correlation spikes may swamp these funds with extremely large drawdowns.
Frequently Asked Questions
What is correlation risk in hedge funds?
Correlation risk in hedge funds is the risk of unexpected changes in the correlation between the returns of different assets or asset classes, such as when assets that normally hedge each other instead move together. These 'rogue' correlations tend to occur during market crashes or periods of economic crisis. Hedge funds generally take on this risk because they seek to exploit correlation to dampen aggregate return volatility.
Does correlation risk explain hedge fund returns?
Correlation risk explains a meaningful part of hedge fund returns, according to a 1996–2008 study of 8,710 hedge funds. Adding a correlation risk factor to a seven-factor model raises explanatory power from 10.5% to 17.7%, and it explains over 10% of the 13.4% annualized return of the tenth of funds with the most negative correlation risk exposures. Adjusting for it cuts the alpha of a broad value-weighted hedge fund index from 5.36% to 3.47%.
How is hedge fund exposure to correlation risk measured?
Hedge fund exposure to correlation risk was measured using data on actual one-month-to-maturity S&P 500 correlation swaps, which are based on daily implied versus realized correlation. The study combined these with individual S&P 500 stock and index put and call options and 8,710 individual hedge funds spanning January 1996 through December 2008. Researchers added a correlation risk factor to a seven-factor hedge fund return model and tested results with alternative databases, equal weighting and liquidity factors.
Do hedge funds with high returns from selling correlation insurance have true alpha?
Hedge funds with large negative correlation risk exposures, which implicitly sell insurance against rising correlations, earn high returns that are partly compensation for risk rather than pure skill. The top tenth by negative exposure had a 13.4% raw annualized return and an 8.9% seven-factor alpha, but correlation risk explained over 10% of that return. For low net market exposure funds (Long/Short Equity, Option Trader, Merger Arbitrage, Multi-Strategy), adjusting for correlation risk cut alpha from 13.7% to 4.25%.
What are the risks of hedge funds with negative correlation risk exposure?
Hedge funds with large negative correlation risk exposures face severe tail risk, because rogue correlation spikes can swamp them with very large drawdowns. The typical maximum drawdown for the tenth of funds with the most negative exposures is nearly three times bigger than for the tenth with the most positive exposures. In addition, the correlation risk premium, which averaged -14.3% per month, has been declining over time, possibly because expanding use of strategies seeking to exploit it is compressing it.