
Why do simple stock portfolios such as equal weighting and random weighting beat market capitalization weighting over the long run? In their June 2018 paper entitled “Diversification, Volatility, and Surprising Alpha”, Adrian Banner, Robert Fernholz, Vassilios Papathanakos, Johannes Ruf and David Schofield tackle this question by decomposing expected stock portfolio log-return into average growth rate and excess growth rate (EGR). They focus on average log-return because, unlike arithmetic and geometric averages, it is an unbiased estimator of long-term performance. They apply two formulas derived in prior work to estimate portfolio log-returns:
- Expected portfolio log-return = weighted average stock log-return + EGR
- EGR = (weighted average stock return variance – portfolio return variance)/2
They apply these formulas to the following five portfolios, each consisting of monthly overlapping sub-portfolios formed from the 1,000 U.S. stocks with the (each day) largest market capitalizations and rebalanced annually with stock weights normalized to a sum of one:
- Capitalization-weighted (CW) – stock weights are proportional to their respective market capitalizations.
- Equal-weighted (EW) – weight of each stock is 1/1000.
- Large-overweighted (LO) – stock weights are proportional to the square of their respective market capitalizations.
- Random-weighted (RW) – stock weights are proportional to random values between zero and one (median of 1,000 trials).
- Inverse random-weighted (IRW) – stock weights are proportional to the reciprocals of random values between zero and one (median of 1,000 trials).
EGR quantifies the extent to which portfolio volatility is less than constituent stock volatilities and is always positive for long-only portfolios. Higher constituent stock volatilities generate higher portfolio EGRs. Using daily prices for the 1,000 U.S. stocks with the largest market capitalizations each day during 1964 through 2012 (5,384 distinct stocks over 49 years), they find that:
- Over the sample period, average log-returns do not vary with market capitalization rank. In other words, smaller stocks do not have higher expected log-returns than larger stocks.
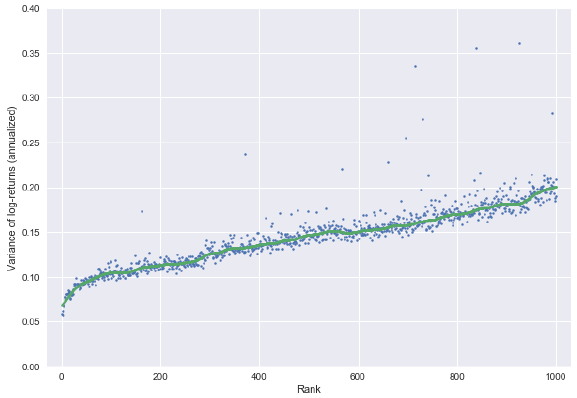
- Log-return variance, however, varies systematically with market capitalization rank, with smaller stocks having higher variances than larger stocks (see the chart below).
- Variation among log-returns of different portfolios therefore depends essentially on differences in their respective EGRs, as driven by different mixes of smaller and larger stocks. Since smaller stocks tend to be more volatile than larger stocks, portfolios tilted toward smaller stocks tend to have higher EGRs and therefore higher overall expected log-returns.
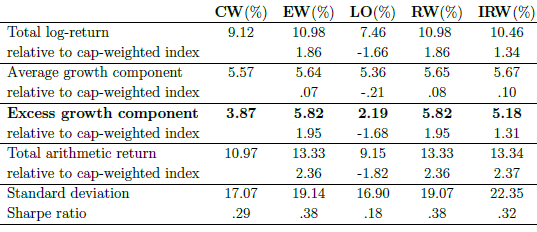
- Specifically, over the 49-year sample period (see the table below):
- The EW, RW and IRW portfolios specified above all outperform the CW portfolio, due largely to differences in EGRs.
- The CW portfolio outperforms the LO portfolio for the same reason.
The following chart, taken from the paper, plots annualized daily log-return variance by market capitalization rank for the top 1000 U.S. stocks over the full sample period. The green line is a smoothed version of results. The chart shows that smaller stocks tend to have a larger variance than larger stocks.
In contrast average daily log-return by market capitalization rank is approximately flat, indicating that smaller and larger stocks have about the same expected log-return.
The following table, also from the paper, summarizes annualized gross performance statistics for the five portfolios specified above. Notable points are:
- Average log-returns (average growth components) are similar, with EW, RW and IRW having only slight advantages over CW.
- EGRs (excess growth components), however, differ considerably. EW and RW (IRW) outperform CW by about 2% (1.5%) annually. Return outperformance translates to higher Sharpe ratios.
- Performances of EW and RW are nearly identical, since many random weighting trials tend to average to equal weights.
In summary, evidence indicates that simple stock portfolios such as equal weighting and random weighting beat market capitalization weighting over the long run due to higher volatilities, not higher returns, of smaller stocks.
Cautions regarding findings include:
- All findings are gross, not net. Trading frictions tend to rise with asset volatility, and portfolio rebalancing thus tends to be more costly for smaller stocks than larger stocks. This tendency works against the EGR effect described above and may neutralize it.
- Findings may differ for other asset class universes.
Frequently Asked Questions
What is excess growth rate in stock portfolio returns?
Excess growth rate (EGR) is the amount by which a portfolio's expected log-return exceeds the weighted average of its constituent stocks' log-returns. It is calculated as (weighted average stock return variance minus portfolio return variance) divided by 2, so it measures how much portfolio volatility is below constituent stock volatilities. EGR is always positive for long-only portfolios, and higher constituent stock volatilities produce higher EGRs.
Do equal-weighted portfolios beat cap-weighted portfolios over the long run?
Equal-weighted portfolios outperformed cap-weighted portfolios in a 1964–2012 study of the 1,000 largest U.S. stocks, by about 2% annually in log-return. Random-weighted portfolios did about as well, and inverse random-weighted portfolios outperformed by about 1.5% annually. The outperformance came mainly from higher excess growth rates, not higher average stock log-returns, and the results are gross of trading costs.
How do you decompose stock portfolio log-return into average growth and excess growth?
Expected portfolio log-return equals the weighted average stock log-return plus the excess growth rate (EGR), where EGR is half the difference between the weighted average stock return variance and the portfolio return variance. The researchers applied this to five portfolios (cap-weighted, equal-weighted, large-overweighted, random-weighted and inverse random-weighted) built from the 1,000 largest U.S. stocks by daily market capitalization during 1964–2012. Each portfolio consisted of monthly overlapping sub-portfolios rebalanced annually, and the random-weighted versions used the median of 1,000 trials.
Do smaller stocks have higher returns than larger stocks, or just higher volatility?
In the 1964–2012 sample of the 1,000 largest U.S. stocks, smaller stocks had higher log-return variance but about the same average log-return as larger stocks. Average log-returns were roughly flat across market capitalization rank. Portfolios tilted toward smaller stocks therefore outperformed because higher volatility raised excess growth rates, not because small stocks had higher expected log-returns.
What are the limitations of the excess growth rate explanation for equal-weighted portfolio outperformance?
The reported results are gross, not net of trading costs, which matters because trading frictions tend to rise with asset volatility. Rebalancing is therefore typically more costly for smaller stocks than larger stocks, which works against the excess growth rate effect and may neutralize it. The findings are also based on the top 1,000 U.S. stocks and may differ for other asset class universes.