
A European subscriber asked about the effect of the dollar-euro exchange rate on the Simple Asset Class ETF Value Strategy (SACEVS) and the Simple Asset Class ETF Momentum Strategy (SACEMS). To investigate, we each month adjust the gross returns for these strategies for the change in the dollar-euro exchange rate that month. We consider all strategy variations: Best Value and Weighted for SACEVS; and, Top 1, equally weighted (EW) Top 2 and EW Top 3 for SACEVS. We focus on SACEVS Best Value and SACEMS EW Top 3. We consider effects on four gross performance metrics: average monthly return; standard deviation of monthly returns; compound annual growth rate (CAGR); and, maximum drawdown (MaxDD). Using monthly returns for the strategies and monthly changes in the dollar-euro exchange rate since August 2002 for SACEVS and since July 2006 for SACEMS, both through December 2020, we find that:
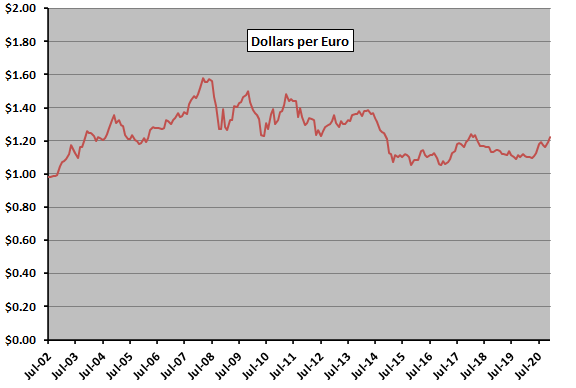
The following chart tracks dollars per euro since July 2002 based on end-of-month data, showing that the dollar sometimes appreciates versus the euro (dollars per euro falls) and sometimes depreciates (dollars per euro rises). Effects of changes in the exchange rate therefore depend on the sample period. It may be that the exchange rate is mean reverting over long periods, but not over periods of a few years.
How does this trajectory affect SACEVS and SACEMS?
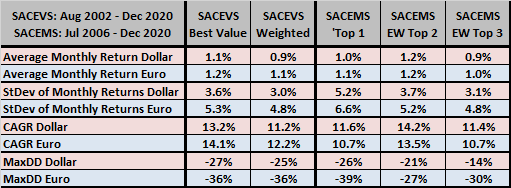
The following table compares performance metrics for all variations of SACEVS and SACEMS, unadjusted (Dollar) and adjusted for changes in the dollar-euro exchange rate (Euro) over available sample periods. Notable points are that exchange rate fluctuations:
- Do not hurt average monthly returns.
- Do make monthly returns more volatile and MaxDDs deeper.
- Increase CAGR for SACEVS and decrease CAGR for SACEMS.
The consistent volatility and MaxDD effects are likely inherent to an additional fluctuating variable in return calculations. CAGR effects are due to different sample periods. The SACEMS sample period misses a substantial dollar depreciation during 2002-2004.
For additional perspective, we compare original and exchange rate-adjusted cumulative performances for SACEVS Best Value and SACEMS EW Top 2.
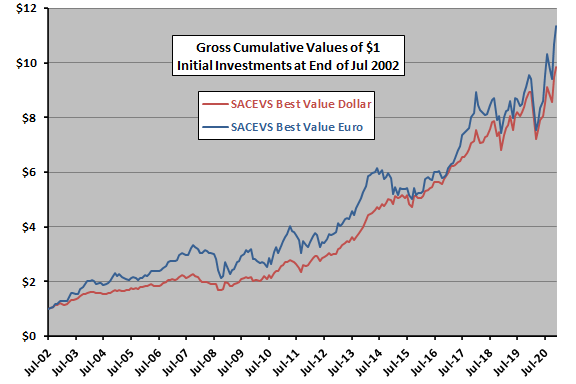
The next chart compares unadjusted SACEVS Best Value (Dollar) to exchange rate-adjusted SACEVS Best Value (Euro) over the available sample period. The latter mostly leads the former due to an extended dollar depreciation early in the sample period.
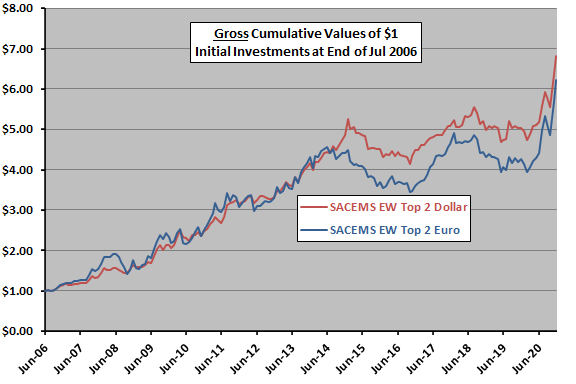
The final chart compares unadjusted SACEMS EW Top 2 (Dollar) to exchange rate-adjusted SACEMS EW Top 2 (Euro) over the available sample period. The two track closely until a year of strong dollar appreciation starting mid-2014 that drives the latter down relative to the former.
A non-U.S. investor wishing to invest in the strategies but avoid currency risk could employ a parallel currency hedge (which would involve costs) or implement the strategy in local asset class proxies (which may behave differently from U.S. counterparts).
In summary, available evidence indicates that introducing a currency exchange complication into SACEVS and SACEMS increases strategy volatilities and deepens drawdowns.
Cautions regarding findings include:
- Reported returns are gross, not net. Accounting for monthly portfolio reformation frictions as incurred would reduce these returns.
- There is latitude for parameter value snooping in each strategy. Also, testing multiple versions of a strategy on the same data introduces snooping bias.
- Results for dollar exchange rates for other currencies may differ.
- Anticipating directional effects of changes in the exchange rate would require accurate exchange rate forecasting.
Frequently Asked Questions
What are the Simple Asset Class ETF Value Strategy (SACEVS) and Simple Asset Class ETF Momentum Strategy (SACEMS)?
SACEVS (Simple Asset Class ETF Value Strategy) and SACEMS (Simple Asset Class ETF Momentum Strategy) are rules-based strategies that trade asset class exchange-traded funds (ETFs), reforming the portfolio monthly. SACEVS has Best Value and Weighted variations, while SACEMS has Top 1, equally weighted (EW) Top 2 and EW Top 3 variations. The article evaluates them from the perspective of a European (euro-based) investor.
Does adjusting for the dollar-euro exchange rate hurt the performance of SACEVS and SACEMS?
Adjusting SACEVS and SACEMS for the dollar-euro exchange rate does not hurt average monthly returns, but it makes monthly returns more volatile and maximum drawdowns deeper. Compound annual growth rate (CAGR) rises for SACEVS (August 2002-December 2020) and falls for SACEMS (July 2006-December 2020). The CAGR differences stem from different sample periods rather than a consistent currency effect.
How do you adjust ETF strategy returns for exchange rate changes to see the effect on a European investor?
The researchers adjust each month's gross strategy return for that month's change in the dollar-euro exchange rate, applying this to all SACEVS and SACEMS variations. They then compare unadjusted (dollar) and adjusted (euro) results on four gross metrics: average monthly return, standard deviation of monthly returns, CAGR and maximum drawdown. Data cover August 2002 to December 2020 for SACEVS and July 2006 to December 2020 for SACEMS.
Why does currency adjustment increase CAGR for SACEVS but decrease it for SACEMS?
The opposite CAGR effects for SACEVS and SACEMS arise from different sample periods, not from the strategies themselves. SACEVS includes an extended dollar depreciation during 2002-2004, so its euro-adjusted version mostly leads the dollar version, while SACEMS starts later and misses that period. For SACEMS EW Top 2, the two versions track closely until a year of strong dollar appreciation starting mid-2014 pulls the euro-adjusted version down.
What are the limitations of the findings on SACEVS and SACEMS from a European perspective?
The reported returns are gross, so accounting for monthly portfolio reformation frictions would reduce them. There is latitude for parameter snooping in each strategy, and testing multiple versions on the same data introduces snooping bias. Results for other currencies may differ, and anticipating directional exchange rate effects would require accurate exchange rate forecasting. A non-U.S. investor avoiding currency risk could use a costly parallel currency hedge or local asset class proxies, which may behave differently from U.S. counterparts.