
Do any of the major U.S. stock market sectors systematically lead or lag the overall market, perhaps because of some underlying business/economic cycle? To investigate, we examine the behaviors of the nine sectors defined by the Select Sector Standard & Poor’s Depository Receipts (SPDR) exchange traded funds (ETF):
Materials Select Sector SPDR (XLB)
Energy Select Sector SPDR (XLE)
Financial Select Sector SPDR (XLF)
Industrial Select Sector SPDR (XLI)
Technology Select Sector SPDR (XLK)
Consumer Staples Select Sector SPDR (XLP)
Utilities Select Sector SPDR (XLU)
Health Care Select Sector SPDR (XLV)
Consumer Discretionary Select SPDR (XLY)
Using monthly dividend-adjusted closing prices for these ETFs, along with contemporaneous data for SPDR S&P 500 (SPY) as a benchmark, during December 1998 (sector ETF inception) through August 2021, we find that:
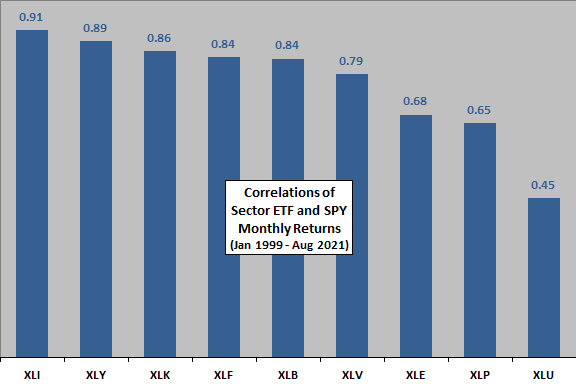
The following chart summarizes correlations of coincident monthly returns for each of the nine sector ETFs with the monthly returns of SPY over the available sample period, in order of decreasing correlation. Utilities, consumer staples and energy have the lowest correlations and are therefore the best candidates for market leaders or laggers. Utilities are arguably somewhat bond-like, and both energy and staples are somewhat commodity-like.
To test for lead-lag relationships, we calculate correlations for the monthly returns of each ETF offset by intervals ranging from -12 months (sectors lag the market) to +12 months (sectors lead the market) with respect to monthly returns of SPY. If there is a systematic leading or lagging relationship between a sector ETF and SPY of a year or less, it should emerge as a notably positive or negative correlation over this range of offsets.
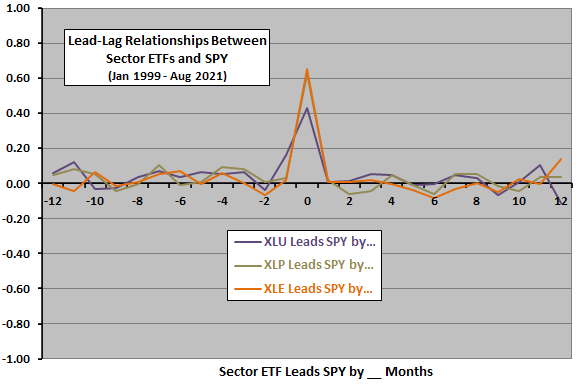
The following chart shows the offset correlations for the utilities, consumer staples and energy sector ETFs (the three sector ETFs with the lowest coincident correlations with SPY). The coincident correlations are clearly strongest, but there is a hint that utilities have some tendency to lag the overall stock market by a month. Correlations for other sector-market lead-lag relationships appear to be noise.
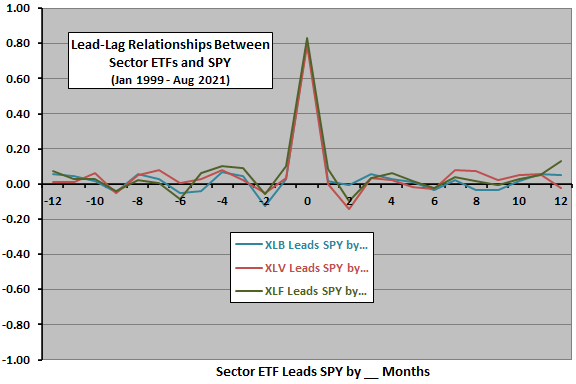
The next chart shows the offset correlations for the materials, financial and health care sector ETFs. The coincident correlations dominate, and correlations for other sector-market lead-lag relationships appear to be noise. There may be a slight scalloping of lead-lag correlations, perhaps associated with synchronized dividends.
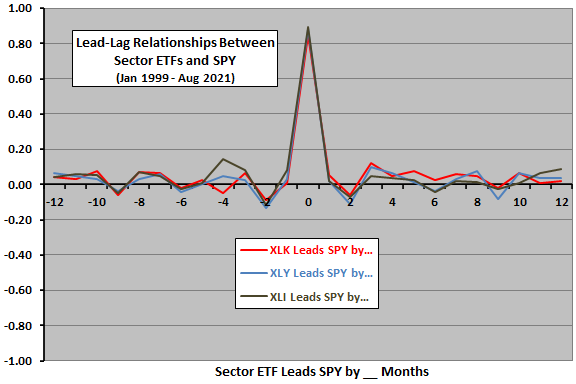
The final chart shows the offset correlations for the consumer discretionary, industrial and technology sector ETFs (the three sector ETFs with the highest coincident correlations with SPY). The coincident correlations again dominate, and correlations for other sector-market lead-lag relationships appear to be noise. Again, synchronized dividends may account for the slight scallop pattern across offset intervals.
In summary, there is little evidence that any equity sector ETFs reliably lead or lag the overall U.S. stock market over the past 23 years. Utilities may slightly lag the broad market.
Cautions regarding findings include:
- The sample is small in terms of the number of underlying business/economic cycles.
- Other ways of specifying sectors (or industries) may produce different results.
Frequently Asked Questions
What is a sector ETF and what are the Select Sector SPDR funds?
A sector ETF is an exchange traded fund that holds stocks from one segment of the U.S. stock market. The nine Select Sector SPDR ETFs cover materials (XLB), energy (XLE), financials (XLF), industrials (XLI), technology (XLK), consumer staples (XLP), utilities (XLU), health care (XLV) and consumer discretionary (XLY). They are commonly benchmarked against SPDR S&P 500 (SPY), which represents the overall market.
Do any sector ETFs reliably lead or lag the overall stock market?
Sector ETFs show little evidence of reliably leading or lagging the overall U.S. stock market. In an analysis of the nine Select Sector SPDR ETFs against SPY from December 1998 through August 2021, offset correlations other than coincident ones appeared to be noise. The only hint of a pattern was a slight tendency for utilities to lag the market by one month.
How do you test whether a sector leads or lags the market using offset correlations?
Offset correlation testing compares monthly sector ETF returns with SPY monthly returns shifted by intervals from -12 months (sector lags the market) to +12 months (sector leads the market). A systematic lead-lag relationship of a year or less should appear as a notably positive or negative correlation at some offset. The study used monthly dividend-adjusted closing prices from December 1998 (sector ETF inception) through August 2021.
Why are utilities, consumer staples and energy sector ETFs the best candidates for leading or lagging the market compared with other sectors?
Utilities, consumer staples and energy ETFs had the lowest coincident monthly return correlations with SPY among the nine sectors, making them the best candidates for lead-lag behavior. Utilities are arguably somewhat bond-like, while energy and staples are somewhat commodity-like. By contrast, consumer discretionary, industrial and technology had the highest coincident correlations with SPY, and in every group the coincident correlation dominated.
What are the limitations of using sector ETF correlations to find market leaders and laggers?
The main caveat is that the sample is small in terms of the number of underlying business/economic cycles, covering about 23 years from December 1998 to August 2021. Other ways of specifying sectors or industries may also produce different results. Additionally, a slight scalloping pattern in offset correlations may be associated with synchronized dividends rather than true lead-lag behavior.