
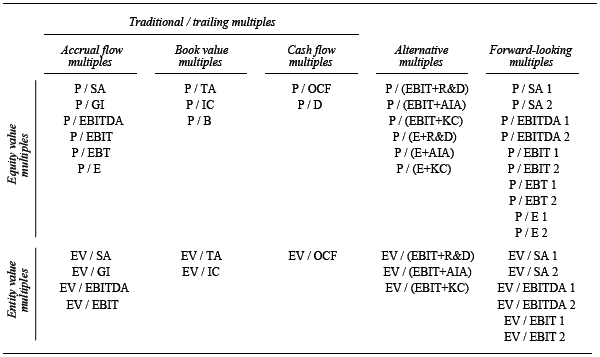
How well do commonly used valuation multiples align with actual stock prices? In their January 2007 paper entitled “Multiples and Their Valuation Accuracy in European Equity Markets”, Andreas Schreiner and Klaus Spremann investigate the accuracy of the valuation multiple method in general and the properties of 50 different multiples (see the figure below). They define a valuation multiple as a market price variable (e.g., stock price) divided by a particular value driver (e.g., earnings). Using stock price and firm financial data over the period 1996-2005 primarily for the Dow Jones STOXX 600 (ten industries, 18 supersectors, 39 sectors, and 104 subsectors) and secondarily for the S&P 500 index, they find that:
- Valuation multiples align with market value fairly well, with median absolute valuation errors less than 30%.
- Equity value (market capitalization) multiples outperform enterprise value multiples due to noise in the enterprise value data.
- In science/technology-based industries, knowledge-related multiples (which augment earnings by adding research and development costs and intangible asset amortization) outperform multiples using unadjusted earnings.
- Forward-looking multiples (using projections of a driver variable, such as earnings), in particular the two-year forward-looking price-earnings ratio (P/E), outperform multiples using trailing data.
- Multiples based on value drivers closer to bottom line income outperform multiples based on value drivers further up in the income statement.
- Multiples based on earnings clearly outperform those based on book value and cash flow.
- U.S. results are similar, with valuation multiples even more accurate than elsewhere, indicating that: (1) the widespread use of P/E and the price-book value ratio (P/B) influences U.S. stock prices; and, (2) analyst earnings forecasts better reflect firm value for U.S. stocks than for European stocks.
The following table, taken from the paper, summarizes the valuation multiples that the authors investigate, with definitions as follows: P = stock price; EV = enterprise value; SA = sales or revenues; GI = gross income; EBITDA = earnings before interest, taxes, depreciation and amortization; EBIT = earnings before interest and taxes; EBT = earnings before taxes; E = earnings available to common shareholders; TA = total assets; IC = invested capital; B = book value of common equity; OCF = operating cash flow; D = ordinary cash dividend; R&D = research & development expenditures; AIA = amortization of intangible assets; and, KC = knowledge costs (R&D + AIA). Forward-looking multiples use mean analyst forecasts for the next one (1) or two (2) years.
In summary, P/E using two-year forward earnings estimates is among the best indicators of firm market value. For technology firms, adjusting earnings to include investments in intellectual property enhances valuation accuracy.