
Are momentum trading strategies reliable and economically significant after trading frictions for large-capitalization stocks? In his November 2006 paper entitled “Alpha Generating Momentum Strategies”, Gregor Obrecht test 32 momentum trading strategies on large-capitalization U.S. stocks. The strategies encompass all combinations of: formation periods of three, six, nine and 12 months; wait periods of zero months and one month; and, holding periods of three, six, nine and 12 months. Using monthly returns for S&P 100 stocks over the period 12/85-8/06, he concludes that:
- All 32 hedge portfolios that are long (short) the tenth of stocks with the highest (lowest) momentum generate positive alpha before trading frictions. Results for 16 of 32 such portfolios are statistically significant. Use of a one-month wait period appears to be advantageous only for short holding periods.
- Focusing on the strategy using a six-month formation period, zero wait period and six-month holding period:
- Momentum returns are significant over 12/85-12/94 and 1/95-8/00 subperiods, but they disappear for 9/00-8/06. The most likely explanation for the breakdown is that momentum does not work during bear markets.
- Among large-capitalization stocks, momentum effects may be strongest in June, July and September.
- Adjustments for market, size and book-to-market risk factors do not explain momentum returns.
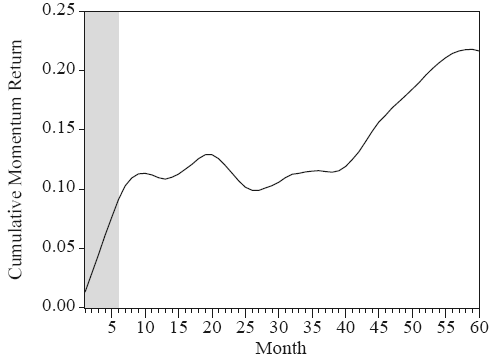
- Momentum returns are more likely an adjustment to past underreaction than an overreaction to recent events (see chart below).
- Inclusion of reasonable trading frictions leaves a net alpha of 2.33% over six months (growing to 7.55% for a 10-month holding period).
The following chart, taken from the paper, shows the average cumulative return over 60 months after hedge portfolio formation based on past six-month momentum with no wait period. The shaded area indicates a nominal six-month holding period, which captures most of the abnormal returns available over the first year. Because the cumulative return does not revert toward zero, results suggest that momentum reflects adjustment to past underreaction rather than an overreaction in and of itself. Note that this figure omits the most recent 60 months of data in the sample due to unavailability of returns for the entire cumulative return window.
In summary, momentum trading strategies generally offer significantly positive alpha for large-capitalization U.S. stocks, but the strategies may not work during bear markets.
Frequently Asked Questions
What is a momentum trading strategy in investing?
A momentum trading strategy buys stocks with the strongest past returns and shorts stocks with the weakest past returns, expecting recent winners and losers to keep their direction. In the studied S&P 100 research, hedge portfolios went long the tenth of stocks with the highest momentum and short the tenth with the lowest. Strategies were defined by a formation period (3, 6, 9 or 12 months), a wait period (0 or 1 month) and a holding period (3, 6, 9 or 12 months).
Do momentum strategies still generate alpha for large-cap stocks after trading costs?
Momentum strategies on large-cap S&P 100 stocks generally produce positive alpha even after reasonable trading frictions, though results may fail in bear markets. Over 12/85-8/06, all 32 tested hedge portfolios had positive alpha before frictions, and 16 of 32 were statistically significant. The six-month formation, zero wait, six-month holding strategy retained a net alpha of 2.33% over six months, growing to 7.55% for a 10-month holding period.
How are momentum strategies tested on S&P 100 stocks?
Momentum strategies on S&P 100 stocks were tested using monthly returns from 12/85 to 8/06 across 32 combinations of formation, wait and holding periods. Each combination formed a hedge portfolio that was long the highest-momentum decile and short the lowest-momentum decile. Alpha was measured before and after reasonable trading frictions, and returns were adjusted for market, size and book-to-market risk factors.
Is momentum an underreaction or an overreaction in stock prices?
Momentum in large-cap stocks looks more like an adjustment to past underreaction than an overreaction to recent events. Average cumulative hedge portfolio returns over the 60 months after formation (six-month momentum, no wait period) did not revert toward zero, which would have signaled overreaction. Most abnormal returns were captured within the first year, and market, size and book-to-market risk factors did not explain them.
Why might momentum strategies stop working for large-cap stocks?
Momentum strategies for large-cap stocks may fail during bear markets, which is the most likely explanation for the breakdown seen in 9/00-8/06. The six-month formation, zero wait, six-month holding strategy was significant over 12/85-12/94 and 1/95-8/00 but disappeared in that last subperiod. A further caveat is that the cumulative return chart omits the most recent 60 months of the sample because returns for the full window were unavailable.