
How do pension funds, arguably representative of sophisticated and conservative investors, use real estate as an alternative investment? In their January 2012 paper entitled “Value Added From Money Managers in Private Markets? An Examination of Pension Fund Investments in Real Estate”, Aleksandar Andonov, Piet Eichholtz and Nils Kok investigate the allocation, costs and performance of pension funds with respect to real estate investments. Using self-reported investment data for 884 U.S., Canadian, European and Australian/New Zealand pension funds during 1990 through 2009, they find that:
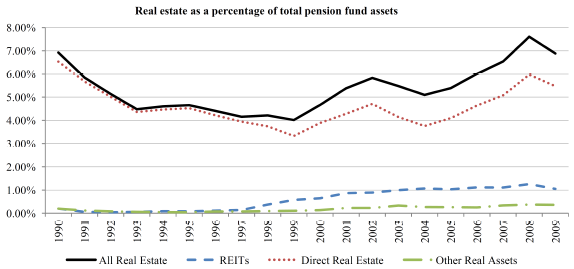
- Real estate is the most important asset class after equity and bonds, representing on average 4% to 7% of pension fund assets over the sample period (see the first chart below). About 75% of funds invest in real estate.
- Direct real investments dominate positions in Real Estate Investment Trusts (REIT) for pension funds. Large funds are more likely to invest in REITs. Small funds seem not to recognize that REIT returns match those of externally managed direct holdings and beat those of funds-of-funds, but at much lower cost.
- Pension fund allocations to real estate are predominantly active (adjusted tactically) rather than passive.
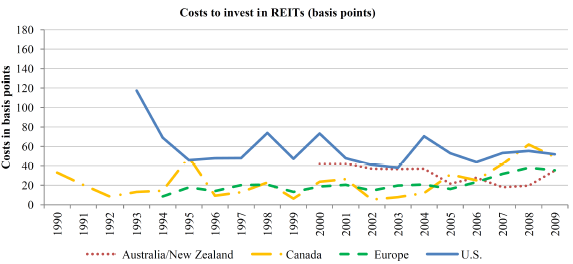
- The average cost to pension funds of investing in real estate is 0.76% per year, higher for direct investments (0.83%) than for REITs (0.41%). See the second chart below. Real estate investment costs are signi cantly lower than those for private equity and hedge funds.
- Over the entire sample period, the average annual gross return to pension funds from real estate investments is about 7%, with REITs (10.9%) outperforming direct investments (6.7%). Funds-of-funds substantially underperform alternatives by over 2% per year due to multiple layers of fees.
- Pension funds exhibit strong persistence in real estate investment performance, mainly due to direct real estate investments. There is no persistence in REIT investment performance, suggesting lack of informational advantage for that category.
The following chart, taken from the paper, summarizes average pension fund allocation to real estate investments during 1990 through 2009, with a breakdown into direct holdings and REITs. The overall average allocation across all years is 5.4%. Though presenting higher investment costs, direct real estate holdings dominate, perhaps because of potential informational advantages.
The next chart, also from the paper, tracks the average pension fund cost for investing in REITs by geographical region. Costs for investing in REITs are much lower than those for direct real estate holdings and funds-of-funds.
In summary, evidence from pension fund holdings suggests that modest allocations to REITs may be a cost-effective way to maintain exposure to real estate as an asset class.
Cautions regarding findings include:
- Individual investors may hold leveraged (mortgaged) direct real estate positions via homes that are much larger than the average allocations described above, thereby obviating the need for further exposure to real estate.
- As noted in the paper, return estimates do not account for any performance fees due to external managers. Such fees would reduce reported returns.
- The sample period is not long in terms of demographic and policy pressures.
Frequently Asked Questions
What is a REIT and how do pension funds use real estate as an investment?
A Real Estate Investment Trust (REIT) is a listed vehicle that gives investors exposure to real estate, and pension funds use it as one of several ways to hold real estate alongside direct holdings and funds-of-funds. In a sample of 884 pension funds from 1990 through 2009, real estate averaged 4% to 7% of fund assets (5.4% overall), making it the most important asset class after equities and bonds. About 75% of funds invested in real estate.
Do REITs outperform direct real estate investments for pension funds?
REITs outperformed direct real estate investments for pension funds in this study, with average annual gross returns of 10.9% versus 6.7% over 1990 through 2009. The sample covered 884 U.S., Canadian, European and Australian/New Zealand pension funds. The return estimates do not account for performance fees paid to external managers, which would reduce reported returns.
How is pension fund real estate performance and cost measured and compared?
Pension fund real estate performance and cost were measured using self-reported investment data from 884 pension funds in the U.S., Canada, Europe and Australia/New Zealand during 1990 through 2009. The study compared average annual gross returns and costs across direct investments, REITs and funds-of-funds, and also tested whether performance persisted over time. Average real estate costs were 0.76% per year, with direct investments at 0.83% and REITs at 0.41%.
How do REITs compare to direct real estate and funds-of-funds in cost and returns?
REITs were cheaper and earned higher gross returns than direct real estate in the pension fund data, at 0.41% versus 0.83% annual cost and 10.9% versus 6.7% annual return. Funds-of-funds underperformed alternatives by over 2% per year because of multiple layers of fees. Performance persisted for direct real estate but not for REITs, which suggests no informational advantage in the REIT category.
What are the limitations of using pension fund data to decide on REIT versus direct real estate investing?
The pension fund findings have limits: return estimates exclude performance fees paid to external managers, which would lower reported returns, and the 1990 through 2009 sample is not long in terms of demographic and policy pressures. The data are also self-reported. Individual investors may already hold large leveraged direct real estate positions through their homes, which can reduce their need for additional real estate exposure beyond the modest allocations pension funds use.