
How far can a fund manager squeeze turnover while still maintaining an effective low-volatility portfolio? In his June 2015 paper entitled “Low Turnover: a Virtue of Low Volatility”, Pim van Vliet investigates the lower limit of turnover for a low-volatility stock portfolio in two ways. First, he reviews 21 published analyses to relate turnover to volatility reduction while controlling for other factors. Second, he directly relates turnover and volatility reduction for an equally weighted portfolio that: (1) initially selects the 500 of 3,000 liquid global stocks with the lowest weekly volatility over the prior three years; and, (2) each subsequent month rebalances stocks that have at least doubled their baseline portfolio weight and sells stocks when they fall out of the top X% of the volatility ranking, with X varying from 20% (baseline) to 90%. He also models the costs of maintaining low-volatility stock portfolios. Using findings from 13 academic journal articles and working papers and weekly returns for the 3,000 most liquid global stocks during January 1989 through December 2013, he finds that:
- The 21 published analyses report volatility reductions ranging from 19% to 37% and turnover ranging from 19% to 119%. There is a weak concave relationship between volatility reduction and turnover (see the chart below), but the relationship does not survive robustness tests. Overall, it appears that 25% volatility reduction is achievable with 30% turnover.
- New empirical tests show that:
- The market portfolio has an annual turnover of about 5% due to initial public offerings, delistings and reinvestment of dividends.
- The baseline low-volatility portfolio specified above produces a 28% reduction in volatility with an annual turnover of 32%.
- Sensitivity testing indicates that the first/second/third 10% increments of turnover yield 22.5%/3.5%/2.0% increments in volatility reduction.
- Low-volatility investors should be skeptical if the turnover of a low-volatility index/strategy significantly exceeds 30%. Higher turnover could derive from sector/country concentration limits and/or exposure to factors such as value and momentum.
- Because low-volatility stocks tend to have much larger capitalizations than high-volatility stocks, they also tend to be more liquid and less costly to trade.
The following scatter plot, taken from the paper, summarizes the relationship between volatility reduction (compared to the market portfolio) and turnover for 21 low-volatility portfolios in published research. Results suggest that most of the volatility reduction benefits (the cluster of points on the left) are achievable with modest turnover.
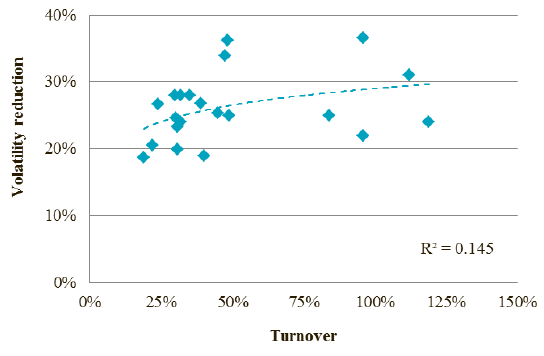
In summary, evidence from prior research and modeling suggests that 30% annual turnover should be sufficient to reduce portfolio volatility by 25% compared to a market-weighted index.
Cautions regarding findings include:
- Data/processing/capital requirements to construct and maintain a diversified low-volatility portfolio are beyond the reach of most investors. Delegating this work to a fund manager incurs fees, raising the cost of holding the portfolio.
- Testing many variations of a strategy on the same data introduces snooping bias, such that the best outcome likely overstates expectations.
- Findings may not hold for other asset classes.
Frequently Asked Questions
What is a low-volatility stock portfolio and what does portfolio turnover mean for it?
A low-volatility stock portfolio holds stocks with the lowest historical price variability, selected here as the 500 of 3,000 liquid global stocks with the lowest weekly volatility over the prior three years. Turnover is the share of the portfolio traded each year, and the market portfolio itself has only about 5% annual turnover from IPOs, delistings and dividend reinvestment.
How much turnover is needed to reduce portfolio volatility with low-volatility stocks?
A low-volatility stock portfolio can achieve about 25% volatility reduction with roughly 30% annual turnover, per Pim van Vliet's review of 21 published analyses and his own tests. His baseline portfolio cut volatility by 28% with 32% annual turnover over January 1989 to December 2013. Most of the benefit comes from modest turnover, though the weak concave relationship across studies did not survive robustness tests.
How is a low-turnover low-volatility stock portfolio constructed and tested?
The tested low-volatility portfolio is equally weighted and starts with the 500 of 3,000 liquid global stocks having the lowest weekly volatility over the prior three years. Each month it rebalances stocks that have at least doubled their baseline weight and sells stocks that fall out of the top X% of the volatility ranking, with X ranging from 20% (baseline) to 90%. The test uses weekly returns from January 1989 through December 2013 and is supplemented by a review of 21 published analyses.
Why do some low-volatility indexes have higher turnover than 30%, and how does that compare with the market portfolio?
Low-volatility indexes or strategies with turnover well above 30% warrant skepticism, since the market portfolio turns over only about 5% a year. Higher turnover may come from sector or country concentration limits and/or exposure to other factors such as value and momentum. Sensitivity tests show diminishing returns: successive 10% turnover increments add 22.5%, 3.5% and 2.0% of volatility reduction.
What are the limitations and risks of building a low-volatility stock portfolio with low turnover?
The data, processing and capital requirements for a diversified low-volatility portfolio are beyond the reach of most investors, and delegating to a fund manager incurs fees that raise holding costs. Testing many strategy variations on the same data introduces snooping bias, so the best outcome likely overstates expectations. The findings may also not hold for other asset classes.