
The Simple Asset Class ETF Momentum Strategy (SACEMS) each month picks the one, two or three of nine asset class proxies with the highest cumulative total returns over a specified lookback interval. A subscriber proposed instead using the optimal intrinsic (time series or absolute) momentum lookback interval for each asset rather than a common lookback interval for all assets. SACEMS and the proposed approach represent different beliefs (which could both be somewhat true), as follows:
- Many investors adjust asset class allocations with some regularity, such that behaviors of classes are important and coordinated.
- Many investors switch between specific asset classes and cash with some regularity, such that each class may exhibit distinct times series behavior.
To investigate, we consider two ways to measure intrinsic momentum for each asset class proxy:
- Correlation between next-month return and average monthly return over the past one to 12 months. The lookback interval with the highest correlation has the strongest (linear) relationship between past and future returns and is optimal.
- Intrinsic momentum, measured as compound annual growth rate (CAGR) for a strategy that is in the asset (cash) when its total return over the past one to 12 months is positive (zero or negative). The lookback interval with the highest CAGR is optimal.
We use the two sets of optimal lookback intervals (optimization-in-depth) to calculate momentum for each asset class proxy as its average monthly return over its optimal lookback interval. We then compare performance statistics for these two alternatives to those for base SACEMS, focusing on: gross CAGR for several intervals; average gross annual return; standard deviation of annual returns; gross annual Sharpe ratio; and, gross maximum drawdown (MaxDD). Using monthly dividend-adjusted prices for SACEMS asset class proxies during February 2006 through September 2019, we find that:
Per prior research, SACEMS portfolios each month hold the Top 1, equally weighted (EW) Top 2 or EW Top 3 assets based on 4-month past returns from among the following eight exchange-traded funds (ETF) plus cash:
- PowerShares DB Commodity Index Tracking (DBC)
- iShares MSCI Emerging Markets Index (EEM) until December 2007, and iShares JPMorgan Emerging Markets Bond Fund (EMB) thereafter
- iShares MSCI EAFE Index (EFA)
- SPDR Gold Shares (GLD)
- iShares Russell 2000 Index (IWM)
- SPDR S&P 500 (SPY)
- iShares Barclays 20+ Year Treasury Bond (TLT)
- Vanguard REIT ETF (VNQ)
- 3-month Treasury bills, or T-bills (Cash)
Availability of DBC determines beginning of the sample period, and return calculations start in March 2007 to accommodate the longest (12-month) lookback interval. Calculations assume that past returns and portfolio reformation occur at the same monthly close (winners can be slightly anticipated) and ignore trading frictions and tax implications. The risk-free rate for a year in Sharpe ratio calculations is the average monthly T-bill yield during that year.
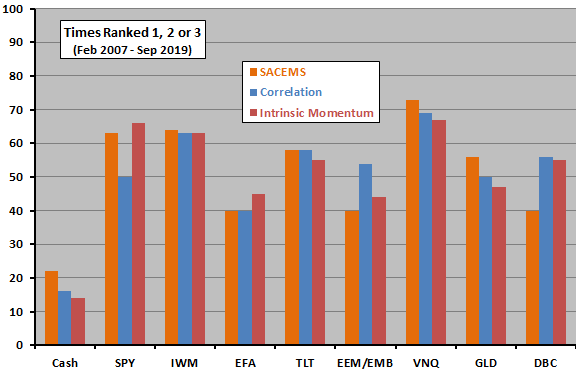
The following chart compares distributions of monthly top three assets across the three strategies over the full sample period. Overall, distributions are similar. The clearest difference is that optimization-in-depth strategies tilt more toward (non-gold) commodities than does base SACEMS.
A principal difference between correlation and intrinsic momentum optimizations-in-depth is an assumption of linearity in relationships between past returns and next-month returns for the former.
How do these distributions translate into performance?
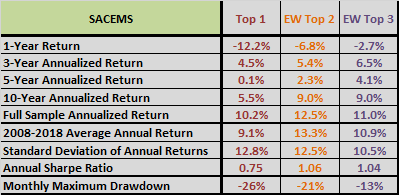
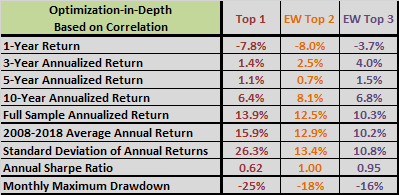
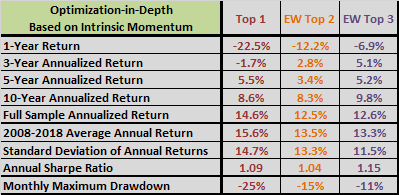
The following three tables summarize gross performance statistics for base SACEMS (upper chart), optimization-in-depth via correlation (middle chart) and optimization-in-depth via intrinsic momentum (lower chart) over the full sample period. Overall, the last alternative wins, though with especially weak recent performance.
However, in-sample optimization impounds data snooping bias, and optimization-in-depth involves much more snooping that does base SACEMS (eight parameters versus one). It is reasonable to suspect that some or all of any improvement is due to snooping bias (lucky choices).
Out-of-sample testing would alleviate snooping bias. For example, re-estimating optimal intervals periodically (say, monthly or annually) using only past data and applying these intervals to future months. However, the available sample is so short (fewer than 13 independent 12-month lookback intervals) that out-of-sample testing is problematic. Also, re-estimation of optimal intervals is burdensome.
As a simple robustness test, we see whether optimal intervals are similar for the first and second halves of the available sample.
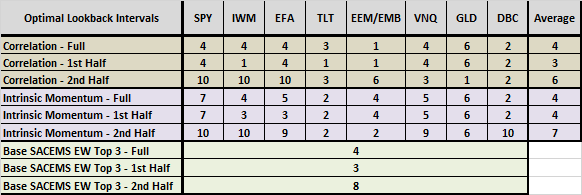
The final table shows optimal lookback intervals by asset class proxy for the full sample period and the first and second halves of the sample period (break point at the end of May 2013) for both optimization-in-depth alternatives. For comparison, it also shows optimal lookback intervals for the base SACEMS EW Top 3 portfolio (based on CAGR) over the same periods. In general:
- Full sample and first half optimal intervals are similar, and shorter than second half optimal intervals.
- Differences in optimal intervals between the first and second halves are most pronounced for equities. The first half includes a deep and sharp equity bear market, and the second half is a fairly continuous bull market.
Taken together, these two results suggest that tuning to equity bear market conditions is more important than tuning to equity bull market conditions (see “Asset Class Momentum Faster During Bear Markets?”). However, subsamples have only six independent 12-month measurement intervals each, undermining belief in findings.
In summary, evidence indicates that, ignoring snooping bias, optimization of SACEMS lookback intervals by individual asset class proxy (optimization-in-depth) may be attractive. Available data do not support out-of-sample testing rigorous enough to mitigate concern about snooping bias.
Cautions regarding findings include:
- As noted, the available sample for the full SACEMS universe of ETFs is very short for discriminating between similar competing strategies.
- As noted, optimization-in-depth involves considerable data snooping (eight optimizations versus one for base SACEMS), arguably removing the “S” from SACEMS. A short sample exacerbates snooping bias. Drawing conclusions based on the above in-sample testing is risky.
See also:
- “Optimal Intrinsic Momentum and SMA Intervals Across Asset Classes”
- “Long-term Tests of Intrinsic Momentum Across Asset Classes”
Frequently Asked Questions
What is the Simple Asset Class ETF Momentum Strategy (SACEMS)?
The Simple Asset Class ETF Momentum Strategy (SACEMS) is a monthly rotation strategy that holds the top one, two or three of nine asset class proxies (eight ETFs plus cash) ranked by cumulative total return over a set lookback interval. The base version uses a 4-month lookback for all assets. The ETFs cover commodities, emerging market equities and bonds, developed market equities, gold, small caps, large caps, long-term Treasuries and REITs.
Does using a different momentum lookback interval for each asset improve asset class momentum strategy returns?
Asset-specific lookback intervals (optimization-in-depth) produced higher CAGR than base SACEMS over March 2007 to September 2019, with the intrinsic momentum version performing best overall, though with especially weak recent performance. However, the improvement may stem partly or wholly from data snooping bias, so the evidence is not conclusive. The available data do not support out-of-sample testing rigorous enough to confirm the gain.
How are optimal momentum lookback intervals determined for each asset class?
Optimal lookback intervals for each asset were determined two ways over lookbacks of one to 12 months. The first picks the interval with the highest correlation between next-month return and average monthly return over the past interval. The second picks the interval with the highest CAGR for a strategy that holds the asset when its past return is positive and cash otherwise. Each asset's momentum is then its average monthly return over its own optimal interval.
How does asset-specific momentum optimization differ from using one common lookback period for all assets?
A common lookback (base SACEMS) assumes asset classes behave in coordinated ways as investors reallocate across them, while asset-specific optimization assumes each class has distinct time series behavior as investors move between it and cash. Asset selection distributions were broadly similar, but the optimized versions tilted more toward non-gold commodities. The correlation method also assumes a linear relationship between past and future returns, which the intrinsic momentum method does not.
What are the risks of optimizing momentum lookback periods for each asset separately?
Optimizing lookback intervals for each asset involves substantial data snooping bias, since eight parameters are optimized versus one for base SACEMS, and some or all of the improvement may be due to lucky choices. The short sample (fewer than 13 independent 12-month lookback intervals, and only six per half-sample) makes out-of-sample testing problematic and weakens robustness checks. Optimal intervals also differed between the first and second halves of the sample, especially for equities, so drawing conclusions from the in-sample results is risky.