
Extended stock market index winning and losing streaks elicit speculation about pending reversals. Does evidence support the what-goes-up-must-come-down view that likelihood of reversal grows with streak duration and magnitude? To check, we examine the “modern” (since 1990) behaviors of the S&P 500 Index and NASDAQ Composite Index during the one and two trading days after winning and losing streaks of at least three days. Using daily closes, highs and lows for the S&P 500 Index and the NASDAQ Composite Index during January 1990 through June 2016 (6,681 trading days), we find that:
Testing assumptions are:
- Base future returns on the same index closes used for streak tabulations. In other words, a trader would have to determine streak status just before the close so that any associated trade takes place at the same close.
- Ignore overlap of streaks. For example, the first three days of all four-day streaks are included among three-day streaks. An investor could not know when a streak will end.
- Ignore trading frictions.
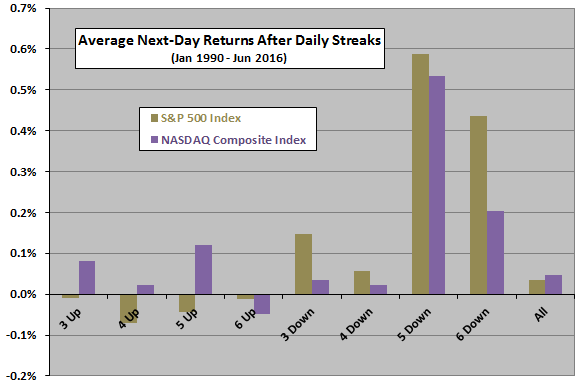
The following chart summarizes average S&P 500 Index and NASDAQ Composite Index next-day returns after up and down streaks of three to six days, and for all days, over the entire sample period. Samples of streaks longer than six days are small. Notable points are:
- For the S&P 500 Index, there is evidence of small reversals after up streaks and larger reversals after down streaks. The magnitude of reversal does not vary systematically with streak length.
- For the NASDAQ Composite Index, there is evidence of reversals only after long down streaks.
Most effects are small compared to trading frictions (which are likely larger after down streaks than up streaks due to widened bid-ask spreads).
For additional insight, we look at S&P 500 Index streak behavior in more detail.
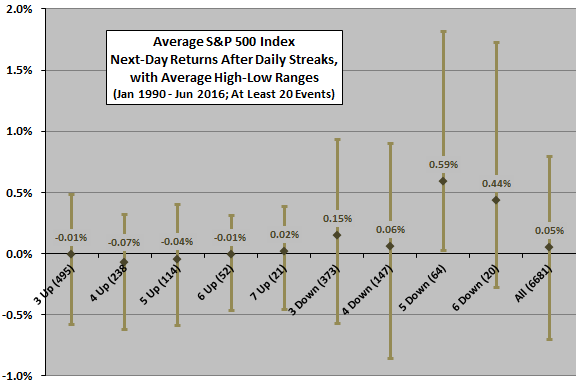
The next chart summarizes S&P 500 Index behaviors after up and down streaks for which there are at least 20 observations during the sample period, including:
- Number of observations (in parentheses on the horizontal axis).
- Average next-day return (data labels).
- Range of next-day returns measured from the prior close to next-day highs and lows (illustrated by variability ranges).
Notable findings are:
- As noted above, there is evidence of weak reversals after up streaks and stronger reversals after down streaks, but sample sizes are modest for the strongest of the latter.
- Ranges of next-day returns are much wider after down streaks than up streaks (market volatility is higher after down streaks).
- Ranges of next-day returns are skewed downward (unskewed or skewed upward) after up (down) streaks.
Do cumulative returns during streaks affect likelihood and magnitude of reversals?
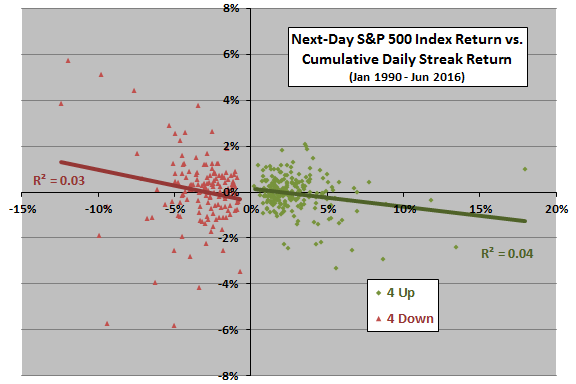
The following scatter plots relate S&P 500 Index next-day returns to cumulative returns during preceding 4-day up streaks (green diamonds) and 4-day down streaks (red triangles). Both relationships are negative, so the larger the magnitude of the cumulative return during the streak, the larger the magnitude of the next-day reversal.
However, the plots exhibit considerable dispersions and R-squared statistics indicate that cumulative return magnitudes explain only 3%-4% of next-day return magnitudes.
In summary, evidence from simple tests offers little support for belief that U.S. equity markets react reliably and exploitably after daily winning and losing streaks.
Cautions regarding findings include:
- As noted, sample sizes are very small for long streaks, limiting confidence in associated findings (and, in any case, offering only rare trades).
- Results may differ for other kinds of assets.
- To the extent that return distributions are wild (plausibly more so around streaks), normal statistics lose power as predictors.
Frequently Asked Questions
What is a stock market winning or losing streak?
A stock market winning (losing) streak is a run of consecutive trading days in which an index closes higher (lower) than the prior close. The article examines streaks of at least three days in the S&P 500 Index and NASDAQ Composite Index, tabulated from daily closes. Streaks are often thought to signal a pending reversal, which is the belief the article tests.
Do stock market streaks reliably predict next-day reversals?
Stock market streaks do not reliably predict exploitable next-day reversals. For the S&P 500 Index from January 1990 through June 2016, reversals were weak after up streaks and stronger after down streaks, and reversal size did not vary systematically with streak length. For the NASDAQ Composite Index, reversals appeared only after long down streaks, and most effects were small compared to trading frictions.
How do you test whether index streaks lead to reversals?
Streak reversals are tested by tabulating up and down streaks of at least three days from daily index closes and measuring average returns on the following one and two trading days. The article used S&P 500 and NASDAQ Composite data for January 1990 through June 2016 (6,681 trading days), with returns based on the same closes used to identify streaks. It also ignored overlap among streaks (e.g., three-day streaks include the first days of four-day streaks) and ignored trading frictions.
Do bigger cumulative returns during a streak cause bigger reversals, and how do up streaks compare with down streaks?
Larger cumulative returns during S&P 500 Index 4-day streaks are associated with larger next-day reversals, but the relationship explains little. Cumulative return magnitudes explain only 3%-4% of next-day return magnitudes (R-squared), with considerable dispersion. Down streaks show stronger reversals and much wider next-day return ranges than up streaks, reflecting higher market volatility after declines.
What are the limitations of trading stock market streak reversals?
Trading streak reversals is limited by small effects relative to trading frictions, which are likely larger after down streaks because of widened bid-ask spreads. Samples for long streaks are very small, limiting confidence and offering only rare trades, and results may differ for other asset types. If return distributions are wild, especially around streaks, normal statistics lose power as predictors.