
A reader requested a test of the TradingMarkets 5% VIX rule, which states:
“Do not buy stocks (or the market) anytime the VIX is 5% below its moving average. Why? Because since 1989, the S&P 500 cash market has “lost” money on a net basis 5 days following the times the VIX has been 5% below its 10 day ma.”
“Since 1989, whenever the VIX has been 5% or more above its 10 day ma, the S&P 500 has achieved returns which are better than 2 1/2 to 1 compared to the average weekly returns of all weeks.”
The reader also asked whether one can improve the signal by using a 4% or 6% threshold rather than 5%, or by using a holding interval longer or shorter than five days. We first reproduce the results claimed by TradingMarkets, then investigate whether the signals are of economic value to traders, and finally test sensitivity of results to parameter changes. Using daily CBOE Volatility Index (VIX) and S&P 500 index data for 1/2/90-7/11/07 (4415 trading days), we find that:
The following chart reproduces the TradingMarkets analysis. The average return for the S&P 500 index for all five trading-day intervals in the sample is 0.19%, with standard deviation 2.14%. The average return for the five trading-day holding intervals after 5% relative high (low) VIX rule signals is 0.49% (-0.02%), with standard deviation 2.45% (1.96%). Taken at face value, these results confirm the TradingMarkets conclusions. Note that actual volatility is higher (lower) than normal after high (low) VIX signals.
Is there any economic value in these results? In other words, are there any trading strategies here?
There are two issues with constructing trading strategies from these results:
(1) Standard deviations are large compared to the differences in mean returns. A trader must therefore systematically trade the signals many, many times (say >100) to cancel out the variability and achieve the indicated mean returns reliably. Short-term technical signals typically have this drawback.
(2) More critically, because the signals frequently come in bunches or streaks, there is a problem with the calculation of mean returns. In fact, there are more trading signals than there are five trading-day intervals in the sample. From a statistical perspective, there is serial correlation bias because returns for some days are included in more than one signaled holding interval. From a practical perspective, a trader cannot systematically act on all the signals because many signals occur while funds are still committed based on a prior signal.
To resolve the second problem, we eliminate streaks by thinning the signals such that no two signals fall within five trading days of each other. Specifically, we default to the first signal after any five trading-day gap and ignore any signals in the subsequent five trading days. This thinning reduces the number of high-VIX signals from 1,246 to 492, and the number of low-VIX signals from 1,080 to 364. The next chart shows the results. The mean return for the five trading days after high VIX signals falls from 0.49% to 0.25%, while the return after low VIX signals rises from -0.02% to 0.11%. Imposing an executable trading strategy therefore eliminates most of the anomaly identified by TradingMarkets.
How would trading on the thinned subsample of high-VIX signals compare to buy-and-hold?
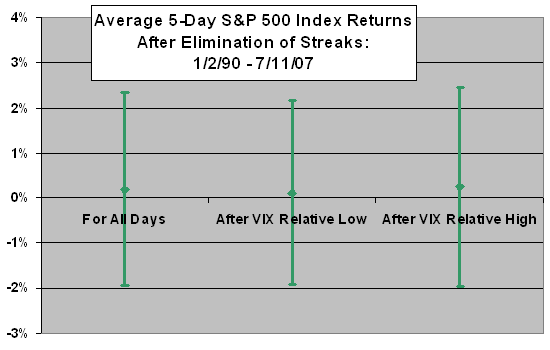
A buy-and-hold approach for the S&P 500 index generates a return of about 322% during 1/2/90-7/11/07. Buying and holding for five trading days whenever VIX is 5% above its ten-day moving average (based on the thinned, executable sample), generates a return of about 196% via 492 round-trip trades over the same period, far underperforming buy-and-hold. The high-VIX strategy underperforms because the stock market still rises on average during the 391 weeks that the strategy is on the sidelines. This calculation assumes for the high-VIX trading strategy that return on cash while out of the market offsets trading costs.
Is the relative VIX rule sensitive to the 5% threshold?
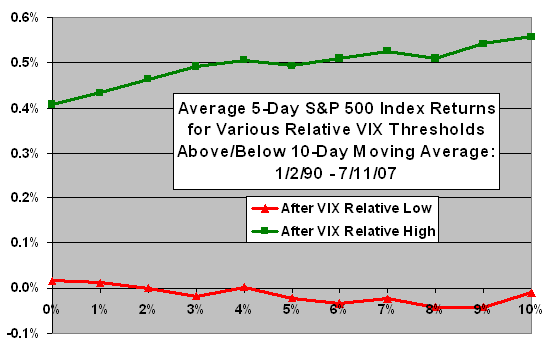
The following chart summarizes the effect on mean returns for the entire (unthinned) sample of varying the relative VIX threshold from 0% to 10% above/below the ten-day moving average. It shows that the uncorrected anomaly is fairly insensitive to the threshold level. Note that lower thresholds should generate more signals. Note also that thinning the signals to accommodate an executable trading strategy would likely make the differences in means between high-VIX signals and low-VIX signals for all threshold levels much smaller.
Is the relative VIX rule sensitive to the post-signal holding interval?
Using a ten trading-day holding interval instead of a five trading-day holding interval boosts the mean returns (and standard deviations of returns) for all cases: the mean return for all intervals increases from 0.19% to 0.39%; the mean return after high-VIX (5% threshold) signals increases from 0.49% to 0.66%; and, the mean return for the low-VIX signals increases from -0.02% to 0.29%. Again, the difference between the high-VIX and low-VIX means would likely dissipate if the signals were thinned to accommodate an executable trading strategy.
Note that the more parameter variations one tests against a given historical dataset, the greater the data mining bias (luck factor) in the best result and the more that best result overstates expected out-of-sample performance.
In summary, the TradingMarkets 5% VIX rule is of limited practical use and does not support a standalone trading strategy that keeps up with buy-and-hold.
Frequently Asked Questions
What is the relative VIX level and how is it used as a trading signal?
The relative VIX level compares the CBOE Volatility Index (VIX) to its own short-term moving average, such as the 10-day average. The TradingMarkets 5% VIX rule treats VIX at least 5% above (below) its 10-day moving average as a signal to buy (avoid buying) the S&P 500. The idea is that a relatively high VIX precedes better short-term stock returns.
Does the TradingMarkets 5% VIX rule beat buy-and-hold for the S&P 500?
The TradingMarkets 5% VIX rule does not beat buy-and-hold. Using executable (thinned) signals from 1/2/90 to 7/11/07, buying for five trading days after high-VIX signals returned about 196% via 492 round-trip trades, versus about 322% for buy-and-hold. The strategy lags because the market still rises on average during the 391 weeks it sits out.
How do you test a VIX moving average signal without double-counting overlapping trades?
The test thins the signals so no two fall within five trading days of each other, defaulting to the first signal after any five-day gap and ignoring signals in the following five days. This removes serial correlation bias from overlapping holding intervals and reflects that a trader cannot act on signals while funds are committed. Thinning cut high-VIX signals from 1,246 to 492 and low-VIX signals from 1,080 to 364, using daily VIX and S&P 500 data for 1/2/90-7/11/07 (4,415 trading days).
How do returns after high-VIX signals compare with returns after low-VIX signals and with all weeks?
Before thinning, the average five-day S&P 500 return was 0.49% after high-VIX signals, -0.02% after low-VIX signals, and 0.19% for all five-day intervals. After thinning to executable signals, the high-VIX mean fell to 0.25% and the low-VIX mean rose to 0.11%, eliminating most of the apparent gap. Volatility was also higher after high-VIX signals (standard deviation 2.45%) than after low-VIX signals (1.96%).
What are the limitations of using short-term VIX signals to trade the stock market?
Short-term VIX signals have large standard deviations (about 2% over five days) relative to differences in mean returns, so a trader would need to act on them well over 100 times to reliably capture the averages. Signals also come in streaks, which biases results unless thinned, and testing many thresholds (0% to 10%) and holding periods (5 or 10 days) on one dataset adds data mining bias that overstates expected out-of-sample performance. The rule is therefore of limited practical use as a standalone strategy.