
A reader inquired about the validity of Martin Zweig’s Four Percent Model, which states (from pages 93-94 of the 1994 version of Martin Zweig’s Winning on Wall Street):
“The Four Percent Model for the stock market works as follows. First, It uses the Value Line Composite Index…an unweighted price index of approximately seventeen hundred stocks… All you need to construct this model is the weekly close of the Value Line Composite. You can ignore the daily numbers if you wish… This trend-following model gives a buy signal when the weekly Value Line Index rallies 4% or more from any weekly close. It then gives a sell signal when the weekly close of the Value Line Composite drops by 4% or more from any weekly peak. …That’s all there is to it. …The model is designed to force you to stay with the market trend.”
We execute this description as follows (after identifying the first signal):
- After a buy signal, generate the next sell signal upon a 4% or greater decline from a subsequent high water mark (including the buy signal level).
- After a sell signal, generate the next buy signal upon a 4% or greater advance from a subsequent low water mark (including the sell signal level).
We test the usefulness of the signals on the following exchange-traded funds (ETF) over their entire available histories: SPDR S&P 500 (SPY), PowerShares QQQ (QQQ), iShares Russell 2000 Index (IWM) and Guggenheim S&P 500 Equal Weight (RSP). Using weekly closes of the Value Line Geometric Index and the dividend-adjusted weekly opens of the selected ETFs from their respective inceptions through September 2014, we find that:
In testing this indicator, we make the following assumptions for all trading vehicles:
- Execute weekly close signals at the open the next week.
- Cash earns the contemporaneous 13-week Treasury bill (T-bill) yield while out of stocks (a long only strategy).
- Consider both frictionless trading and various constant levels of trading friction for entering or exiting ETFs.
- Ignore tax consequences of trading.
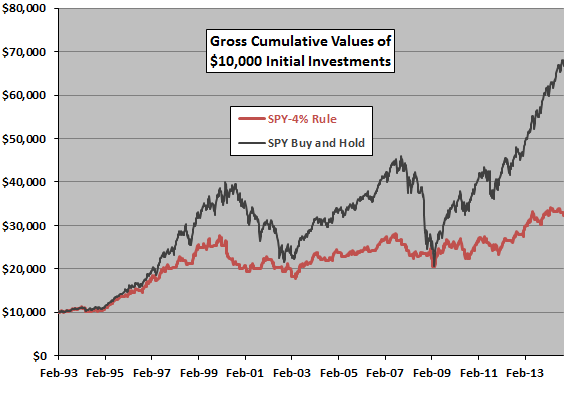
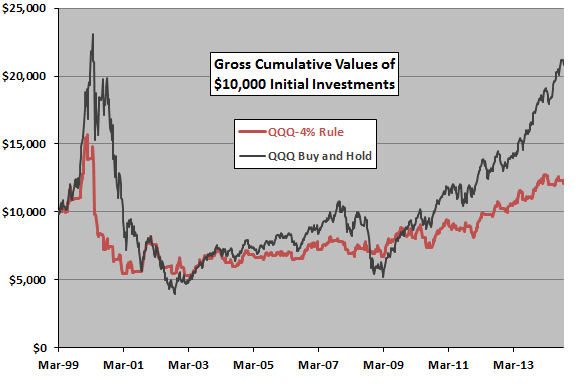
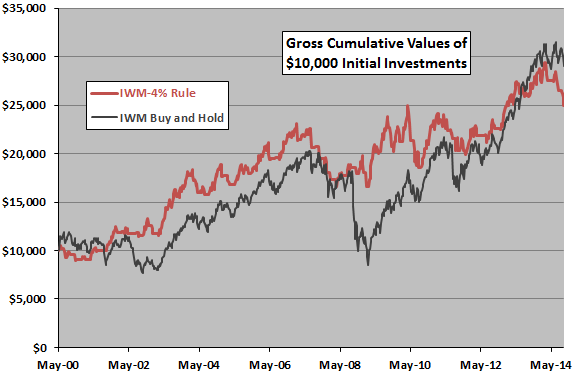
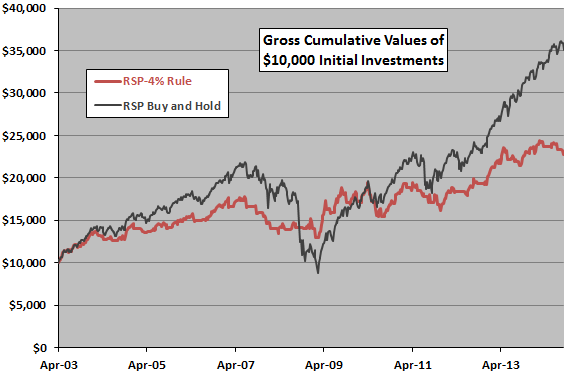
The following four charts track the gross performance of the 4% rule as applied to SPY, QQQ, IWM and RSP, respectively, over their available histories. The charts also show the performance of a respective buy-and-hold approach as a benchmark. Results suggest that the 4% rule applied to broad stock ETFs:
- Suppresses volatility and drawdowns but generally underperforms based on cumulative value.
- Works better in a sample with a higher proportion of equity bear market conditions, as for QQQ and IWM (see “The 2000s: A Market Timer’s Decade?”).
- Would work better when the sample period starts near a stock market peak.
For different perspectives, we consider and array of performance statistics.
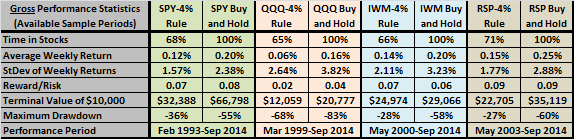
The following table summarizes gross performance statistics for the 4% rule as applied to the four ETFs, with statistics for corresponding buy-and-hold approaches as benchmarks. Results indicate that the 4% rule:
- Is in the ETFs about one third of the time, depending somewhat on the sample period.
- Generally underperforms buy-and-hold based on average gross weekly return.
- Generally suppresses weekly return volatility as measured by standard deviation (StDev) of weekly returns.
- Is generally competitive with buy-and-hold based on gross reward/risk (gross average weekly return divided by standard deviation of weekly returns).
- Generally loses to buy-and-hold based on terminal wealth.
- Generally reduces maximum drawdown substantially.
How strongly do trading frictions affect performance of the 4% rule?
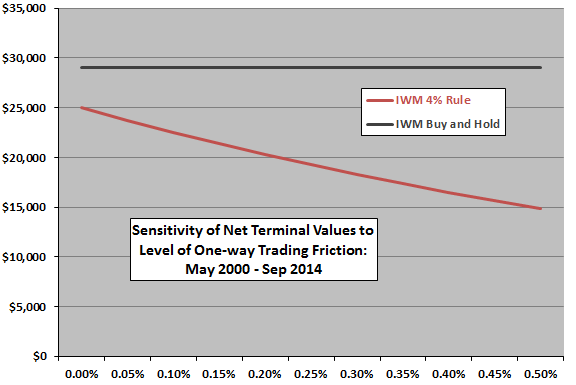
The final chart shows how the terminal value of the 4% rule applied to IWM (best case for the 4% rule among the four above) varies across levels of one-way trading frictions ranging from 0.00% (gross) to 0.50%. There are 50 buys and 50 sells over the sample period, such that the cumulative effect of trading frictions is material even for low frictions.
In summary, evidence from simple tests does not offer much support for belief that Martin Zweig’s Four Percent Model is a useful tool for stock market timing on a net basis.
A more positive view of the indicator may derive from snooping of the signal threshold within the discovery dataset, from ignoring trading frictions and/or from ignoring dividends.
Cautions regarding findings include:
- The source data for the Value Line Composite Geometric Index is not well documented. The Value Line Composite Arithmetic Index may generate different results.
- Some signal threshold other than 4% may work better, but empirical testing of different values would introduce data snooping bias into results.
- Given the volatility suppression, investors might consider using the 4% rule with leverage while in stocks to boost average return and terminal value (but leverage is not free).
- The extremely low return on cash during recent years adversely affects market timing rule performance.
Frequently Asked Questions
What is Martin Zweig's Four Percent Model for timing the stock market?
Martin Zweig's Four Percent Model is a trend-following market timing rule based on weekly closes of the Value Line Composite Index. It signals a buy when the index rallies 4% or more from a weekly low and a sell when it falls 4% or more from a weekly peak. The model is designed to keep an investor aligned with the prevailing market trend.
Does the Zweig Four Percent Model beat buy-and-hold investing?
The Zweig Four Percent Model generally underperforms buy-and-hold when applied to broad stock ETFs (SPY, QQQ, IWM and RSP) from inception through September 2014. It suppresses volatility and substantially reduces maximum drawdown, but loses to buy-and-hold on average weekly return and terminal wealth. Evidence offers little support for it as a useful timing tool on a net basis.
How do you test a 4% trend-following signal on stock ETFs?
The 4% signal is tested using weekly closes of the Value Line Geometric Index, with trades executed at the next week's dividend-adjusted open of ETFs such as SPY, QQQ, IWM and RSP. After a buy signal, a sell triggers on a 4% decline from a subsequent high; after a sell, a buy triggers on a 4% advance from a subsequent low. Cash earns the 13-week Treasury bill yield while out of stocks, and results are tested with frictionless trading and constant trading costs, ignoring taxes.
When does the Four Percent Model work better than buy-and-hold, and how do its risk-adjusted returns compare?
The Four Percent Model works better in samples with a higher proportion of equity bear markets, as with QQQ and IWM, and when the sample starts near a market peak. Its gross reward/risk (average weekly return divided by standard deviation) is generally competitive with buy-and-hold, even though its raw returns and terminal wealth are generally lower. The model is invested in the ETFs only about one third of the time.
What are the limitations and trading cost risks of using the Zweig Four Percent Model?
Trading frictions materially erode the Four Percent Model's performance, since even low costs compound over 50 buys and 50 sells in the IWM sample, its best case among the four ETFs. Other cautions include poorly documented Value Line Geometric Index source data, possibly different results with the Arithmetic Index, data snooping bias if other thresholds are tested, and low recent cash returns that hurt timing rules. Any positive view of the model may stem from threshold snooping, ignoring trading costs, or ignoring dividends.