
Is the conventional wisdom that stocks of certain sectors outperform systematically during specific stages of the business cycle correct, and exploitable? In the December 2009 update of their draft paper entitled “Sector Rotation across the Business Cycle”, Jeffrey Stangl, Ben Jacobsen and Nuttawat Visaltanachoti test the value of sector rotation by assuming that an investor anticipates U.S. business cycle stages perfectly and rotates sectors in accordance with conventional wisdom. The baseline business cycle consists of five stages across the peaks and troughs of economic activity declared by the National Bureau for Economic Research (NBER). The baseline conventional wisdom on sector rotation comes from Standard & Poor’s Guide to Sector Investing. Using monthly industry returns, market returns and Treasury bill rates for 1948-2007 (10 business cycles), they find that:
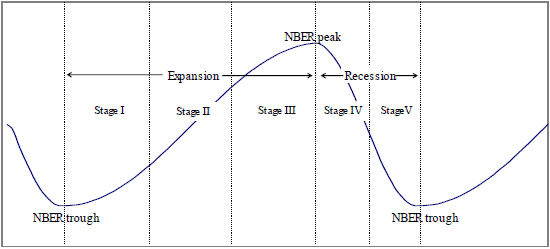
- The average length of U.S. business cycles since 1948 is 71 months, 61 months for expansions and 10 months for recessions (see the figure below).
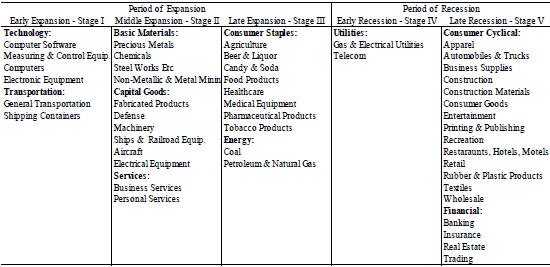
- On a nominal return basis, 33 of the 48 industries beat the market on average as expected during their optimal stages (see the table below). During late expansion, early recession and late recession (but not early and middle expansion), optimal industries in aggregate beat the market on average as expected.
- With perfect business cycle foresight, conventional sector rotation outperforms the market by a gross 2.3% per year over the entire 60-year sample period. However:
- This gross outperformance degrades to 1.9% and 1% (2.2% and 1.8%) per year when sector rotation is one and two months early (late), respectively.
- Including trading frictions degrades the 2.3% annual outperformance to between 1.1% and 1.9% (depending on assumptions), statistically indistinguishable from zero.
- Using the same perfect foresight to go to cash during early recessions and hold the market during all other business cycle stages outperforms the market by a gross 2.5% per year.
- Moreover, contrary to conventional wisdom, industries optimal for a particular stage mostly underperform the market (28 out of 48 sectors) based on Sharpe ratio. Across various risk-adjustment methods, there is very little evidence of industry outperformance by stage in accordance with conventional wisdom.
- Results are generally robust to alternate definitions of the business cycle and business cycle stages, subperiods, different risk adjustment approaches, different industry-business cycle relationships and different industry segmentations.
- There are a few sectors with significant alphas during particular stages of the business cycle (performing well 60%-70% of the time), as follows:
- Early expansion – none.
- Middle expansion – Candy & Soda and Pharmaceuticals.
- Late expansion – Mining and Tobacco Products.
- Early recession – Shipping Containers, Food products, Utilities and Entertainment.
- Late recession – Personal Services, Food Products and Tobacco Products.
- With perfect business cycle foresight, this alternative sector rotation outperforms the market by a gross 7.3% per year (about 6.1% per year after trading frictions) over the entire 60-year sample period.
The following figure, taken from the paper, presents the baseline idealized business cycle divided into five stages. Expansions span trough to peak in three stages of equal length (Stages I-III). Recessions span peak to trough in two stages of equal length (Stages IV-V). As indicated, expansions are typically much longer than recessions. Since 1948, U.S. expansions (recessions) average 61 (10) months in length.
The following table, also from the paper, summarizes the baseline conventional wisdom (from Standard & Poor’s Guide to Sector Investing) on outperformance of sectors by stage of the business cycle.
Note that NBER can take as long as two years after a turning point to designate its date and that one business cycle can be very different from another.
In summary, realistic assumptions about business cycle predictability make it unlikely that an investor can outperform the broad stock market using a conventional sector rotation strategy. A more focused, unconventional sector rotation strategy might outperform.
Frequently Asked Questions
What is sector rotation in investing?
Sector rotation is an investing strategy that shifts portfolio holdings among stock sectors or industries based on the stage of the business cycle. Conventional wisdom, such as that in Standard & Poor's Guide to Sector Investing, holds that certain sectors outperform during specific stages like early expansion, late expansion, or recession. The idea is to overweight whichever sectors are expected to lead at each stage.
Does sector rotation across the business cycle beat the market?
Conventional sector rotation beats the market only under unrealistic perfect business cycle foresight, outperforming by a gross 2.3% per year over 1948-2007. Once realistic timing errors and trading frictions are included, the outperformance falls to between 1.1% and 1.9% per year, which is statistically indistinguishable from zero. Realistic assumptions therefore make it unlikely that conventional sector rotation outperforms the broad market.
How do researchers test whether sector rotation strategies work?
Researchers in this study assumed an investor perfectly anticipates U.S. business cycle stages and rotates sectors according to conventional wisdom. They divided NBER-dated business cycles into five stages (three for expansions, two for recessions) and used monthly industry returns, market returns and Treasury bill rates for 48 industries over 1948-2007 (10 cycles). They then tested timing errors of one and two months early or late, trading frictions, and several risk-adjustment methods.
Is conventional sector rotation better than an unconventional, data-driven sector rotation strategy?
In this study, an unconventional strategy using only industries with significant alphas in particular business cycle stages did better than conventional sector rotation, but only with perfect foresight. It outperformed the market by a gross 7.3% per year (about 6.1% after trading frictions) over 1948-2007, versus 2.3% gross for the conventional approach. Going to cash only during early recessions and holding the market otherwise earned a gross 2.5% per year, also with perfect foresight.
What are the limitations and risks of sector rotation based on the business cycle?
Sector rotation depends on accurately timing business cycle stages, yet NBER can take up to two years to designate turning points and each cycle can differ greatly from another. Gross outperformance of 2.3% per year falls to 1.9% and 1% when rotation is one and two months early, and to 2.2% and 1.8% when late. Also, industries deemed optimal for a stage mostly underperformed the market on a Sharpe ratio basis (28 of 48), so there is little evidence of risk-adjusted outperformance by stage.