
Does the S&P 500 implied volatility index (VIX) behave predictably after up or down streaks? To check, we look at next-day percentage changes in VIX after up and down streaks ranging from two to seven trading sessions. To test exploitability, we repeat the analysis on the much shorter sample available for the iPath S&P 500 VIX ST Futures ETN (VXX). Using daily closes of VIX from the beginning of January 1990 and VXX from the end of January 2009, both through mid-November 2012, we find that:
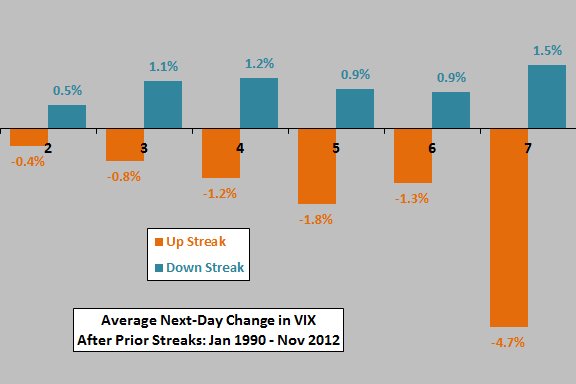
The following chart summarizes average next-day percentage changes in VIX after up and down streaks of two, three, four, five, six and seven trading sessions over the available sample period. The number of seven-day up (down) streaks is only 11 (46). The number of observations for streaks longer than seven sessions is too small for analysis. The average daily percentage change in VIX over the entire sample period is 0.19%.
Results consistently indicate that VIX tends to reverse after streaks, but the strength of reversal does not systematically increase with the length of the streak.
Is this reversion tendency exploitable via VXX?
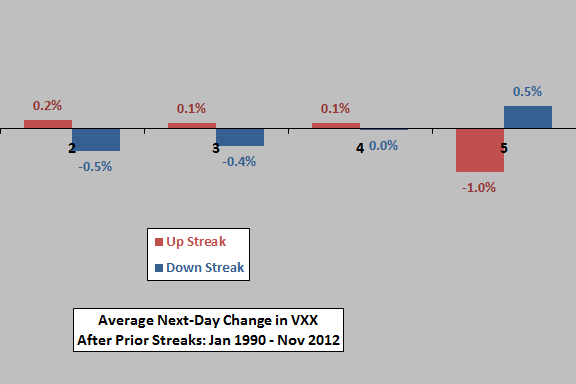
The next chart summarizes average next-day percentage changes in VXX after up and down streaks of two, three, four and five trading sessions over the available sample period. The number of five-day up (down) streaks is only 13 (72). The number of observations for streaks longer than five sessions is too small for analysis. The average daily percentage change in VXX over the entire sample period is -0.34%.
Results are very different from those for VIX. If anything, VXX exhibits some degree of momentum rather than reversion for most streak lengths. It appears that future traders anticipate the streak behaviors of VIX.
In summary, evidence from simple tests on available data indicates that VIX tends to revert after streaks, but the tendency is not exploitable via the futures-based VXX.
Cautions regarding findings include:
- As indicated, the number of observations for the longest up streaks is very small.
- The overall VXX sample is small in terms of number of VIX regimes.
See “Exploit Short-term VIX Reversion with VXX?” for closely related research on VIX reversion. See “Trade Stock Market Streak Reversals?” for similar analysis of U.S. stock market return streaks.
Frequently Asked Questions
What is the VIX and what does a VIX streak mean?
The VIX is the S&P 500 implied volatility index, a measure of expected stock market volatility. A VIX streak is a run of consecutive trading sessions in which the index rises (up streak) or falls (down streak). The article examined streaks of two to seven sessions using daily closes from January 1990 through mid-November 2012.
Does the VIX tend to reverse after consecutive up or down days?
The VIX tends to reverse after up and down streaks of two to seven trading sessions, based on daily closes from January 1990 to mid-November 2012. However, the strength of reversal does not systematically increase with streak length. The average daily VIX change over the full sample was 0.19%.
How do you test whether VIX streak reversion can be traded with VXX?
The test measures average next-day percentage changes in VIX after streaks of two to seven sessions, then repeats the analysis for the iPath S&P 500 VIX ST Futures ETN (VXX) after streaks of two to five sessions. The VXX sample runs from the end of January 2009 to mid-November 2012, and its average daily change over that period was -0.34%. Comparing the two shows whether VIX reversion carries over to a tradable instrument.
Why does VXX show momentum after streaks when the VIX shows reversion?
VXX tracks VIX futures rather than the VIX itself, and the article suggests futures traders anticipate the VIX's streak behavior. As a result, VXX exhibits some degree of momentum rather than reversion for most streak lengths, so the VIX reversion tendency is not exploitable via VXX. This is an interpretation of the pattern, not a proven cause.
What are the limitations of VIX streak reversion findings?
The number of observations for the longest streaks is very small, with only 11 seven-day up streaks and 46 seven-day down streaks in the VIX sample, and only 13 five-day up streaks in the VXX sample. The VXX sample is also small in terms of the number of VIX regimes it covers. Streaks longer than seven sessions for VIX and five for VXX had too few observations to analyze, and the tests are simple ones on available data.