
Several readers have requested that we evaluate the expertise of Mark Leibovit, Chief Market Strategist for VRTrader.com, According to VRTrader.com: “His technical expertise is in volume analysis, providing short-term, high performance stock trades and market timing…” Based on the information provided at VRTrader.com, especially the “Track Record” encompassing 3,388 round-trip trades during 2001-2007, we conclude that:
VRTrader.com’s approach is essentially momentum-aided volatility trading. We could measure the timing value of the trade advice by testing whether the prices of recommended stocks move in directions favorable to the trades immediately after trade entry dates. Such a test is very laborious, so we limit this analysis to broader trading statistics.
We assume that the “Track Record” reflects the advice offered via the “VR Platinum” service, which “offers specific recommendations, entry points, targets, stops for individual stocks and stock indexes (Exchange Traded Funds – ETFs) and other valuable information regarding short-term timing signals for the overall market. All of these are sent to your email, as well as being posted on the website. VR Platinum is published pre-market, post-market and on ‘as needed’ basis intra-day.”
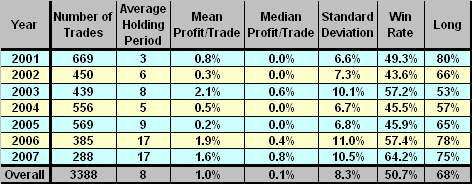
The following table summarizes raw statistics for the 3,388 round-trip trades. Note that:
- The average holding period (calendar days) for the entire sample is eight days, ranging from three days in 2001 to 17 days for 2006 and 2007. A longer holding period means lower portfolio turnover and slower compounding of returns.
- The mean profitability of all trades is 1.0%, ranging from 0.2% in 2005 to 2.1% in 2003. The relatively high mean trade profitability in 2006 and 2007 tends to offset the relatively long average holding periods in those years.
- The typical (median) trade is barely profitable and, in fact, is just breakeven in four of seven years.
- The standard deviation of trade returns, a measure of drawdown risk, is elevated for 2003, 2006 and 2007.
- The win rate is just over 50% overall and is less than 50% in four of seven years.
- Overall, about two thirds of trades are long, with the highest percentage of short trades (47%) coming in the most bullish year for the broad market (2003).
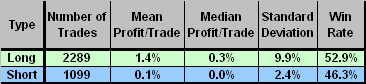
The next table provides statistics on long and short trades. It shows that long VRTrader.com trades are generally much more profitable than short trades, although with much greater variability in returns. Results suggest that subscribers may want to ignore recommendations for short trades.
Both the “Track Record” and the VRTrader.com disclaimer make clear that:
“THE RESULTS POSTED FOR VRTRADER.COM ARE HYPOTHETICAL. VRTrader.com cannot guarantee that any person bought or sold the actual security for the prices listed on the website or in email. No representation is being made that any subscriber or account will, or is likely to, achieve profits or losses similar to those shown. The prices listed are for reference only and are in no way intended to represent an actual trade, entry price or exit price. Unlike an actual performance record, simulated results do not represent actual trading and are not subject to liquidity issues.”
In other words, the “Track Record” excludes some trading frictions (bid-ask spread and impact of trading). For some of the stocks/ETFs recommended by VRTrader.com, bid-ask spreads should be very small and impacts of trading negligible. For others, these frictions may be substantial. A subsample of 61 long (seven short) trades ending during the last quarter of 2007 has an average exit price is notably closer to the trade date high (low) than the trade date low (high). This favorable trading may not be systematically achievable for real trades.
The trade profitability percentages also exclude broker transaction fees (changing the “Commission” variable for the “Track Record” does not change profitability percentages), subscription fees for the “VR Platinum” service (roughly $6 per round-trip trade) and additional costs for short sales.
The effect of total trading friction on profitability depends on trade size and specific broker fees. The following table summarizes the sensitivity of trading profitability to various assumed levels of total trading friction, as follows:
- As round-trip trading friction approaches 1% of trade size (0.5% for entry and 0.5% for exit), mean trade profitability approaches zero.
- The typical (median) trade produces a loss for most scenarios, with all win rates below 50%.
- Assuming a stable mean trade profitability and 20 portfolio turns per year, annual portfolio return approaches zero as round-trip trading friction approaches 1%. (For comparison, the annualized return of the S&P 500 index during 2001-2007 is about 1.5%.)
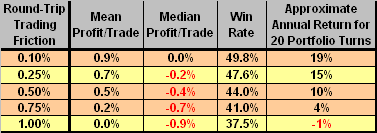
Given the variation in trade profitability, actual annual returns could vary widely from the approximations, with substantial account drawdowns. Also, the calculation in the table does not take into account the effect on overall portfolio return of open positions, which by definition are below some level of targeted profitability.
Finally, a trading strategy such as that offered by VRTrader.com obviously generates short-term capital gains, which may have adverse tax consequences compared to long-term buy and hold.
In summary, traders employing frequent trading strategies such as that offered by VRTrader.com must achieve low trading friction and be prepared for frequent losses and high return volatility among individual trades. Specifically for VRTrader.com, they may also want to ignore short trade recommendations.
Frequently Asked Questions
What is momentum-aided volatility trading?
Momentum-aided volatility trading is a short-term approach that tries to profit from price swings in individual stocks and ETFs, using momentum and volume signals to time entries and exits. CXO Advisory characterized VRTrader.com's approach this way, based on 3,388 round-trip trades during 2001-2007 with an average holding period of eight days.
Is VRTrader.com's trading strategy profitable after trading costs?
VRTrader.com's strategy is only marginally profitable before costs and approaches zero profitability after realistic costs. Its 3,388 trades during 2001-2007 averaged 1.0% profit per trade with a win rate just over 50%, but mean trade profitability approaches zero as round-trip trading friction nears 1% of trade size. At 20 portfolio turns per year, annual portfolio return also approaches zero at that friction level, versus about 1.5% annualized for the S&P 500 over the same period.
How do you test a stock trading track record for the effect of trading frictions?
The track record is tested by summarizing trade statistics (holding period, mean and median profitability, standard deviation, win rate, long versus short results) and then recalculating profitability under assumed levels of round-trip trading friction. In the VRTrader.com analysis of 3,388 trades, friction scenarios were applied to mean and median trade returns and win rates, and annual return was approximated assuming a stable mean trade profitability and 20 portfolio turns per year. This approximation ignores the effect of open positions on overall portfolio return.
Are long trades or short trades more profitable in a short-term trading strategy like VRTrader.com's?
In VRTrader.com's track record, long trades were generally much more profitable than short trades, though with much greater variability in returns. About two thirds of trades were long, and short trades were most common (47%) in 2003, the most bullish year for the broad market. The analysis suggests subscribers may want to ignore short trade recommendations.
What are the limitations of hypothetical trading track records like VRTrader.com's?
A hypothetical track record like VRTrader.com's excludes bid-ask spreads, market impact, broker commissions, subscription fees (roughly $6 per round-trip trade) and extra short-sale costs, and it is not subject to liquidity issues. A subsample of 61 long and seven short trades ending in late 2007 showed exit prices notably favorable relative to the trade date's range, which may not be systematically achievable in real trading. Returns are also short-term capital gains, which may carry tax disadvantages versus long-term buy and hold, and actual results could involve substantial drawdowns.