
What is Warren Buffett’s preferred fixed asset allocation, and how does it perform? In his October 2015 paper entitled “Buffett’s Asset Allocation Advice: Take It … With a Twist”, Javier Estrada examines Warren Buffett’s 2013 implied endorsement of a fixed allocation of 90% stocks and 10% short‐term bonds (90/10). Specifically, he tests the performance of eight fixed asset allocations ranging from 100/0 to 30/70. Testing assumes a $1,000 nest egg at retirement, a withdrawal rate of 4% of the initial amount adjusted annually for inflation and a 30‐year retirement. At the beginning of each year, the retiree makes the annual withdrawal and rebalances to the target allocation. The first 30‐year retirement interval is 1900‐1929 and the last 1985‐2014, for a total of 86 rolling intervals. He further explores two adjustments (twists) to the 90/10 allocation:
- T1 – If stocks are up the past year, take the annual withdrawal from stocks and rebalance to 90/10. If stocks are down, take the annual withdrawal from bonds and do not rebalance.
- T2 – If stocks outperform bonds the past year, take the annual withdrawal from stocks and rebalance to 90/10. If stocks underperform, take the annual withdrawal from bonds and do not rebalance.
Using U.S. stock market and U.S. Treasury bill (T-bill) annual real total returns as compiled by Dimson‐Marsh‐Staunton for 1900 through 2014, he finds that:
- Over the entire sample period, the U.S. stock market and T-bills have average annual real compound returns 6.5% and 0.9%, with annual volatility 20.0% and 4.6%.
- In a contest among fixed allocations:
- Only 60/40 has a 0% failure rate.
- 90/10 has low 2.3% failure rate (but not the lowest), high upside potential (but not the highest) and good downside protection (but not the best).
- In other words, 90/10 offers an attractive compromise between best upside potential (100/0) and best downside protection (60/40 and 70/30).
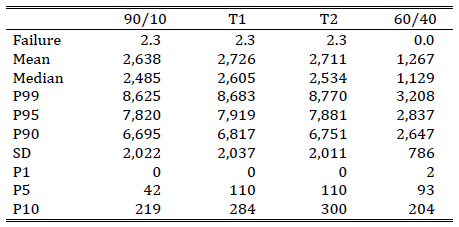
- Results for the two twists on 90/10 are similar (see the table below).
- Both have the same failure rate as 90/10.
- Compared to 90/10, both modestly enhance upside potential (mean, median, 99th, 95th and 90th percentile outcomes) and provide slightly better downside protection (5th and 10th percentile outcomes), with about the same volatility.
The following table, taken from the paper, summarizes performance statistics based on the test assumptions outlined above for 90/10, T1, T2 and 60/40 allocations over the entire sample period.
- The failure rate (Failure) is the percentage of 86 retirement intervals that run out of money before 30 years.
- The mean and median average terminal wealth in dollars show the typical retiree experience.
- The 99th percentile (P99), P95 and P90 terminal wealth in dollars show lucky retiree outcomes.
- P1, P5 and P10 terminal wealth in dollars show unlucky retiree outcomes.
Results show that 90/10, T1 and T2 are in most ways superior to a conventional 60/40 allocation.
In summary, available evidence indicates that Warren Buffett’s implied endorsement of a fixed 90/10 stocks/bonds allocation in retirement is sensible, and that simple adjustments to this strategy modestly improve retirement outcome.
Cautions regarding findings include:
- Performance data are gross, not net. Construction of a liquid tracking fund for the U.S. stock market and annual rebalancing frictions would lower performance (much less so in recent decades than before).
- The number of independent 30-year retirement intervals in the sample is small (less than four), so findings may not be representative of all retirements.
- Testing different strategies on the same data introduces snooping bias (luck), such that the best-performing strategy overstates expectations.
Frequently Asked Questions
What is a 90/10 stocks-bonds asset allocation in retirement?
A 90/10 stocks-bonds asset allocation is a fixed portfolio of 90% stocks and 10% short-term bonds, rebalanced annually to those targets, which Warren Buffett implicitly endorsed in 2013. In Javier Estrada's retirement test, a retiree withdraws 4% of the initial nest egg each year, adjusted for inflation, over 30 years.
Is a 90/10 stocks-bonds allocation a sound strategy for retirement withdrawals?
A 90/10 stocks-bonds allocation looks sensible for retirement, with a low 2.3% failure rate across 86 rolling 30-year retirement intervals from 1900 to 2014 using a 4% inflation-adjusted withdrawal rule. It is not the best on any single measure, but it offers a compromise between the upside of 100/0 and the downside protection of 60/40 and 70/30. Only 60/40 had a 0% failure rate.
How do you test a retirement asset allocation using rolling 30-year periods?
Rolling 30-year retirement testing assumes a $1,000 starting nest egg, a withdrawal of 4% of the initial amount adjusted annually for inflation, and annual rebalancing to the target allocation after each withdrawal. Estrada applied this to 86 overlapping intervals, from 1900-1929 through 1985-2014, using Dimson-Marsh-Staunton real total returns for U.S. stocks and T-bills. Failure rate is the percentage of intervals in which the money runs out before 30 years.
How does a 90/10 stocks-bonds allocation compare to a conventional 60/40 portfolio in retirement?
A 90/10 allocation has a 2.3% failure rate versus 0% for a 60/40 portfolio in the 86 rolling 30-year retirements tested, but offers higher upside potential. Estrada found 90/10 and its two timing twists superior to 60/40 in most ways. The twists, which choose whether to withdraw from stocks or bonds based on prior-year performance, matched 90/10's failure rate while modestly improving upside and downside outcomes with about the same volatility.
What are the limitations of backtesting a 90/10 stocks-bonds retirement allocation?
The 90/10 backtest uses gross returns, so tracking-fund construction costs and annual rebalancing frictions would lower real-world performance. The sample contains fewer than four independent 30-year retirement intervals, so results may not represent all retirements. Testing several strategies on the same data also introduces snooping bias, so the best-performing strategy overstates expected results.