
Does intensity of firm quarterly earnings releases affect stock market behaviors? A reader proposed the following stock market timing strategy based on a strictly calendar-based definition of earnings season: go short (long) the market at the close at the end of the first full week (sixth full week) of each calendar quarter, representing the beginning (end) of earnings season. The hypothesis is that the broad stock market performs poorly during earnings season and well outside of earnings season. Using weekly closes for the S&P 500 Index since January 1950 and for the S&P 500 Implied Volatility Index (VIX) since January 1990, both through June 2014, we find that:
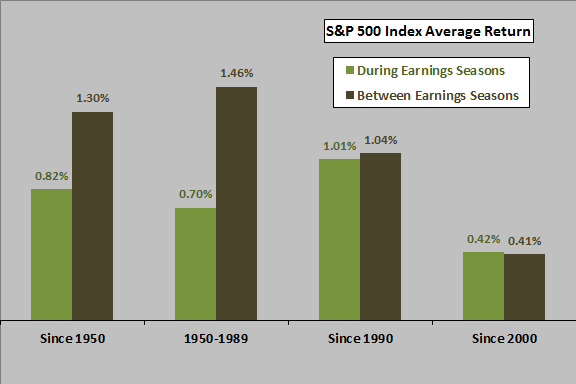
The following chart shows average returns for the S&P 500 Index during and between earnings seasons for four historical periods:
- Since 1950 (257 observations)
- During 1950-1989 (160 observations)
- Since 1990 (97 observations)
- Since 2000 (57 observations)
Periods between earnings seasons tend to generate greater returns than do earnings seasons. However, the early part of the sample period drives the overall difference. Results generally do not support shorting the market during earnings season.
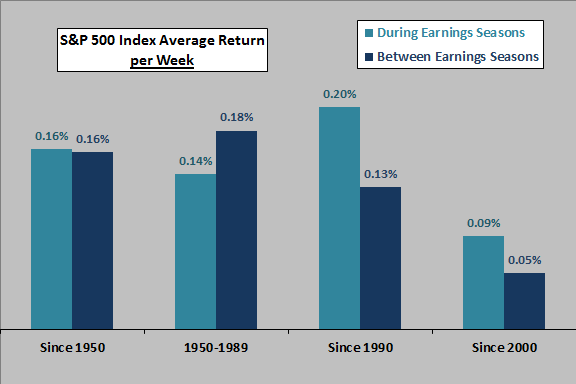
Since earnings seasons are on average about three weeks shorter than the intervals between earnings seasons, an interval comparison may mislead. What happens if we normalize based on average returns per week during and between earnings seasons?
The next chart shows the average normalized (per week) returns for the S&P 500 Index during and between earnings seasons for the same period and subperiods used above. There is no consistent difference in average stock market returns per week during and between earnings seasons. In recent subperiods, average returns are stronger during earnings season.
In case these aggregations miss some more granular pattern, we consider average returns by week across an earnings season-based quarter.
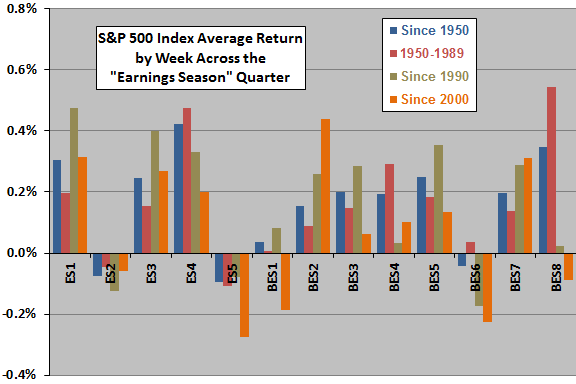
The next chart shows average returns for the S&P 500 Index by week during earnings seasons (weeks ES1 through ES5) and between earnings seasons (weeks BES1 through BES8) for the historical periods used above. There is some indication that the second and last weeks of earnings season and the first and sixth weeks between earnings seasons tend to be weak.
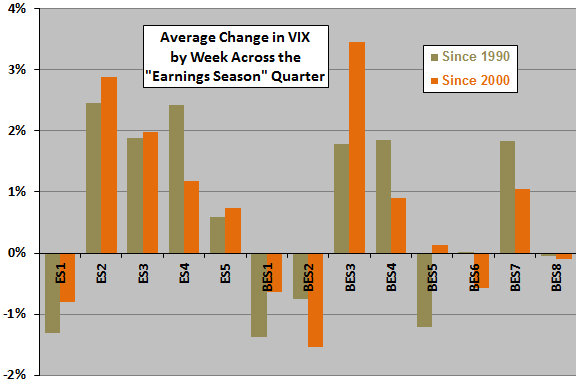
For a perspective on return volatility during and between earnings seasons, we look at weekly changes in VIX.
The final chart shows average changes in VIX by week during weeks ES1 through ES5 and weeks BES1 through BES8 since 1990 and since 2000. Results suggest that VIX tends to rise during most of earnings season and then fall after earnings season is over.
In summary, evidence from simple tests does not support a belief that the U.S. stock market is reliably weak (strong) during (between) earnings seasons.
Cautions regarding findings include:
- Recent subsamples are small in terms of secular market trends/conditions.
- Week-by-week results are particularly subject to data snooping bias (luck), such that results for extreme weeks likely overstate reasonable out-of-sample expectations.
Frequently Asked Questions
What is earnings season in the stock market?
Earnings season is the period each calendar quarter when most publicly traded firms release quarterly earnings reports. In the article's calendar-based definition, it begins at the end of the first full week of each calendar quarter and ends at the close of the sixth full week, spanning roughly five weeks (ES1 through ES5), with the remaining weeks (BES1 through BES8) falling between earnings seasons.
Does the stock market perform worse during earnings season than between earnings seasons?
The S&P 500 does not reliably perform worse during earnings season than between earnings seasons. Raw returns are higher between seasons, but this is driven by the early part of the 1950-2014 sample, and on a per-week basis there is no consistent difference, with stronger average returns during earnings season in recent subperiods. The results generally do not support shorting the market during earnings season.
How do you test whether stock returns differ between earnings seasons and non-earnings periods?
The test uses weekly S&P 500 closes since January 1950 (and VIX closes since January 1990), all through June 2014, and compares average returns during and between calendar-defined earnings seasons. Because earnings seasons are about three weeks shorter than the intervals between them, returns are also normalized per week, and then examined week by week (ES1-ES5 and BES1-BES8). Results are shown for since 1950 (257 observations), 1950-1989 (160), since 1990 (97) and since 2000 (57).
How does market volatility (VIX) behave during earnings season compared to the weeks after it ends?
The VIX tends to rise during most weeks of earnings season and then fall after earnings season is over, based on weekly VIX changes since 1990 and since 2000. This suggests expected volatility is generally higher during earnings season than between seasons, though the article does not find that this translates into reliably weaker S&P 500 returns.
What are the limitations of earnings season market timing strategies based on weekly returns?
Earnings season timing results carry two main cautions: recent subsamples are small relative to secular market trends and conditions, and week-by-week results are particularly vulnerable to data snooping bias (luck). Extreme-week results, such as weak second and last weeks of earnings season and weak first and sixth weeks between seasons, likely overstate reasonable out-of-sample expectations. The calendar-based definition of earnings season is also a simple approximation.