
Financial media often cite Bureau of Labor Statistics (BLS) productivity growth news releases as relevant to investment outlook. Does the quarter-to-quarter change in U.S. labor force productivity predict U.S. stock market behavior? Specifically, does a relatively weak (strong) change in productivity portend strong (weak) earnings and therefore an advance (decline) for stocks? Using annualized quarterly changes in non-farm labor productivity from BLS and end-of quarter S&P 500 Index levels during January 1950 through March 2019, we find that:
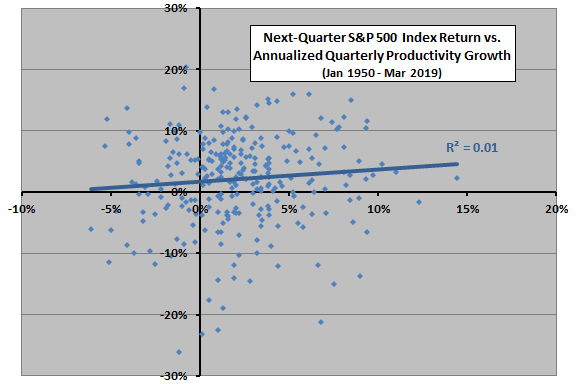
The following scatter plot relates next-quarter S&P 500 Index return to quarterly productivity growth over the full sample period. The Pearson correlation for the relationship is 0.09 and the R-squared statistic is 0.01, indicating that variations in productivity growth explain only 1% of the variation in next-quarter stock market return. Moreover, BLS announcements of productivity growth occur about a month after the end of the quarter reported.
For the first half of the sample (through 1984), the correlation is 0.02. For the second half of the sample, the correlation is 0.00.
Might there be a delayed effect of productivity growth on stock market return?
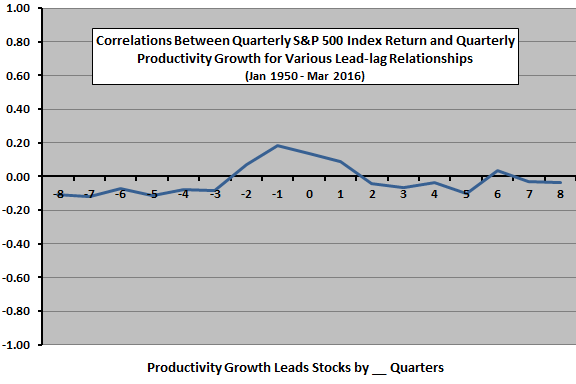
The next chart summarizes relationships between S&P 500 Index quarterly return and quarterly productivity growth for various lead-lag scenarios, ranging from stock market return leads productivity growth by eight quarters (-8) to productivity growth leads stock market return by eight quarters (8) for the full sample period. The strongest indication (correlation 0.18) is that stock market return leads productivity growth positively by one quarter. In other words, stock market returns are relatively strong (week) before relatively strong (weak) productivity growth. Productivity growth may weakly lead the stock market by one quarter, but the effect does not persist into subsequent quarters.
In case there are material non-linearities in the relationship, we look at stock market behavior by range of productivity growth.
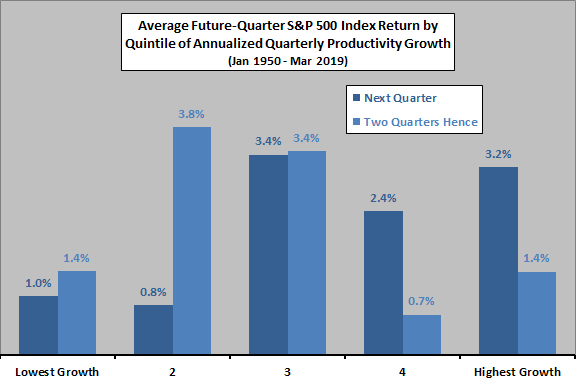
The next chart summarizes average S&P 500 Index return next quarter and two quarters hence by ranked fifth (quintile) of quarterly productivity growth over the entire sample period. There are 55 observations per quintile. Neither future return series exhibits systematic progression across productivity growth quintiles. There is some indication that weak productivity growth is worse than average and strong growth for next-quarter stock market return, but not for return the following quarter.
Do productivity growth series revisions affect interpretation of results?
BLS states: “Generally, a recent quarter of data is revised two or three times after its initial release. Historical revisions occur when the source data used in their construction are revised. Because many of these sources are revised independently, the productivity measures undergo frequent revision.”
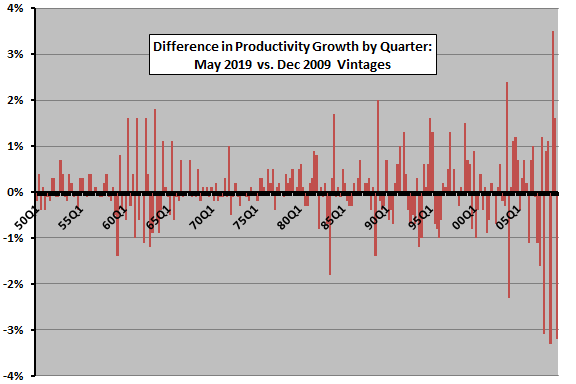
The final chart shows differences in quarterly productivity growth during January 1950 through September 2009 for two vintages of BLS historical data: December 2009 and May 2019. Revisions are extensive, with changes for 90% of quarters reported. Revisions at the end of the period during the financial crisis and initial recovery are pronounced.
In other words, the historical series likely deviates considerably from as-released data. Deviations may be especially large during times of financial market turmoil.
In summary, evidence from simple tests indicates that quarterly U.S. labor productivity growth as available from BLS is likely not useful for predicting U.S. stock market behavior, and perhaps that investors should not consider it due to large cumulative revisions.
Cautions regarding findings include:
- Productivity calculations employ other economic data series and do not capture the entire U.S. economy. Productivity growth may be therefore inherently less useful than economic series such as Gross Domestic Product and employment.
- Extensive revisions in productivity growth over time indicate the possibility of data snooping bias in current “historical” datasets.
- Differences between as-released productivity growth and some contemporaneous measure of expectations may evoke a short-term stock market reaction.
Frequently Asked Questions
What is labor productivity growth and why do investors watch it?
Labor productivity growth is the change in output per hour worked, reported quarterly for the U.S. non-farm sector by the Bureau of Labor Statistics (BLS). Financial media often cite it as relevant to the investment outlook, on the theory that weak (strong) productivity portends weak (strong) earnings and therefore stock declines (advances). The BLS announces each quarter's figure about a month after the quarter ends.
Does quarterly productivity growth predict stock market returns?
Quarterly U.S. labor productivity growth does not meaningfully predict next-quarter S&P 500 returns. Over January 1950 through March 2019, the correlation was 0.09 and the R-squared was 0.01, so productivity explains only about 1% of next-quarter return variation. The correlation was 0.02 through 1984 and 0.00 in the second half of the sample.
How do you test whether productivity growth leads or lags the stock market?
The test compares annualized quarterly BLS non-farm labor productivity growth with end-of-quarter S&P 500 Index returns over January 1950 through March 2019. Lead-lag correlations were run from -8 to +8 quarters, and returns were also grouped into quintiles (55 observations each) of productivity growth to check for non-linear effects. The strongest correlation (0.18) showed stock returns leading productivity growth by one quarter, and quintiles showed no systematic progression in future returns.
Is productivity growth a better stock market indicator than GDP or employment data?
The article suggests productivity growth is likely less useful than economic series such as Gross Domestic Product and employment, though it does not test them directly. Productivity calculations rely on other economic data series and do not capture the entire U.S. economy. The article also found stock returns tend to lead productivity growth by one quarter, rather than the reverse.
Why are BLS productivity growth numbers unreliable for investing?
BLS productivity growth data are revised extensively, so the historical series likely deviates considerably from as-released figures. Comparing the December 2009 and May 2019 data vintages for January 1950 through September 2009 showed revisions to 90% of quarters, especially during the financial crisis and initial recovery. This raises the possibility of data snooping bias in current historical datasets, and the article notes that gaps between as-released growth and contemporaneous expectations might still trigger short-term stock reactions.