
A reader asked: “Can you look into the predictions of Martin Armstrong? He may be one of the most interesting and out-of-the-box thinkers on the markets. He supposedly predicted the 1987 crash, the Japanese crash and the top of our real estate market to the day.”
Retrospective sampling of forecasts by the expert doing the forecasting (or an associate) is suspect. For promotional reasons or due to confirmation bias, experts may report successes and ignore (or deny the significance of) failures.
A scan of the recent writings of Martin Armstrong (sent from prison) posted at the “unofficial” MartinArmstrong.org generates a few examples of forecasts for the U.S. stock market, as proxied by the Dow Jones Industrial Average (DJIA). Martin Armstrong’s writings there are more storytelling (fitting selected past events to themes) than analysis. Themes focus strongly on cycles of business/economic/investing behavior.
The sample is too small for useful inference. The duration of the sample (less than two years) is small compared to forecast horizons, such that many forecasts are still pending. Also, conditionality/hedging of outlooks makes assessing forecast accuracy difficult. Specifically:
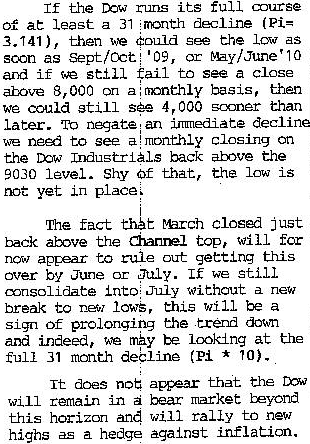
The following hedged outlook is from Martin Armstrong’s 12/18/08 commentary “We Are Alone”. The intuition that the U.S. stock market might fall sharply proved correct. However, the forecast that the drop would end “as early as April 2009 to June 2009” is substantially incorrect (one to three months late within a six-month forecast horizon). The destination of the drop for the DJIA is also substantially incorrect (4,000 versus an actual 6,440 on March 9, 2009).

The next very conditional outlook is from Martin Armstrong’s 5/15/09 commentary “Understanding the Real Economy”. There was no DJIA low in Sep/Oct 2009 (there could still be one in May/Jun 2010). Conditionalities make these forecasts difficult to assess and may provide the means to claim accuracy on many alternative market evolutions.
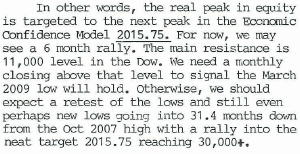
The next outlook is from Martin Armstrong’s 8/14/09 commentary “Will the Dow Reach 30,000 by 2015”. During 8/14/09-2/14/10, the DJIA rallied to January and then pulled modestly back, so one could judge the short-term part of the forecast essentially correct. The longer-term forecasts of a major low in mid-2011 and a major high in late 2015 are pending.
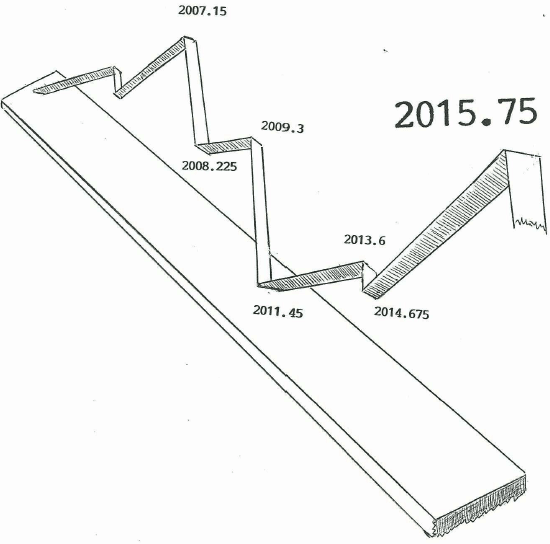
The following figure is also from Martin Armstrong’s 8/14/09 commentary (the front page). Partial iterations of the figure appear in earlier writings. The indication of a relative minimum in the DJIA during the first quarter of 2008 is incorrect. The indication of a relative maximum about a third of the way into 2009, followed by a steady decline is incorrect. As noted above, the indications of a major low in mid-2011 and a major high in late 2015 are pending.
The above evidence seems insufficient to support a belief that Martin Armstrong is an exceptional market forecaster.
A reader commented on 3/3/10:
“I don’t think you understand his model. I suggest you read “8.6 Year Review” [from 6/14/06 by Martin Armstrong] and “Economic Confidence Model” [from 6/14/06 with no author indicated]. The economic confidence model has a statistical significance into the billions to one odds. Pay attention especially to the highest and lowest points on the model, the minor points in between are less reliable and do not always mean a high or low, just a turn.”
Response:
Both citations are largely retrospective, with events sampled by Martin Armstrong or an associate. The cautions at the beginning of the brief review above about potential biases apply. The latter citation appears to include material added after the 6/14/06 publication date, as follows:
“2007.15 is projected by Martin to be a peak in commodity prices including Gold, however it could extend out into 2012 according to him. In general the model indicated that everything would inflate again after the 2002 low, with an emphasis on hard assets – commodities, real estate etc. but given that the dow jones 30 took the lead and made new highs into the 2007 cycle date while commodities and housing (actually the Schiller Housing index peaked on the Feb. 2007 Pi Cycle date, as did the Nikkei and the Financial Indices)peaked earlier that shows that capital had turned back to stocks (especially the blue chips) again. ” [sic]
Readers are free to investigate further or not.
Frequently Asked Questions
Who is Martin Armstrong and what is his market forecasting approach based on?
Martin Armstrong is a market forecaster whose writings, posted at the unofficial MartinArmstrong.org, focus strongly on cycles of business, economic and investing behavior. The article describes his commentary as more storytelling (fitting selected past events to themes) than analysis. His outlooks on the U.S. stock market are often framed with conditions and hedges.
Is Martin Armstrong an accurate stock market forecaster?
Martin Armstrong's stock market forecasts showed mixed accuracy in a small sample, and the evidence is insufficient to conclude he is an exceptional forecaster. His 12/18/08 call that the Dow Jones Industrial Average would fall sharply proved directionally right, but the timing and the 4,000 destination (versus an actual 6,440 low on March 9, 2009) were substantially incorrect. The short-term part of his 8/14/09 forecast was essentially correct through 2/14/10, while his longer-term calls for a mid-2011 low and late-2015 high were still pending.
How can you evaluate the accuracy of Martin Armstrong's market predictions?
Martin Armstrong's predictions were assessed by scanning his recent writings for forecasts of the Dow Jones Industrial Average and comparing each with subsequent actual market outcomes. Examples came from commentaries dated 12/18/08, 5/15/09 and 8/14/09, including a figure of projected turning points. This approach is limited because the sample covers less than two years and many forecasts were still pending.
Are claims of predicting past crashes the same as reliable forecasting skill?
No. Claims that Martin Armstrong predicted past events, such as the 1987 crash, the Japanese crash and the top of the U.S. real estate market, are retrospective samples reported by the forecaster or an associate, which differs from verified forecasting skill. The article warns that promotional motives or confirmation bias may lead experts to report successes and ignore or downplay failures. It also found his Economic Confidence Model citations largely retrospective, with one appearing to include material added after its 6/14/06 publication date.
Why is it hard to judge whether Martin Armstrong's forecasts were right or wrong?
Martin Armstrong's forecasts are hard to judge because the sample is small, covers less than two years, and is short relative to forecast horizons, leaving many forecasts pending. His outlooks are also conditional and hedged, such as the 5/15/09 call for a possible DJIA low in Sep/Oct 2009 that did not occur but could still occur in May/Jun 2010. The article says these conditionalities may allow accuracy to be claimed for many alternative market outcomes.