
How do stock index volatility and variance futures contracts compare with stock index put options as hedges against market crashes? In their August 2010 paper entitled “Using Volatility Instruments as Extreme Downside Hedges”, Bernard Lee and Yueh-Neng Lin investigate the effectiveness of stock index volatility and variance futures contracts as extreme downside hedges and compare this effectiveness to that of out-of-the-money index put options. Specifically, they compare the outcomes of hedging a long Standard & Poor’s Depository Receipts (SPY) position via 1-month and 3-month rolling positions in S&P 500 Volatility Index (VIX) futures contracts, S&P 500 3-month Variance Futures (VT) contracts and 10% out-of-the-money (OTM) S&P 500 Index put options with reasonable hedge trading frictions. Using price data for SPY, VIX and VT futures contracts and index put options spanning 6/10/04-10/14/09 for 1-month rolling hedges and 7/19/04-9/9/09 for 3-month rolling hedges, they find that:
- Rolling VIX and VT futures contracts are more cost-effective extreme downside hedges than rolling out-of-the-money S&P 500 Index put options.
- VIX futures are the most cost-effective choice for hedging extreme downside risk. And, rolling 3-month VIX futures contracts outperform rolling 1-month VIX futures contracts, indicating that the increased trading frictions of more frequent hedge adjustments outweigh incremental hedging value.
- Based on the relatively high liquidity of 3-month VIX futures contracts, real-life traders appear to have developed the correct market intuition.
The following chart, taken from the paper, compares cumulative values (marked to market – MTM) over the test period of 100 shares of SPY that are:
- Unhedged (ETF).
- Completely hedged by 1-month rolling S&P 500 Index put options (SPXPUT).
- Completely hedged by 1-month rolling VIX futures contracts.
- Completely hedged by 3-month rolling VIX futures contracts.
- Completely hedged by 1-month rolling VT futures contracts.
The chart shows that hedging with 3-month rolling VIX futures contracts (1-month rolling index put options) is most (least) cost-effective.
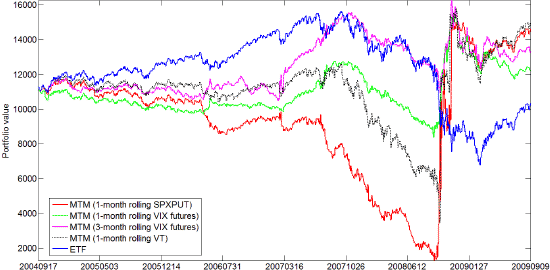
In summary, evidence indicates that 3-month rolling VIX futures contracts may be the preferred way for investors to hedge stock market positions against crashes.
Frequently Asked Questions
What is an extreme downside hedge in investing?
An extreme downside hedge is a position designed to offset large losses in a stock portfolio during market crashes. Lee and Lin examine volatility futures, variance futures and out-of-the-money index puts as such hedges for a long SPY position. Each is evaluated on how cost-effectively it protects against severe declines, after trading frictions.
Are VIX futures better than put options for hedging a stock market crash?
VIX futures were more cost-effective than 10% out-of-the-money S&P 500 put options as extreme downside hedges in the Lee and Lin study. Rolling VIX and VT (variance) futures both beat rolling OTM puts, and VIX futures were the most cost-effective choice overall. The test periods ran 6/10/04-10/14/09 for 1-month rolls and 7/19/04-9/9/09 for 3-month rolls.
How do you test a crash hedge using rolling VIX futures and index puts?
Lee and Lin compared the marked-to-market cumulative value of 100 shares of SPY that were unhedged or completely hedged with 1-month rolling index puts, 1-month or 3-month rolling VIX futures, or rolling VT variance futures. The puts were 10% out-of-the-money S&P 500 Index options, and the hedges included reasonable trading frictions. Price data for SPY, VIX and VT futures, and index puts covered mid-2004 to late 2009.
Is it better to roll 3-month or 1-month VIX futures when hedging a stock portfolio?
Rolling 3-month VIX futures outperformed rolling 1-month VIX futures as a crash hedge in the Lee and Lin study. The added trading frictions of more frequent hedge adjustments outweighed the incremental hedging value of the 1-month roll. The authors also note that 3-month VIX futures are relatively liquid, consistent with real-life trader practice.
What are the limitations of using volatility futures to hedge against market crashes?
The Lee and Lin findings rest on a single test period of roughly 2004-2009, and results include only the hedge trading frictions the authors assumed to be reasonable. The comparison covers specific instruments: 10% out-of-the-money S&P 500 puts, VIX futures and 3-month variance futures, hedging a long SPY position. Trading frictions also matter, since more frequent rolling of 1-month hedges reduced cost-effectiveness relative to 3-month rolls.