
Are factor models universal, or does each group of related stocks have a unique set of factors for predicting differences in future returns? In their September 2007 paper entitled “How Common Are Common Return Factors Across NYSE/AMEX and Nasdaq?”, Amit Goyal, Christophe Perignon and Christophe Villa propose a general procedure to identify pervasive risk factors and apply the methodology to identify similarities and differences between the return structures of the specialist-controlled NYSE/AMEX and the computer-driven Nasdaq. Using monthly return data for large samples of NYSE/AMEX and Nasdaq stocks over the period 1978-2002 (25 years), divided into five 60-month subperiods, they find that:
- While there are three important pervasive factors for both NYSE and Nasdaq stocks, no more than two are common to both groups. In other words, there is a substantial difference between the return structures of stocks on the two exchanges.
- There are at most three pervasive factors for both groups across a long time horizon, suggesting that two-factor or three-factor models are adequate to describe the cross-section of stock returns for any given group of stocks.
- With respect to widely used factors:
- The market factor (beta), the principal factor of factor models, typically has the highest correlation with the above common pervasive factors. However, the importance of the market factor in explaining variation of returns among stocks has decreased over time.
- The importance of the size effect seems to have decreased over time.
- The importance of the value premium has increased over time (although not monotonically).
- The addition of a momentum factor only marginally improves the explanatory power of the other widely used factors.
The following table, taken from the paper, summarizes top-level differences in excess (relative to the one-month Treasury bill yield) monthly return statistics for stocks traded on the NYSE/AMEX and Nasdaq over five 60-month subperiods during 1978-2002. NYSE/AMEX has more stocks (N) in early subperiods, while Nasdaq has more in later subperiods. Nasdaq stocks tend to be more volatile than NYSE/AMEX stocks, and this difference has increased over time. Nasdaq stocks also have higher skewness and kurtosis than NYSE/AMEX stocks. These differences support the conclusion from general factor analysis that there are significant differences between the cross-sectional structures of NYSE/AMEX and Nasdaq returns.
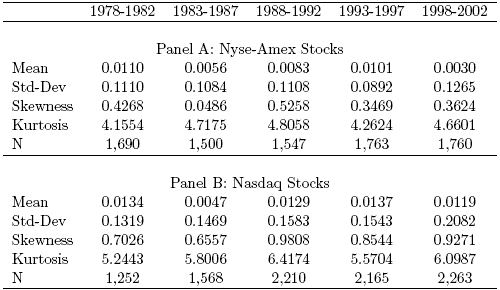
In summary, while dominant factors may be common, different groups of stocks require different factor models to explain the variation in returns among individual stocks within them.
Frequently Asked Questions
What is a pervasive risk factor in a stock return factor model?
A pervasive risk factor is a common source of variation that drives returns across many stocks in a group, and factor models use such factors to explain differences in stock returns. Goyal, Perignon and Villa propose a general procedure to identify these factors, and the market factor (beta) typically has the highest correlation with the pervasive factors they find.
Do NYSE/AMEX and Nasdaq stocks share the same return factors?
NYSE/AMEX and Nasdaq stocks do not share the same return factors: each group has up to three pervasive factors, but no more than two are common to both. Based on monthly data for 1978-2002, this indicates a substantial difference between the return structures of the two exchanges. Different groups of stocks therefore appear to require different factor models.
How do researchers test whether return factors are common across different groups of stocks?
Goyal, Perignon and Villa apply a general procedure for identifying pervasive risk factors to separate samples of NYSE/AMEX and Nasdaq stocks, then compare the factors found for each group. They use monthly returns from 1978-2002, divided into five 60-month subperiods, and compare the pervasive factors with widely used factors such as market, size, value and momentum. Summary statistics such as volatility, skewness and kurtosis of excess returns over the one-month Treasury bill yield provide supporting evidence.
How do the market, size, value and momentum factors compare in explaining stock returns over time?
In the 1978-2002 study, the market factor (beta) typically has the highest correlation with the common pervasive factors, but its importance in explaining return variation among stocks has decreased over time. The size effect also seems to have weakened, while the value premium has grown in importance, although not monotonically. Adding a momentum factor only marginally improves the explanatory power of the other widely used factors.
What are the limitations of using a single factor model for all stocks?
A single factor model may not fit all stocks because NYSE/AMEX and Nasdaq stocks share at most two of three pervasive factors, so a model built for one group may miss factors important to the other. Nasdaq stocks are also more volatile, with higher skewness and kurtosis, and this volatility gap has grown over time. The findings cover 1978-2002 and two exchanges, and they suggest two-factor or three-factor models are adequate for any given group of stocks.