
How can investors protect portfolios from crashes across asset classes? In the November 2014 version of his paper entitled “Tail Risk Protection in Asset Management”, Cristian Homescu describes tail (crash) risk metrics and summarizes the body of recent research on the effectiveness and costs of alternative tail risk protection strategies. The purpose of these strategies is to mitigate or eliminate investment losses during rare events adverse to portfolio holdings. These strategies typically bear material costs. He focuses on some strategies that may be profitable and hence useful for more than crash protection. Based on recent tail risk management research and some examples, he concludes that:
- Widely used measures of (left) tail risk are:
- Downside volatility – the standard deviation of negative returns.
- Value-at-risk – the probability over a given interval of a loss greater than some threshold.
- Expected shortfall or conditional value-at-risk – the expected total for events exceeding the VaR threshold.
- Value of financial derivatives that hedge negative returns.
- Expected tail loss – expected return during the worst events over a specified interval.
- Tail risk protection must work (meaningfully offset losses and not quickly revert) when asset allocation, rebalancing and momentum strategies are most vulnerable (when the market is least liquid).
- Tail risk strategies fall into four categories:
- Diversification – not all holdings crash at the same time. However, diversification that is evident when markets are calm may diminish during crises.
- All-weather (such as risk parity) – markets have two or several predictable states (regimes), with each state having a distinct return distribution and inter-asset correlations. However, regime prediction is messy, making the portfolio suboptimal most of the time.
- Hedging – sacrifice a portion of expected returns to fund positions (portfolio insurance) that protect the balance of the portfolio during tail events. Portfolio insurance may be static or dynamically change based on market state. Cost effectiveness is a main concern. Complexity is a concern for dynamic hedging.
- Alternative alpha – elevate allocations to alternative investments (global macro, Commodity Trading Advisor and volatility-based) expected to outperform during volatile markets. However, such alternatives may be a drag on the overall portfolio much of the time.
- Hedging approaches may involve one or more of (see the table below):
- Variance swaps
- Tail risk protection indexes
- Financial options
- Credit instruments
- Inflation floor agreements
- Managed futures indexes
- Sovereign risk commodity hedges
- Sovereign risk rates hedges
- Swaps on indexes
- A target volatility strategy
- A tail risk parity strategy
- Exploitation of implied and/or realized volatility
- Dynamic hedging strategies (such as a multi-regime volatility futures strategy) may boost long-term portfolio returns both by generating positive returns and by making funds available during hedge liquidation to exploit low prices for hedged assets.
The following table, extracted from the paper, summarizes instruments available to hedge tail risks for various asset classes, along with rough relative hedge costs and liquidities.
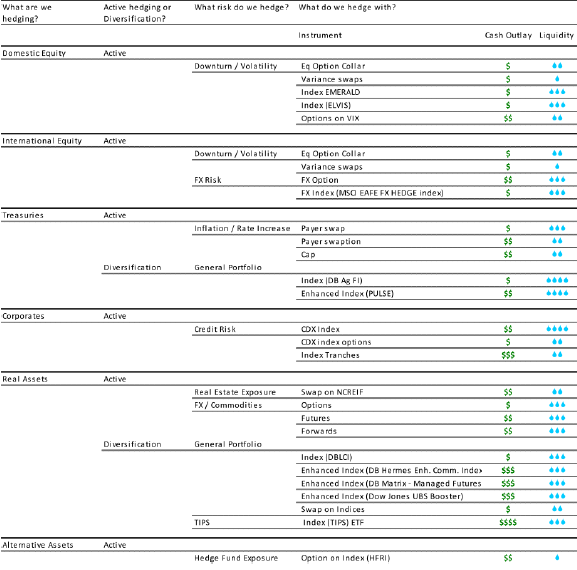
In summary, evidence suggests that tail risk management improves long-term portfolio performance even for well-diversified investors.
Cautions regarding conclusions include:
- By definition, samples of rare events are always small. Optimizing complex tail protection strategies with many assumptions/parameters using small samples can generate extreme data snooping bias.
- Moreover, comparing different strategies for avoiding a given type of crash incorporates higher-level snooping bias.
- As noted in the study, some hedging instruments may involve ancillary risk of hedge counterparty failure.
Frequently Asked Questions
What is tail risk protection in investing?
Tail risk protection refers to strategies that mitigate or eliminate investment losses during rare events adverse to portfolio holdings, such as market crashes. Common measures of left tail risk include downside volatility, value-at-risk, expected shortfall (conditional value-at-risk), and expected tail loss. These strategies typically bear material costs.
Does tail risk management improve long-term portfolio performance?
Tail risk management appears to improve long-term portfolio performance, even for well-diversified investors, according to Cristian Homescu's November 2014 review of recent research. Dynamic hedging strategies, such as a multi-regime volatility futures strategy, may boost returns by generating positive returns and freeing funds to buy hedged assets at low prices. The evidence is subject to small-sample and data snooping caveats.
How do investors hedge against market crashes?
Investors hedge against market crashes by sacrificing a portion of expected returns to fund portfolio insurance that protects the rest of the portfolio during tail events. Instruments include financial options, variance swaps, tail risk protection indexes, credit instruments, managed futures indexes, swaps on indexes, target volatility strategies, and tail risk parity strategies. Portfolio insurance may be static or may change dynamically with market state.
How do diversification, all-weather portfolios, hedging, and alternative alpha compare for crash protection?
The four tail risk strategy categories each have a distinct trade-off. Diversification may fail in crises when correlations rise, all-weather approaches such as risk parity depend on messy regime prediction and are suboptimal most of the time, hedging is costly and dynamic versions are complex, and alternative alpha (global macro, Commodity Trading Advisors, volatility-based) may drag on the portfolio much of the time.
What are the risks and limitations of tail risk protection strategies?
Tail risk protection strategies typically carry material costs, and cost effectiveness is a main concern for hedging. Because samples of rare events are small, optimizing complex strategies with many parameters can produce extreme data snooping bias, and comparing strategies adds higher-level snooping bias. Some hedging instruments also carry the ancillary risk of hedge counterparty failure.