
Do stocks of firms that initiate buybacks (open market stock repurchases) tend to appreciate due to elevated takeover risk? In the October 2013 draft of their paper entitled “The Timing and Source of Long-run Returns Following Repurchases”, Leonce Bargeron, Alice Bonaime and Shawn Thomas investigate the timing and source of the abnormal return associated with stock repurchases. They define abnormal return as three-factor (market, size, book-to-market) alpha from equally weighted portfolios of stocks associated with repurchasing activity. They focus on subsequent repurchase and takeover announcements as potential sources of long-run outperformance after repurchases. Using firm characteristics and monthly returns for stocks involved in 18,293 open market repurchase authorization announcements, with focus on 3,089 that have associated repurchase completion announcements, during January 1980 through September 2010, they find that:
- For both the subsample of authorizations with completions and the overall sample, positive average gross alpha after repurchase announcements derives entirely from subsequent repurchase authorizations and takeover attempts (see the chart below).
- For example, from the overall sample (the subsample of matching authorizations and completions):
- When there are no subsequent authorizations, average gross monthly alpha is 0.22% (0.27%) over the 12 months after authorization.
- When there are subsequent authorizations, average gross monthly alpha is 0.29% (0.55%) over the 12 months after initial authorization.
- When there are either subsequent authorizations or takeover attempts, average gross monthly alpha is 0.63% (0.61%) over the 12 months after initial authorization.
- More specifically, average long-run outperformance after repurchase authorizations derives from aggregation of price jumps around subsequent repurchase announcements and takeover announcements.
- Controlling for a takeover risk factor eliminates outperformance of stocks involved in repurchase activity. In other words, the contribution of subsequent takeovers dominates the contribution of repeat repurchases in driving returns for past repurchasers.
- Findings are robust across subsamples and variations in methodology.
The following chart, taken from the paper, compares cumulative three-factor alphas for four subsamples of the overall set of 18,293 repurchase authorization announcements:
- Stocks with no subsequent repurchase authorization announcements
- Stocks with no subsequent repurchase authorization or takeover attempt announcements
- Stocks with subsequent repurchase authorization announcements
- Stocks with subsequent repurchase authorization or takeover attempt announcements
Results indicate that subsequent repurchase or takeover announcements are essential to stock outperformance, and suggest that the effect of takeover announcements dominates.
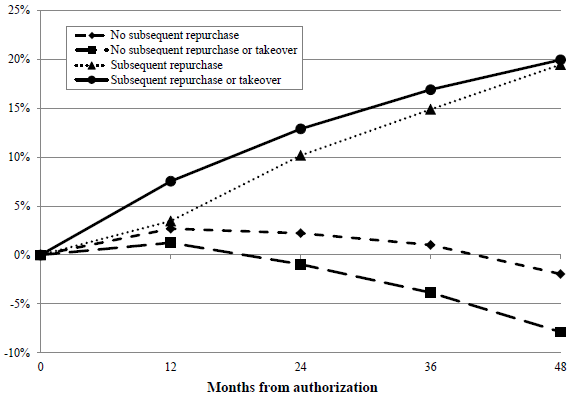
In summary, evidence indicates that stock repurchase announcements are noisy indicators of subsequent repurchases/takeovers and that price jumps during these subsequent events drive the future average gross outperformance associated with the initial repurchase announcements.
Cautions regarding findings include:
- Alpha calculations are gross, not net. Including costs of buying and selling based on repurchase signals would lower these alphas.
- As noted by the authors, the study is substantially retrospective and does not enable any exploitable refinement of a stock buyback investment strategy.
Frequently Asked Questions
What is an open market stock repurchase (buyback) authorization?
An open market stock repurchase authorization is a firm's announcement that it may buy back its own shares on the open market. In the study of 18,293 such authorization announcements from January 1980 through September 2010, only 3,089 had associated repurchase completion announcements, so an authorization does not guarantee completed buybacks.
Do stocks that announce buybacks outperform in the long run?
Stocks that announce buybacks show positive long-run three-factor alpha only when followed by subsequent repurchase authorizations or takeover attempts. For the overall sample, average gross monthly alpha over the 12 months after authorization was 0.22% with no subsequent authorizations, 0.29% with subsequent authorizations, and 0.63% with either subsequent authorizations or takeover attempts. Takeover announcements dominate the contribution to outperformance.
How is abnormal return measured after stock buyback announcements?
Abnormal return after buyback announcements is measured as three-factor (market, size, book-to-market) alpha from equally weighted portfolios of stocks associated with repurchasing activity. The study used monthly returns and firm characteristics for 18,293 open market repurchase authorizations from January 1980 through September 2010. It compared cumulative alphas across subsamples with and without subsequent repurchase authorizations or takeover attempts.
Are post-buyback stock returns driven by repeat buybacks or by takeover risk?
Post-buyback returns are driven mainly by takeover risk rather than repeat buybacks. Outperformance comes from the aggregation of price jumps around subsequent repurchase and takeover announcements, and controlling for a takeover risk factor eliminates the outperformance of stocks involved in repurchase activity. Subsequent takeovers therefore contribute more than repeat repurchases.
What are the limitations of using buyback announcements as a trading signal?
Buyback announcements are noisy indicators of subsequent repurchases or takeovers, and the study's alphas are gross, not net of buying and selling costs, which would lower them. The authors note the study is substantially retrospective and does not enable any exploitable refinement of a stock buyback investment strategy.