
In an August 2004 article entitled “Time is Right for These 7 Biotechs” (apparently no longer available on MSN Money), Jim Jubak states: “…in most years, biotechs decline in the spring as investors anticipate a summer hiatus in the conferences where new clinical results are announced. They rally in the fall as the conference schedule and the volume of news increases.” Does empirical data support belief in these observations? To check, we examine the behavior of the AMEX Biotechnology Index (BTK) across the calendar year. Using monthly closing levels for BTK from its inception in January 1995 through August 2012 (over 17 years), and contemporaneous monthly returns for the S&P 500 Index for detrending, we find that:
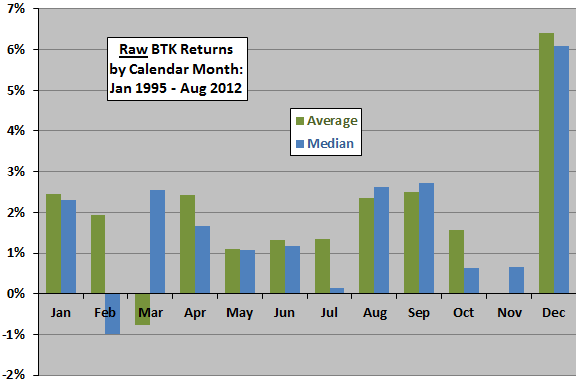
The following chart shows the raw average and median returns by calendar month for BTK over the sample period. The average monthly return for BTK for all months in the sample is 1.9%, with standard deviation 10.4%. A large difference between the average and median indicates that one or a few very extreme months drive the average. For example, 11 of 17 Februaries in the sample have negative returns, but an extremely large positive return in February 2000 makes the average return positive. Based on raw returns:
- December stands out as exceptionally strong.
- January, April, August and September are above average.
- Other months are relatively weak and/or volatile.
Is biotech seasonality distinct from that of the overall stock market?
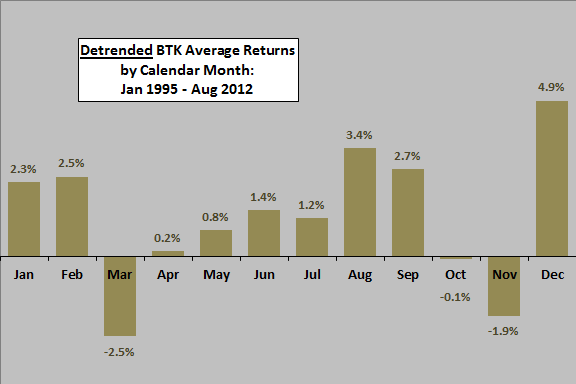
The next chart shows the detrended average return by calendar month for BTK over the sample period, with detrending accomplished by subtracting the return for the S&P 500 Index from the return for BTK each month. The average abnormal monthly return for BTK for all months in the sample is about 1.2%. Based on detrended returns:
- December still stands out as exceptionally strong.
- Biotechs tend to outperform during January, February, August and September.
- Biotechs tend to underperform during March and November.
Do biotechs reliably lead or lag the broad U.S. stock market?
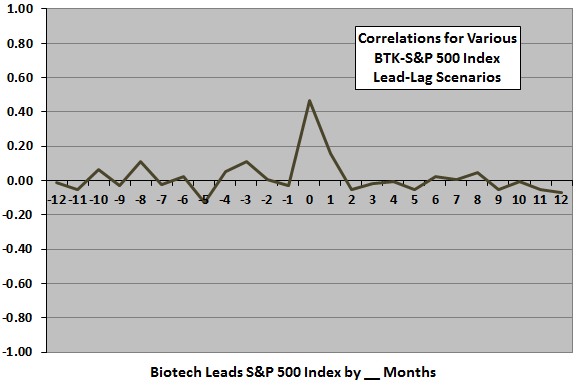
The final chart summarizes Pearson correlations between monthly S&P 500 Index returns and BTK monthly returns for various lead-lag scenarios, ranging from the S&P 500 Index leads BTK by 12 months (-12) to BTK leads the S&P 500 Index by 12 months (12). The peak at “0” is the coincident relationship. Results suggest there may be a weak tendency for biotechs to lead the overall stock market by a month.
In summary, evidence from a modest available sample suggests that biotech stocks tend to be strong in late summer and December.
One caution regarding findings is that sample size is very small for a calendar month analysis, such that one or two additional observations could materially alter conclusions.
Frequently Asked Questions
What is the AMEX Biotechnology Index (BTK) and what does biotech seasonality mean?
The AMEX Biotechnology Index (BTK) is a stock index that tracks biotechnology companies, launched in January 1995. Biotech seasonality refers to recurring calendar-month patterns in biotech stock returns, such as the belief that biotechs weaken in spring and rally in the fall as clinical conference news increases.
Do biotech stocks have reliable seasonal patterns by calendar month?
Biotech stocks, as measured by the AMEX Biotechnology Index (BTK), show some seasonal tendencies, with December standing out as exceptionally strong in both raw and detrended returns from January 1995 through August 2012. Biotechs also tend to outperform the S&P 500 in January, February, August and September, and underperform in March and November. The evidence comes from a modest sample, so the patterns are suggestive rather than reliable.
How do you detrend biotech returns to test for seasonality against the S&P 500?
Detrending BTK returns is done by subtracting the S&P 500 Index return from the BTK return each month, then averaging the resulting abnormal returns by calendar month. The analysis used monthly closing levels from January 1995 through August 2012, and the average abnormal monthly return for BTK was about 1.2%. Lead-lag behavior was tested separately with Pearson correlations between monthly S&P 500 and BTK returns at leads and lags from -12 to +12 months.
Do biotech stocks lead the broad stock market, or does the S&P 500 lead biotechs?
Biotech stocks, as measured by BTK, show only a weak tendency to lead the S&P 500 by one month, based on Pearson correlations across lead-lag scenarios from -12 to +12 months. The strongest relationship is the coincident one (lag 0), meaning biotech and S&P 500 returns mainly move together in the same month.
What are the limitations of using calendar-month seasonality to trade biotech stocks?
Calendar-month seasonality in biotech stocks rests on a very small sample, so one or two additional observations could materially alter the conclusions. The BTK data cover only about 17 years (January 1995 to August 2012), and extreme months can distort averages. For example, 11 of 17 Februaries were negative, but one very large positive return in February 2000 made the February average positive.