
Does the U.S. stock market exhibit predictable return and volatility patterns during the trading day? To investigate, we analyze one-minute prices for SPDR S&P 500 (SPY) over two recent years. Specifically, we calculate average cumulative return, average returns for 15-minute intervals and average standard deviation of one-minute returns during 15-minute intervals over the trading day during each of 2007 (bullish year) and 2008 (bearish year). Using a sample of SPY one-minute prices for 9:30-16:15 spanning 2007-2008 (over 203,000 observations), we find that:
There are two data quality issues:
- The daily opening and closing prices in the sample often deviate slightly from those for (unadjusted) SPY at Yahoo!Finance. Tick selection may be the reason, and the mismatches are probably not important.
- There are some prices missing in the sample. We exclude from averages any returns associated with these missing data. There are enough prices missing for 7/22/08 that we exclude the entire day. For 12/17/08-12/31/08, there are no prices after 16:00.
We exclude from consideration shortened trading days (7/3/07, 11/23/07, 12/24/07, 7/3/08, 11/28/08 and 12/24/08), since early closes would likely shift any patterns.
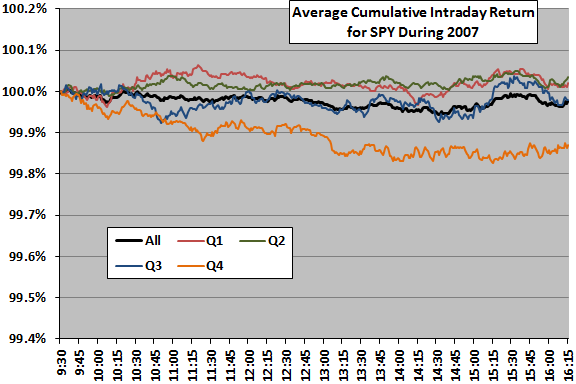
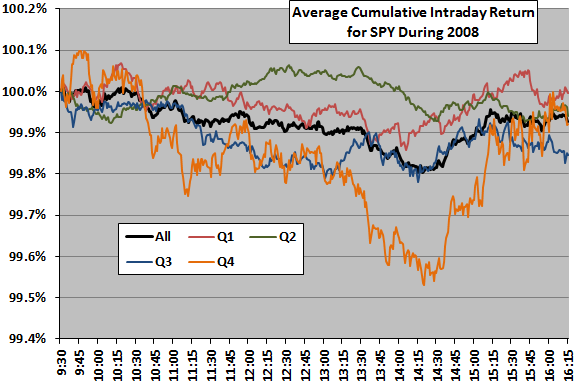
The following two charts show the average SPY intraday cumulative returns based on one-minute prices, overall and by quarter, for 2007 (upper chart) and 2008 (lower chart). The charts use the same scale to facilitate comparison, emphasizing that intraday behavior is much more volatile during 2008 than 2007. Notable points are:
- There may be a tendency for the stock market to decline in early afternoon and subsequently rebound.
- However, differences among quarters undermine belief in a reliable pattern.
- Average returns associated with any patterns, even those for volatile 2008, are likely too small to exploit on a net basis as a standalone strategy. When trading frequently for other reasons, attending to intraday tendencies may be advantageous (for example, scheduling buys for mid-afternoon).
For another perspective, we look at consecutive 15-minute returns.
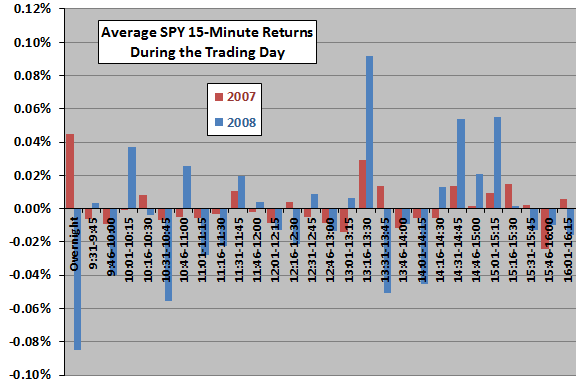
The next chart compares average overnight returns and average intraday 15-minute returns for SPY during 2007 and 2008. There is no compelling pattern, but there is perhaps some indication of alternating strength and weakness in the afternoon.
Might there be a stronger case for a pattern in volatility during the day based on lower market liquidity at the open and the close?
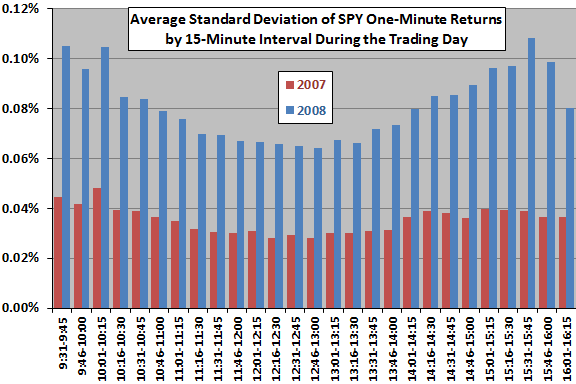
The final chart compares average standard deviation of SPY one-minute returns by 15-minute intraday intervals for 2007 and 2008. While 2008 is much more volatile than 2007, both years exhibit relatively high volatility near the open and close and low volatility in the middle of the day. This pattern suggests that frequent traders may want to schedule option buys (sells) during the middle (beginning and end) of the trading day when the short-term realized volatility may affect implied volatility and therefore option prices. It also suggests that more aggressive limit orders may be appropriate at the beginning and end of the day.
In summary, evidence from two recent years suggests a slight tendency for the U.S. stock market to be a little weak during mid-afternoon and some tendency for volatility to be lower during the middle of the day than at the beginning or end.
Cautions regarding findings include:
- As noted, intraday return patterns are not very reliable, and average return variations are very small compared to probable costs of exploitation.
- Patterns for other years may be different.
Frequently Asked Questions
What is intraday stock market seasonality and how does it apply to the S&P 500 ETF (SPY)?
Intraday stock market seasonality refers to recurring patterns in returns or volatility at particular times of the trading day. The article examines this for SPDR S&P 500 (SPY) using one-minute prices from 9:30 to 16:15 across 2007 and 2008, looking at average cumulative returns, 15-minute interval returns, and the standard deviation of one-minute returns.
Does the stock market show a reliable pattern of returns during the trading day?
The stock market does not show a reliable intraday return pattern in SPY data for 2007-2008, though there is a slight tendency toward weakness in mid-afternoon and a possible rebound afterward. Differences among quarters undermine belief in a dependable pattern, and consecutive 15-minute returns showed no compelling pattern, only a possible alternation of strength and weakness in the afternoon.
How do you measure intraday volatility patterns in an ETF like SPY?
Intraday volatility in SPY was measured by calculating the average standard deviation of one-minute returns within each 15-minute interval of the trading day, separately for 2007 (a bullish year) and 2008 (a bearish year). The sample covered over 203,000 one-minute observations, excluded missing prices, the day 7/22/08, and shortened trading days such as early closes.
Is stock market volatility higher at the open and close than in the middle of the day?
Stock market volatility in SPY was relatively high near the open and close and low in the middle of the day in both 2007 and 2008, even though 2008 was much more volatile overall. The article suggests this may be linked to lower liquidity at the open and close, and that frequent traders might schedule option buys for midday and option sells or more aggressive limit orders near the beginning and end of the day.
Can traders profit from intraday return patterns in the stock market?
Traders are unlikely to profit from SPY intraday return patterns as a standalone strategy, because the average return variations are very small compared to probable costs of exploitation. The patterns are also not very reliable across quarters, and the findings come from only two years (2007-2008), so other years may differ. The patterns may still help those already trading frequently, for example by scheduling buys for mid-afternoon.