
Do hedge funds demonstrate the exploitability of real-time economic data? In their June 2017 paper entitled “Can Hedge Funds Time the Market?”, Michael Brandt, Federico Nucera and Giorgio Valente evaluate whether all or some equity hedge funds vary equity market exposure in response to real-time economic data, and (if so) whether doing so improves their performance. Their proxy for real-time economic data available to a sophisticated investor is the 20-day moving average of an economic growth index derived from principal component analysis of purely as-released industrial output, employment and economic sentiment. They relate this data to hedge fund performance by:
- Applying a linear regression to measure the sensitivity (economic data beta) of each hedge fund to monthly changes in economic data.
- Sorting funds into tenths (deciles) based on economic data beta and calculating average next-month equally weighted risk-adjusted performance (7-factor alpha) by decile. The seven monthly factors used for risk adjustment are: equity market excess return; equity size factor; change in 10-year U.S. Treasury note (T-note) yield; change in yield spread between BAA bonds and T-notes; and trend following factor for bonds, currencies and commodities.
Using sample of 2,224 dead and alive equity hedge funds having at least 36 months of net-of-fee returns and average assets under management of at least $10 million, and contemporaneous daily values of the economic growth index, during January 1994 through December 2014, they find that:
- About 17% (9%) percent of equity hedge funds exhibit statistically significant positive (negative) economic data betas.
- Based on equal fund weighting, the top decile of economic data beta outperforms the bottom decile by 5.5% annualized average 7-factor alpha over the sample period.
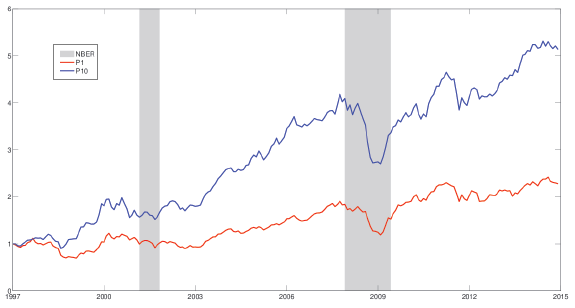
- By the end of the sample period, a $1 investment at the beginning of 1997 in the top decile generates about five times the wealth of a $1 investment in the bottom decile, though the top decile has a deeper loss during the 2008-2009 financial crisis (see the chart below).
The following chart, taken from the paper, compares net cumulative returns from investing $1 at the end of 1997 in the equally weighted decile of equity hedge funds with the lowest (red line) and highest (blue line) economic data betas through the end of the sample period. Gray shading indicates (retrospective) NBER economic contractions. The highest decile usually outperforms but has a deeper drawdown during the 2008-2009 economic contraction.
In summary, evidence indicates that some equity hedge funds achieve elevated performance by exploiting real-time economic data.
Cautions regarding findings include:
- The study does not address the nature of portfolio changes that funds with high economic data beta make in response to changes in economic data.
- There may be snooping bias, inherited from prior research or introduced via the moving average parameter, in the construction of the economic growth index.
- Identification of which hedge funds have high economic data beta is beyond the capability of many investors. Moreover, most investors cannot hold a basket of hedge funds with high economic data beta to capture its effect reliably, and changing funds in response to changing betas may not be feasible in a timely way.
Frequently Asked Questions
What is economic data beta for a hedge fund?
Economic data beta is the sensitivity of a hedge fund's returns to changes in real-time economic data, estimated with a linear regression on monthly changes in an economic growth index. In the study, the index is a 20-day moving average derived from principal component analysis of as-released industrial output, employment and economic sentiment. A high beta suggests the fund varies its equity market exposure as economic data changes.
Do hedge funds with high economic data betas outperform those with low betas?
Yes, high economic data beta equity hedge funds outperformed low beta funds in the study, with the top decile beating the bottom decile by 5.5% annualized average 7-factor alpha from 1994 through 2014. A $1 investment at the beginning of 1997 in the top decile produced about five times the wealth of the bottom decile by the end of the sample. About 17% of funds had significantly positive betas and 9% significantly negative betas.
How is hedge fund performance tested against real-time economic data?
Researchers regressed each hedge fund's returns on monthly changes in a real-time economic growth index to estimate its economic data beta, then sorted funds into deciles by beta. They calculated average next-month equally weighted 7-factor alpha for each decile. The sample covered 2,224 live and dead equity hedge funds with at least 36 months of net-of-fee returns and at least $10 million in average assets, from January 1994 through December 2014.
How does 7-factor alpha differ from a hedge fund's raw returns?
Seven-factor alpha is risk-adjusted performance that removes returns explained by seven monthly factors, while raw returns do not make that adjustment. The factors are equity market excess return, equity size, change in the 10-year T-note yield, change in the BAA-to-T-note yield spread, and trend-following factors for bonds, currencies and commodities. The study used this alpha to compare economic data beta deciles, finding a 5.5% annualized spread, though the top decile also suffered a deeper loss in the 2008-2009 financial crisis.
What are the limitations of using economic data beta to select hedge funds?
Economic data beta has practical and methodological limitations: the study does not explain what portfolio changes high beta funds make in response to economic data, and the economic growth index may suffer from snooping bias via prior research or the moving average parameter. Identifying high beta funds is beyond the capability of many investors, and most cannot reliably hold a basket of them or switch funds quickly as betas change. The highest beta decile also had a deeper drawdown during the 2008-2009 contraction.