
Navellier & Associates, Inc. offers one Navellier-branded mutual fund, Navellier Fundamental A (NFMAX), “designed to achieve the highest possible returns while minimizing risk.” Selection criteria for fund holdings, re-measured quarterly, “include earnings growth, profit margins, reasonable price/earnings ratios based on expected future earnings, and various other fundamental criteria.” Using NFMAX weekly adjusted closing prices from inception in May 2005 through July 2009 and corresponding weekly levels of the Russell 3000 index as a self-selected benchmark, we find that:
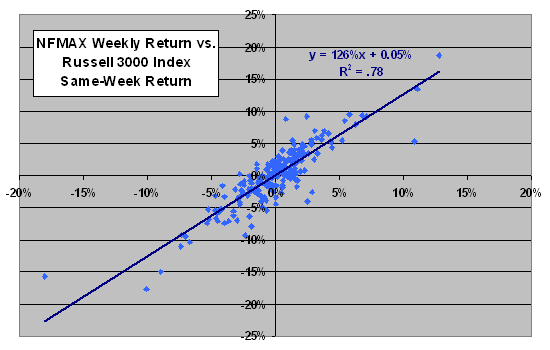
The following scatter plot relates weekly NFMAX return to same-week Russell 3000 index return over the entire sample period. The the R-squared statistic of 0.78 indicates that variation in the Russell 3000 index explains about 78% of the variation of NFMAX. The slope of the best-fit line (beta) is 1.26, indicating that NFMAX is substantially more volatile than the index. The y-intercept (weekly alpha) is 0.05%, indicating that NFMAX has provided some outperformance due to stock picking. However, indicative of the small sample or the non-normality of return distributions, exclusion of as few as two weekly observations makes the positive alpha disappear.
Substituting the investable iShares Russell 3000 Index (IWV) exchange-traded fund for the underlying index results in an R-squared statistic of 0.70, a beta of 1.29 and an alpha of 0.02%. However, again indicative of the small sample or the non-normality of return distributions, exclusion of a single extreme weekly observation can switch the alpha from positive to negative.
During this relatively short test period, stock picking has contributed a small but not reliable positive net alpha.
Next we look at market timing performance.
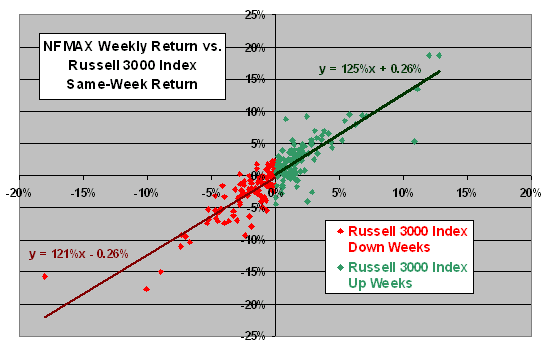
The fund may invest in “cash, or cash equivalents, for temporary defensive purposes or depending on market conditions, if we believe it will help protect the Portfolio from potential losses…” Material shifts in fund holdings to cash at the right times for defensive purposes should substantially reduce portfolio beta when the market declines. The next scatter plot relates NFMAX and Russell 3000 Index weekly returns separately for Russell 3000 Index down weeks and up weeks.
Beta is slightly lower for index down weeks than index up weeks (1.21 versus 1.25), but the subsamples are probably too small to conclude that the difference is meaningful. (For example, exclusion of one extreme down-week observation increases the beta for down weeks to 1.45.)
Note (with caution due to the limited subsample sizes) that NFMAX weekly alpha is materially negative during index down weeks and materially positive during index up weeks. The fund therefore gets a double boost (alpha plus beta) during market up weeks and a double whammy during market down weeks.
In summary, performance of Navellier & Associates, Inc. name-brand mutual fund at the weekly level over the past four years does not provide compelling evidence of reliable net benchmark outperformance based on either stock picking or market timing.
Frequently Asked Questions
What is alpha and beta in mutual fund performance analysis?
Alpha and beta are regression-based measures of fund performance against a benchmark. Beta (the slope of the best-fit line) measures sensitivity to the benchmark's returns, while alpha (the y-intercept) measures outperformance attributed to stock picking. In the Navellier Fundamental A fund (NFMAX) test from May 2005 to July 2009, beta was 1.26 and weekly alpha was 0.05% versus the Russell 3000 index.
Does the Navellier Fundamental A fund (NFMAX) beat the market through stock picking?
The Navellier Fundamental A fund (NFMAX) did not show reliable stock-picking outperformance of the Russell 3000 index from May 2005 through July 2009. Its weekly alpha was a small 0.05%, but excluding as few as two weekly observations makes that positive alpha disappear. Overall, the fund did not provide compelling evidence of reliable net benchmark outperformance from either stock picking or market timing.
How do you test a mutual fund's stock picking and market timing ability?
A mutual fund's stock picking is tested by regressing its weekly returns on a benchmark's same-week returns, with the intercept (alpha) capturing stock-picking skill and the slope (beta) capturing market sensitivity. Market timing is tested by running separate regressions for benchmark up weeks and down weeks, since effective timing should lower beta in down weeks. For NFMAX, the Russell 3000 regression had an R-squared of 0.78, and beta was 1.21 in down weeks versus 1.25 in up weeks.
Does using an investable ETF like IWV instead of the Russell 3000 index change a fund's alpha?
Using the investable iShares Russell 3000 ETF (IWV) instead of the Russell 3000 index lowered NFMAX's measured performance edge. The R-squared fell to 0.70, beta rose to 1.29, and weekly alpha dropped from 0.05% to 0.02%. Excluding a single extreme weekly observation can flip that alpha from positive to negative.
What are the limitations of judging a fund's alpha and market timing from weekly return regressions?
Weekly return regressions on short samples can produce unreliable alpha and beta estimates, especially when return distributions are non-normal. In the NFMAX test (May 2005–July 2009), dropping just two weekly observations erased the positive alpha, and dropping one extreme down-week raised down-week beta from 1.21 to 1.45. The up-week and down-week subsamples were probably too small to conclude that the beta difference was meaningful.