
Are newsletters good sources of stock picks? Specifically, do their recommendations persistently generate excess returns? In their October 1998 paper entitled “The Performance of Investment Newsletters”, Jeffrey Jaffe and James Mahoney tackle these questions. Using the investment newsletter archive of the Hulbert Financial Digest for 1980-1996, they determine that:
- Newsletters typically recommend 10-16 stocks. They tend to recommend growth rather than value stocks, smaller than the value-weighted average of market capitalizations. They generally encourage much higher turnover of holdings than that found among mutual funds.
- Newsletter common stock recommendations do not on average outperform appropriate benchmarks based on market capitalization, book-to-market and stock price. Including trading costs (and newsletter costs), newsletters likely underperform. Over the entire sample period, the mean monthly return of newsletter portfolios (without trading costs) is 1.32% versus 1.26% for the S&P 500 index.
- There is modest evidence of performance persistence based on raw returns, but not based on benchmarked returns. What persistence exists therefore may relate to investing style and not stock picking ability.
- Newsletters tend to recommend stocks with strong recent performance, but they do not herd on stock recommendations.
- Poor-performing newsletters have a greater likelihood of going out of business.
The following table, taken from this paper, provides the average raw and benchmarked returns (excluding trading costs) of newsletter stock portfolios. Benchmarking involves comparing returns for equally-weighted newsletter portfolios with those of equally-weighted portfolios of stocks with similar market capitalization, book-to-market and price characteristics. Results show that, after accounting for these general characteristics, the newsletters on average do not outperform. There is evidence that newsletters are better at recommending growth stocks than value stocks, but they show no special insight regarding small stocks.
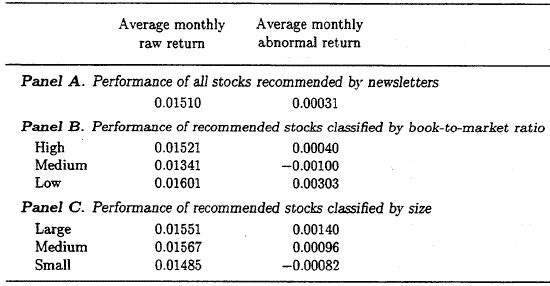
In summary, newsletters on average offer investors/traders average performance, without the broad diversification benefit of mutual funds.
Frequently Asked Questions
What is an investment newsletter and how do its stock recommendations work?
An investment newsletter is a subscription publication that recommends specific stocks or portfolios to investors. In the Hulbert Financial Digest archive studied for 1980-1996, newsletters typically recommended 10-16 stocks, tilted toward growth stocks and smaller-than-average market capitalizations, and encouraged much higher turnover than mutual funds.
Do investment newsletters beat the market with their stock picks?
Investment newsletter stock picks did not on average outperform appropriate benchmarks matched on market capitalization, book-to-market and stock price in the 1980-1996 Hulbert Financial Digest sample. Mean monthly return before trading and newsletter costs was 1.32% versus 1.26% for the S&P 500, and after costs newsletters likely underperform.
How do researchers benchmark newsletter stock recommendations to test performance?
Researchers benchmark newsletter performance by comparing returns of equally-weighted newsletter portfolios with equally-weighted portfolios of stocks having similar market capitalization, book-to-market and price characteristics. This isolates stock-picking skill from general style exposures. In the 1980-1996 Hulbert data, newsletters on average did not outperform after this adjustment.
Is newsletter performance persistence the same as stock-picking skill?
Performance persistence among investment newsletters is not the same as stock-picking skill. The 1980-1996 study found modest persistence in raw returns but none in benchmarked returns, suggesting persistence may reflect investing style, such as favoring recent winners or growth stocks, rather than ability.
What are the drawbacks of relying on investment newsletters for stock picks?
Investment newsletters on average offered only average performance in the 1980-1996 study, before trading and newsletter costs, and likely underperformed after those costs. Their portfolios of roughly 10-16 stocks lack the broad diversification of mutual funds, and they encourage higher turnover. Evidence of skill was limited to growth stocks, with no special insight on small stocks.