
In response to “Robustness of SACEMS Based on Sharpe Ratio”, a subscriber asked whether Martin ratio might work better than raw returns and Sharpe ratio for ranking assets within the Simple Asset Class ETF Momentum Strategy (SACEMS), which each month selects the best performers over a specified lookback interval from among the following eight asset class exchange-traded funds (ETF), plus cash:
PowerShares DB Commodity Index Tracking (DBC)
iShares MSCI Emerging Markets Index (EEM)
iShares MSCI EAFE Index (EFA)
SPDR Gold Shares (GLD)
iShares Russell 2000 Index (IWM)
SPDR S&P 500 (SPY)
iShares Barclays 20+ Year Treasury Bond (TLT)
Vanguard REIT ETF (VNQ)
3-month Treasury bills (Cash)
To investigate, we focus on the SACEMS equally weighted (EW) Top 3 portfolio and compare outcomes across lookback intervals ranging from one to 12 months for the following three asset ranking metrics:
- Raw return – cumulative total return over the lookback interval.
- Sharpe ratio (SR) – average daily excess return (asset return minus T-bill return) divided by standard deviation of daily excess returns over the lookback interval, with months approximated as 21 trading days. We set SR for Cash at zero (though it is actually zero divided by zero).
- Martin ratio (MR) – average daily excess return divided by the Ulcer Index calculated from daily returns over the lookback interval, with months again approximated as 21 trading days.
We employ gross compound annual growth rates (CAGR) and maximum drawdowns (MaxDD) to compare ranking metrics. Using monthly dividend-adjusted closing prices for asset class proxies and the yield for Cash during February 2006 (when all ETFs are first available) through December 2018, we find that:
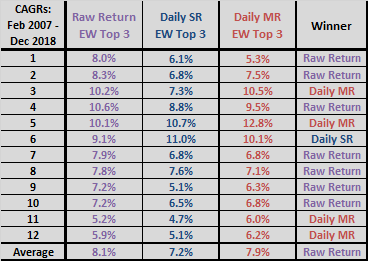
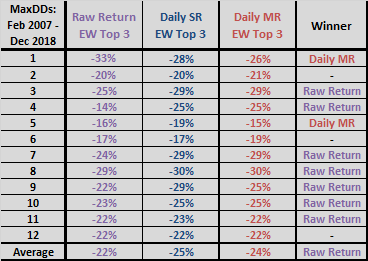
The following two tables compare gross CAGRs and MaxDDs for SACEMS EW Top 3 based on raw return, SR and MR across lookback intervals ranging from one to 12 months. First monthly returns are for March 2007 to accommodate the longest lookback interval of 12 months.
Regarding CAGRs:
- MR for a 5-month lookback stands out, but MR wins only four of 12 lookback intervals. Based on unevenness of performance, MR for a 5-month lookback interval appears to be lucky.
- Raw return wins seven of 12 lookback intervals and the overall average.
- In a sweet spot of lookback intervals (3-month to 6-month, which is favorable to MR compared to any wider range), average CAGR is 10.7% for MR versus 10.0% for raw return.
Regarding MaxDDs:
- MR for a 5-month lookback again stands out, but MR wins or ties only three of 12 lookback intervals.
- Raw return wins or ties 10 of 12 lookback intervals.
- In the above CAGR sweet spot of lookback intervals (3-month to 6-month), raw return wins or ties three of four. MR wins or ties one.
As when experimenting with lookback intervals, experimenting with different ranking metrics on the same dataset introduces data snooping bias. The more metrics tried, the greater the chance that a metric-lookback interval combination will have very lucky performance.
In summary, evidence from available data offers some support for belief that Martin ratio is better than raw return for monthly generation of the SACEMS EW Top 3 portfolio.
Cautions regarding findings include:
- Sample size is modest (about 13 independent 12-month lookback intervals), especially in terms of variety of market conditions.
- As noted, analyses are gross. Accounting for costs of monthly portfolio reformation would reduce returns. However, turnovers are similar for the competing metrics.
- As noted, testing multiple lookback intervals and different ranking metrics introduces data snooping bias, such that the best-performing combinations overstate expectations. Bias increases with the number of metrics tested.
- Calculating Sharpe ratio and Martin ratio with daily data is more complicated and time consuming than calculating raw cumulative returns.
Frequently Asked Questions
What is the Martin ratio and how is it different from the Sharpe ratio?
The Martin ratio is a risk-adjusted performance metric that divides average excess return (asset return minus T-bill return) by the Ulcer Index, which measures drawdown-based downside risk. The Sharpe ratio instead divides average excess return by the standard deviation of excess returns. In the SACEMS test, both were calculated from daily returns over the lookback interval.
Does ranking assets by Martin ratio beat ranking by raw returns in an ETF momentum strategy?
Ranking by Martin ratio offers only modest, inconsistent support over raw returns in the SACEMS equally weighted Top 3 portfolio. In the 3-to-6-month lookback sweet spot, average CAGR was 10.7% for Martin ratio versus 10.0% for raw return, but Martin ratio won only four of 12 lookback intervals while raw return won seven and the overall average. Raw return also won or tied 10 of 12 lookback intervals on maximum drawdown, versus three for Martin ratio.
How do you test different ranking metrics in a monthly ETF momentum strategy?
The SACEMS test each month ranks eight asset class ETFs plus cash by a chosen metric over a lookback interval of one to 12 months, then holds the top three in equal weights. Metrics compared were raw cumulative return, Sharpe ratio and Martin ratio, with months approximated as 21 trading days and Cash's Sharpe ratio set at zero. Performance was compared using gross CAGR and maximum drawdown from March 2007 through December 2018.
Is a Martin ratio better than a Sharpe ratio or simple return for choosing momentum assets?
A Martin ratio is not clearly better than raw return for choosing momentum assets in the SACEMS equally weighted Top 3 portfolio. Martin ratio with a 5-month lookback stood out, but the article judges it likely lucky given uneven performance across lookbacks. The article reports evidence offering only some support for Martin ratio over raw return, mainly in the 3-to-6-month lookback range.
What are the limitations of using the Martin ratio to rank assets in a momentum strategy?
The Martin ratio findings in the SACEMS test are limited by a modest sample of about 13 independent 12-month lookback intervals with little variety in market conditions. Testing multiple lookback intervals and ranking metrics on the same data introduces data snooping bias, so the best-performing combinations overstate expectations. Results are gross of the costs of monthly portfolio reformation, though turnovers are similar across metrics, and calculating Martin and Sharpe ratios from daily data is more complex than using raw returns.