
Are there reliable ways to exploit differences in asset class returns under Democratic and Republican U.S. presidents? In his April 2011 paper entitled “Is the 60-40 Stock-Bond Pension Fund Rule Wise?”, William Ziemba examines relationships between the U.S. presidential election cycle and long-run returns for several asset classes. Specifically, he investigates the differential performance of large capitalization stocks, small capitalization stocks and bonds when Democrats and Republicans hold the presidency. Using annual asset class return data for 1998 through 2010 to extend prior calculations for 1937-1997 and 1942-1997, he finds that:
- Small capitalization stocks (the bottom fifth) have higher returns during Democratic than Republican administrations, due mostly to the April-December annual interval. Small capitalization stocks significantly beat large capitalization stocks during January under both Democrats and Republicans.
- The performance of large capitalization stocks is unaffected by party in power.
- Returns on bonds and cash are higher during Republican than Democratic administrations.
- Regardless of party in power, both small and large capitalization stocks perform better during the last two years of the presidential term than the first two years.
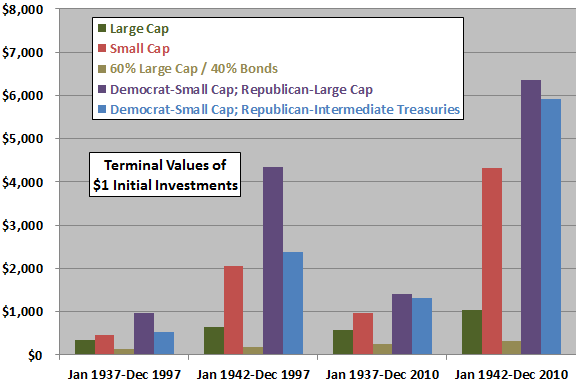
- Two simple investment strategies that hold small capitalization stocks (either large capitalization stocks or intermediate-term Treasuries) when Democrats (Republicans) hold the presidency outperform both buying and holding stocks and a conventional 60/40 stocks/bonds strategy over the entire sample period (see the first chart below). Results do not include trading frictions, but the two party-in-power strategies trade at most every four years.
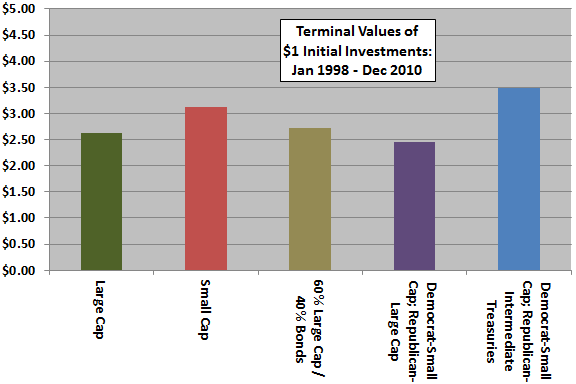
- However, outperformance of these two strategies over a recent subperiod that is arguably out-of-sample with respect to anomaly publication is less convincing (see the second chart below).
The following chart, constructed from data in the paper, summarizes terminal values at the end of December 2010 of $1 investments in five strategies initiated at the beginnings of January 1937 and January 1942 (with no trading frictions and presumably reinvestment of all dividends):
- Buy and hold Large Cap stocks (the S&P 500 Index).
- Buy and hold Small Cap stocks (20% of smallest market capitalizations)
- 60% Large Cap/40% Bonds (bond composition unspecified; rebalancing frequency presumably annual).
- Hold Small (Large) Cap stocks when the President is a Democrat (Republican).
- Hold Small Cap stocks (Intermediate Treasuries) when the President is a Democrat (Republican).
Results indicate that the two party-in-power strategies outperform benchmarks, and also that a relatively short interval (1937-1941) can have a large impact on outcomes.
The second chart, derived from data in the paper, summarizes terminal values for investments initiated at the beginning of January 1998 (arguably out-of-sample with respect to publication of the party-in-power strategies). Results cast some doubt on long-term findings, but the subperiod is short.
In summary, evidence suggests that investors may be able to exploit differences between Democratic and Republican presidencies by holding small capitalization stocks under Democrats and either large capitalization stocks or intermediate-term Treasuries under Republications.
Caution regarding findings include:
- Much of the analysis is in-sample, such that an investor operating in real time could not have known of the anomaly over much of the sample period.
- Given the variability of stock market returns, the sample used is not large in terms of number of presidential terms (17-18). The sample is quite short in terms of potentially confounding multi-term effects such as ebb and flow of inflation (critical to bond returns).
- The study states findings for multiple variables and subperiods, indicating that data snooping bias may be material.
- The study does not describe the statistical significance tests used, but likely assumes a tame distribution of returns.
- While the the two party-in-power strategies trade infrequently, the trading friction for forming and liquidating a portfolio representative of the fifth of stocks with the smallest market capitalizations is likely very high, and perhaps not feasible for modest accounts, over much of the sample period.
- Results from “Party in Power and Stock Returns” suggest that the party controlling the Senate may be more decisive for U.S. stock market returns than the party holding the presidency.
Frequently Asked Questions
What is a party-in-power investment strategy?
A party-in-power investment strategy shifts asset allocation based on whether a Democrat or Republican holds the U.S. presidency. In the William Ziemba study, one version holds small-cap stocks under Democrats and large-cap stocks under Republicans, while another holds small-cap stocks under Democrats and intermediate-term Treasuries under Republicans. Both trade at most once every four years.
Does the party in power in the White House affect stock and bond returns?
Party in power affects some asset classes but not others, according to Ziemba's 1937-2010 analysis. Small-cap stocks return more under Democratic than Republican presidents, bonds and cash return more under Republicans, and large-cap stock returns are unaffected by party. Both party-based strategies beat buy-and-hold stocks and a 60/40 stock/bond mix over the full sample, but outperformance is less convincing over 1998-2010.
How are presidential party strategies tested against buy-and-hold and 60/40 portfolios?
The study compares terminal values of $1 invested in five strategies from January 1937 and January 1942 through December 2010, using annual asset class return data (extended with 1998-2010 data). The strategies are buy-and-hold large caps (S&P 500), buy-and-hold small caps (smallest 20% by market capitalization), a 60/40 large-cap/bond mix, and the two party-in-power strategies. Results exclude trading frictions and presumably assume dividend reinvestment.
Is the presidential election cycle effect the same as the party-in-power effect?
No, the two effects are distinct. The presidential cycle effect is that both small-cap and large-cap stocks perform better in the last two years of a presidential term than in the first two, regardless of party. The party-in-power effect concerns differences in returns under Democratic versus Republican presidents. A related study, "Party in Power and Stock Returns," suggests the party controlling the Senate may matter more for U.S. stock returns than the party holding the presidency.
What are the limitations of trading stocks based on which party holds the presidency?
Presidential party strategies face several limitations: much of the analysis is in-sample, the sample covers only 17-18 presidential terms, and data snooping bias may be material because many variables and subperiods are tested. The study also does not describe its statistical significance tests, and multi-term effects such as inflation cycles may confound results. Trading frictions for building and liquidating a small-cap portfolio (the smallest fifth of stocks) are likely very high and may be infeasible for modest accounts.