
Does a simple countercyclical (contrarian) asset class allocation rule work well, wherein an investor assumes that a relatively high aggregate allocation to an asset class signals relatively low/risky future returns for that class? In his February 2016 paper entitled “Understanding Modern Portfolio Construction”, Cullen Roche reviews the principles of investing and portfolio construction and examines a simple countercyclical approach for adaptively balancing the risk of losing purchasing power versus the risk of permanent loss via a stocks-bonds portfolio. He hypothesizes that such an approach reduces behavioral risks. Using investment cycle indicators and world/U.S. stock and bond class returns as available during 1952 through 2015, he concludes that:
- The best way to construct a diversified and efficient portfolio is via annually rebalanced index funds consistently fed with fresh contributions.
- The global market portfolio and a basic 60-40 stocks-bonds portfolio are good allocation strategies.
- A countercyclical stocks-bonds allocation strategy that systematically inverts current relative aggregate allocations has lowest allocation to stocks when risk of loss is highest, thereby suppressing drawdowns.
- For world stocks and bonds during 1990-2015 (turbulent stock market):
- Countercyclical portfolio allocations generate compound annual growth rate (CAGR) 7.6%, with annual standard deviation 8.4% and largest annual drawdown -14%.
- A 60-40 portfolio generates CAGR 7.1%, with annual standard deviation 10.9% and largest annual drawdown -22%.
- For U.S. stocks and U.S. Treasuries during 1952-1980 (turbulent bond market):
- Countercyclical portfolio allocations generate CAGR 8.3%, with annual standard deviation 10.8%.
- A 60-40 portfolio generates CAGR 8.4%, with annual standard deviation 11.0%.
The following chart, taken from the paper, tracks relative aggregate allocations to stocks, bonds and cash since the beginning of 1993. Results suggest mean reversion of allocations over time. One approach to countercyclical asset allocation is to raise (lower) the allocation to a class when its current aggregate allocation is low (high). The paper notes that “there are countless ways in which one could calculate the procyclical risk in the markets…”
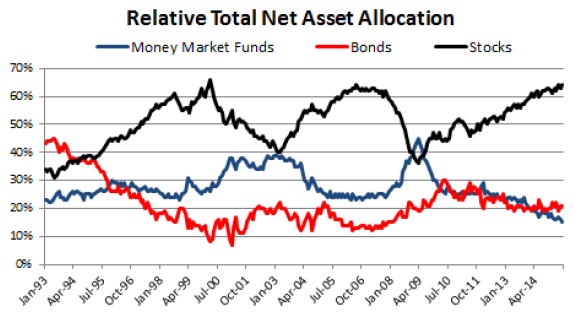
In summary, evidence suggests that a contrarian asset allocation strategy that bets against the aggregate allocations of other investors may be attractive.
Cautions regarding conclusions include:
- The sample is not large in terms of number of financial market cycles for testing mean reversion of asset class allocations and therefore the effectiveness of countercyclical allocation strategies.
- As noted in the paper, there are “countless” ways to measure cyclicality in financial markets. Experimenting to find the best countercyclical allocation strategy from among these measures would impound snooping bias in portfolio performance, thereby overstating expectations.
- The paper does not cite data sources or provide detail on portfolio performance calculations. The author separately reports that all data are from Bloomberg.
See “Average Investor Stock Allocation a Better Predictor than P/E10?”, which looks at aggregate allocation to stocks (only) as an indicator of future equity returns.
Frequently Asked Questions
What is a countercyclical asset allocation strategy?
A countercyclical asset allocation strategy is a contrarian approach that treats a relatively high aggregate investor allocation to an asset class as a signal of lower or riskier future returns for that class. It systematically inverts current aggregate allocations, so an investor holds less of an asset class when others hold more of it. The approach is meant to balance the risk of losing purchasing power against the risk of permanent loss, and it is hypothesized to reduce behavioral risks.
Does countercyclical asset allocation outperform a 60-40 stocks-bonds portfolio?
Countercyclical asset allocation outperformed a 60-40 portfolio for world stocks and bonds during 1990-2015, a turbulent stock market period, with compound annual growth rate (CAGR) of 7.6% versus 7.1%. It also had lower volatility (8.4% vs. 10.9%) and a smaller largest annual drawdown (-14% vs. -22%). For U.S. stocks and Treasuries during 1952-1980, a turbulent bond market, the two were essentially tied, with CAGR of 8.3% versus 8.4%.
How does a countercyclical stocks-bonds allocation rule work and how was it tested?
A countercyclical stocks-bonds allocation rule inverts the current relative aggregate allocations to asset classes, raising an allocation when it is low and lowering it when it is high. This produces the lowest stock allocation when risk of loss is highest. It was tested using investment cycle indicators and world and U.S. stock and bond returns from 1952 through 2015 with annual rebalancing, and compared against a 60-40 portfolio.
How does a countercyclical allocation compare to a 60-40 portfolio or the global market portfolio?
A countercyclical allocation adapts to shifts in aggregate investor allocations, while a 60-40 portfolio holds fixed weights. The paper considers both the global market portfolio and a basic 60-40 stocks-bonds portfolio to be good allocation strategies. The countercyclical approach did better than 60-40 in the 1990-2015 world stocks/bonds test (7.6% vs. 7.1% CAGR) but did not in the 1952-1980 U.S. test (8.3% vs. 8.4%).
What are the limitations of testing countercyclical asset allocation?
The countercyclical allocation tests have limited reliability because the sample covers few financial market cycles, which is too little to confirm that allocations mean revert reliably. There are also countless ways to measure market cyclicality, so searching for the best one would introduce snooping bias and overstate expected performance. In addition, the paper does not cite data sources or detail its portfolio performance calculations, though the author separately reports that all data come from Bloomberg.