
How do analyst earnings forecasts vary across financial reporting periods? Does the desire of analysts to maintain a good relationship with firm management affect earnings forecasts? In their February 2007 paper entitled “Relationship Incentives and the Optimistic/Pessimistic Pattern in Analysts’ Forecasts”, Robert Libby, James Hunton, Hun-Tong Tan and Nicholas Seybert report the results of controlled blind experiments involving experienced sell-side financial analysts that address these questions. Using information gained from “training sessions” for a group of 47 analysts from a single large investment banking/brokerage firm and 34 analysts from a medium-sized regional brokerage firm, they conclude that:
- Earnings forecasts trend from optimistic to pessimistic (walk down) across quarterly financial periods.
- This walk-down effect is significantly stronger when the analysts involved have a good relationship with management.
- Analysts are aware of both the general downward bias in management guidance and the walk-down pattern of their own forecasts. They view the walk-down as beneficial (favored conference call participation and information access) to future relationships with firm management and with brokerage clients.
- This behavior is independent of analyst demographics such as age and years of experience, and of past analyst forecast accuracy.
- Recent regulatory changes (Regulation FD and Regulation AC) may have reduced but have not eliminated this type of conflict of interest.
The following chart, taken from the paper, compares the quarterly earnings forecast walk-downs when analysts are concerned only with forecast accuracy and when they have developed a good relationship with the covered firm. The relationship amplifies the quarterly walk-down with more optimistic beginning forecasts and more pessimistic ending forecasts.
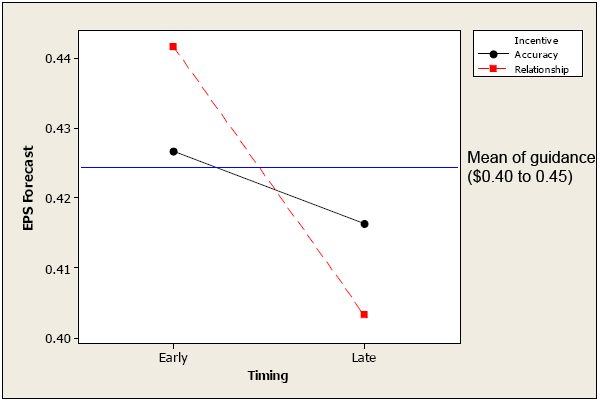
In summary, analysts tend to walk their earnings forecasts down as release of actuals approaches, and this walk-down effect is stronger for analysts that have good relationships with management.
Assuming most firms report by calendar quarter, the above results suggest that stock returns in the first half of calendar quarters (when earnings releases tend to counter pessimistic forecasts from the end of the prior quarter and forecasts for next quarter tend to be most optimistic) might outperform stock returns in the second half of calendar quarters (as earnings forecasts for the next quarter drift toward pessimism). To test this implication, we calculate returns for the S&P 500 index since the beginning of 1990 for two types of intervals:
Type 1 – From the close on the first day of each calendar quarter to the close on the calendar 15th (or as close as possible to the 15th) of the middle month of that calendar quarter; and,
Type 2 – From the close on each calendar 15th (or as close as possible to the 15th) of the middle month of a calendar quarter to the the close on the first day of the next calendar quarter.
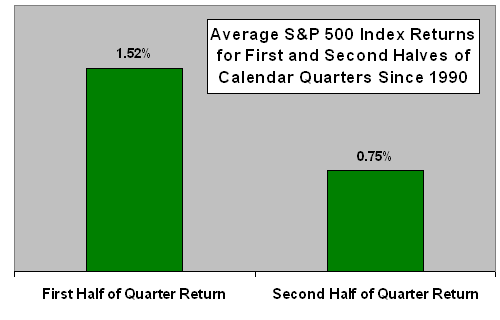
The average return for all 138 intervals is 1.14%. As summarized in the following chart, the average return for Type 1 intervals is 1.52%, compared to only 0.75% for Type 2 intervals. This result supports the corollary that the quarterly drift of earnings forecasts toward pessimism may affect stock prices.

Frequently Asked Questions
What is the analyst earnings forecast walk-down?
The analyst earnings forecast walk-down is the tendency of analysts' earnings forecasts to move from optimistic to pessimistic as the release of actual quarterly results approaches. It was documented in controlled blind experiments with experienced sell-side analysts from two brokerage firms (47 and 34 analysts). Analysts view the pattern as beneficial for relationships with firm management and brokerage clients.
Does the quarterly earnings forecast walk-down affect stock returns?
The quarterly earnings forecast walk-down may affect stock prices, according to a test using S&P 500 returns since 1990. The average return was 1.52% for intervals from the first day of a calendar quarter to about the 15th of its middle month, versus 0.75% for intervals from that date to the start of the next quarter. The average across all 138 intervals was 1.14%.
How do researchers test whether analysts' relationships with management change earnings forecasts?
Researchers tested the effect of management relationships using controlled blind experiments with experienced sell-side analysts, drawing on training sessions with 47 analysts from a large investment banking/brokerage firm and 34 from a medium-sized regional brokerage. They compared quarterly forecast walk-downs when analysts were concerned only with forecast accuracy against when they had a good relationship with the covered firm. A good relationship amplified the walk-down, producing more optimistic initial forecasts and more pessimistic final forecasts.
Is the earnings forecast walk-down the same as general analyst optimism bias?
The earnings forecast walk-down is not the same as a general analyst optimism bias, because it describes a pattern within the quarterly cycle in which forecasts shift from optimistic to pessimistic. Analysts in the study were aware of both the general downward bias in management guidance and the walk-down in their own forecasts. The pattern was stronger with good management relationships and was independent of analyst age, years of experience, and past forecast accuracy.
What are the limitations of using the earnings forecast walk-down to time stock returns?
The return test of the earnings forecast walk-down assumes most firms report by calendar quarter and uses only S&P 500 returns since 1990, so it supports the idea only as an implication rather than proof. The gap between 1.52% and 0.75% average returns is described as consistent with the walk-down affecting prices, not as a confirmed cause. The underlying analyst findings come from experiments with two brokerage firms, and regulatory changes (Regulation FD and Regulation AC) may have reduced but not eliminated the conflict of interest.