
Can investors apply forensic accounting principles (searching for inconsistencies, irregularities and other signs of trouble) to help forecast stock returns? In their July 2011 paper entitled “To Catch a Thief: Can Forensic Accounting Help Predict Stock Returns?”, Messod Beneish, Charles Lee and Craig Nichols investigate the ability of an earnings manipulation model to predict stock returns and detect fraud. The model, which relies exclusively on financial statement data, consists of eight ratios indicative of either financial statement distortions associated with earnings manipulation or a predisposition to engage in earnings manipulation. Specifically, four of the ratios detect unusual buildup in receivables, unusual expense capitalization and dependence of profits on accruals. The other four ratios detect deteriorating gross margins and increasing administration costs, high sales growth and increasing reliance on debt financing. The model calibration period is 1982-1988, and its initial test period is 1989-1992. Using the exact model published in the Financial Analyst Journal in 1999 as applied to accounting data and stock returns for a broad sample of NYSE, AMEX, and NASDAQ over the period 1993 through 2007 (33,848 firm-year observations, excluding financial services firms and small firms), they find that:
- The model flags 14.5% of all firms as potential profit manipulators. The original research suggests that, on average, manipulators tend to be smaller, less profitable, more levered and faster growing than peers.
- The model correctly identifies in advance 12 of the 17 highest profile 1998-2002 fraud cases.
- A hedge portfolio that is short (long) flagged stocks (other stocks), reformed monthly with apparently equal weights during 1993 through 2007, generates a gross annualized size-adjusted return of 9.7% (6.6 % from the short side and 3.1% from the long side). The portfolio is profitable at a gross level in 13 out of 15 years. In other words, “looking like a thief” indicates poor future performance.
- A multivariate regression of returns against market capitalization, book-to-market ratio, total accruals, return momentum, short interest level and probability of profit manipulation indicates that probability of manipulation is among the strongest of the associated six return anomalies.
- Augmenting decile sorts of the other five indicators with probability of manipulation greatly improves hedge returns (see the chart below). A hedge portfolio that is :
- Long (short) the tenth of firms with the smallest (largest) market capitalization generates a gross annualized size-adjusted return of 5.0%. Limiting the long (short) side to non-flagged (flagged) firms boosts this return to 14.8%.
- Long (short) the tenth of firms with the highest (lowest) book-to-market ratio generates a gross annualized size-adjusted return of 8.7%. Limiting the long (short) side to non-flagged (flagged) firms boosts this return to 15.4%.
- Long (short) the tenth of firms with the highest (lowest) return momentum generates a gross annualized size-adjusted return of 9.2%. Limiting the long (short) side to non-flagged (flagged) firms boosts this return to 23.5%.
- Long (short) the tenth of firms with the lowest (highest) short interest ratio generates a gross annualized size-adjusted return of 6.1%. Limiting the long (short) side to non-flagged (flagged) firms boosts this return to 15.3%.
- Long (short) the tenth of firms with the lowest (highest) accruals generates a gross annualized size-adjusted return of 8.3%. Limiting the long (short) side to non-flagged (flagged) firms boosts this return to 13.3%.
- An ability to separate firms with accruals that are more likely to persist from those with accruals that are more likely to reverse drives model effectiveness. The model is particularly effective in predicting returns among low-accruals firms (firms with superficially high earnings quality).
The following chart, taken from the paper, illustrates the enhancement of the accruals effect from including probability of manipulation flags. A hedge strategy that is long (short) the tenth of firms with the lowest (highest) accruals generates a gross annualized size-adjusted return of 8.3%. Limiting the long (short) side to non-flagged (flagged) firms boosts this return to 13.3%.
Exploiting flagged firms with low accruals may be especially attractive.
The paper presents similar charts for forensic enhancement of the size effect, value premium, momentum and short interest effect.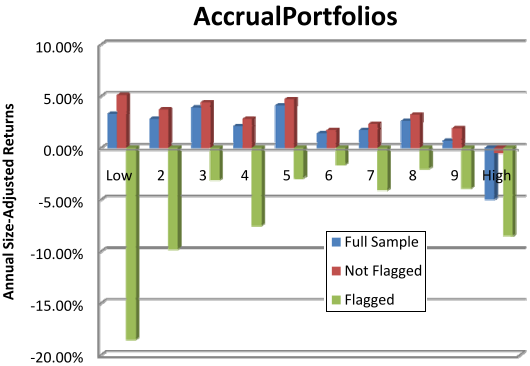
In summary, evidence indicates that investors may be able to improve their stock picking materially by applying forensic accounting principles to identify firms that are potential profit manipulators.
Cautions regarding findings include:
- Return calculations are gross, not net. Accounting for reasonable trading frictions would materially reduce profitability of hypothethical trading strategies. Profitability may well be concentrated in stocks that are most costly to trade.
- As noted, the study excludes financial services firms and very small firms and may not work for them.
Frequently Asked Questions
What is an earnings manipulation model in forensic accounting?
An earnings manipulation model is a forensic accounting tool that uses only financial statement data to estimate the probability a firm is manipulating its reported profits. The Beneish model tested in the article uses eight ratios: four detect distortions such as unusual receivables buildup, expense capitalization and reliance on accruals, and four detect deteriorating gross margins, rising administration costs, high sales growth and increasing debt financing.
Does forensic accounting help predict stock returns?
Forensic accounting, via an earnings manipulation model, helped predict stock returns in the 1993-2007 test period. A hedge portfolio short flagged stocks and long other stocks earned a gross annualized size-adjusted return of 9.7% (6.6% from the short side, 3.1% from the long side) and was profitable in 13 of 15 years. The model also flagged 12 of the 17 highest-profile 1998-2002 fraud cases in advance.
How is the probability of earnings manipulation used to improve factor strategies like momentum and value?
The probability of earnings manipulation is used as a filter on decile-sorted long/short hedge portfolios, limiting the long side to non-flagged firms and the short side to flagged firms. During 1993-2007 this raised gross annualized size-adjusted returns from 9.2% to 23.5% for momentum, 8.7% to 15.4% for book-to-market value, 6.1% to 15.3% for short interest, 8.3% to 13.3% for accruals, and 5.0% to 14.8% for size. The model works largely by separating firms whose accruals are likely to persist from those whose accruals are likely to reverse.
How does earnings manipulation probability compare to accruals, momentum, and short interest as a return predictor?
In a multivariate regression including market capitalization, book-to-market, total accruals, momentum, short interest and probability of manipulation, probability of manipulation was among the strongest of the six return anomalies. It also complements the others rather than replacing them, since adding it to decile sorts of the other five indicators greatly improved hedge returns. It was particularly effective among low-accruals firms, which superficially appear to have high earnings quality.
What are the limitations of using an earnings manipulation model to pick stocks?
The reported returns of earnings manipulation model strategies are gross, not net, so reasonable trading frictions would materially reduce profitability. Profits may also be concentrated in stocks that are most costly to trade. The study excluded financial services firms and very small firms, so the model may not work for them.