
Does the S&P 500 implied volatility index (VIX) exhibit predictable behaviors around holidays? If so, is the predictability exploitable? To check, we look at percentage changes in VIX from three trading days before to three trading days after the following annual holidays: New Year’s Day, Super Bowl, Good Friday, Memorial Day, 4th of July, Labor Day, Thanksgiving and Christmas. To test exploitability, we employ iPath S&P 500 VIX ST Futures ETN (VXX), exchange-traded notes that hold short-term VIX futures. Using daily closes of VIX and VXX from their respective inceptions (January 1990 and February 2009) through November 2016 (214 and 62 holidays), we find that:
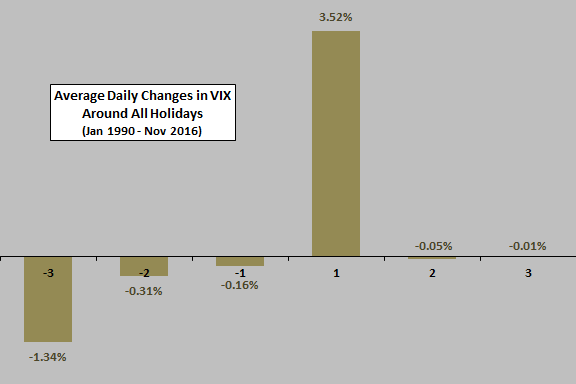
The following chart summarizes average daily percentage changes in VIX from three trading days before (-3) through three trading days after (3) holidays across all 214 holidays in the available sample period. The average daily percentage change in VIX over the entire sample period is 0.20%. Results indicate that VIX tends to decline leading up to holidays but increase strongly the day after holidays.
Do these results hold for each holiday?
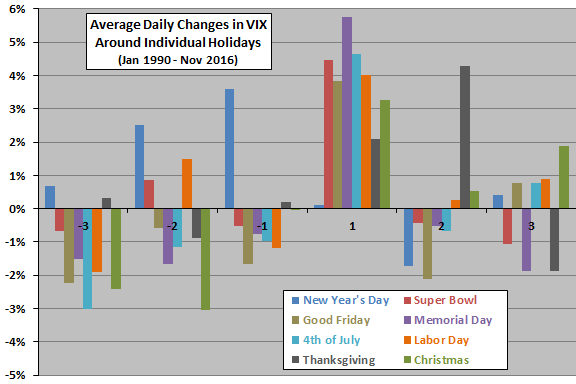
The next chart summarizes average daily percentage changes in VIX from three trading days before through three trading days after holidays for each of the eight holidays in the available sample period (26-27 observations each). The above findings hold for most holidays, but New Year’s Day and Thanksgiving exhibit pronounced differences.
Are results exploitable via VIX derivatives?
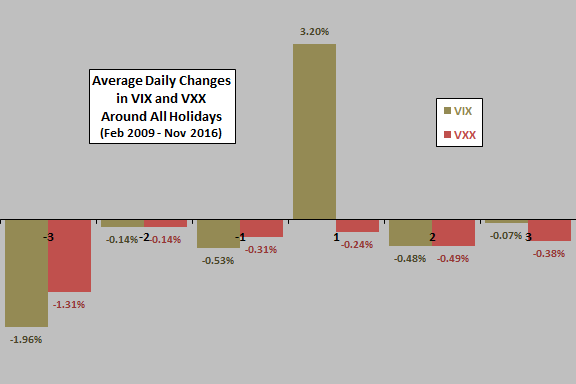
The next chart summarizes average daily percentage change in VIX and average daily return for VXX from three trading days before through three trading days after holidays for all 62 holidays since VXX inception in February 2009. The average daily percentage change in VIX (VXX) over this subperiod is 0.21% (-0.27%).
VIX behavior is consistent with that found above for the entire sample period, but VXX traders apparently anticipate the spike in VIX the day after holidays such that VXX does not rise with VIX.
Does variability of results differ over the event window?
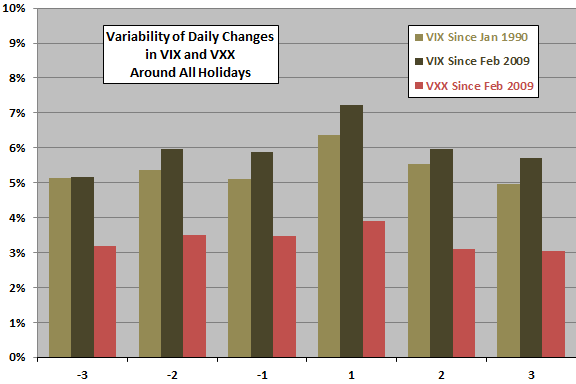
The final chart summarizes standard deviations of daily VIX changes and VXX returns from three trading days before through three trading days after holidays for all holidays since inceptions of both. Results consistently indicate that variability of VIX changes and VXX returns is highest on the day after a holiday.
In summary, evidence from simple tests on available data indicates that VIX tends to jump on the day after holidays, but VIX futures traders (and therefore VXX) apparently anticipate this jump.
Note that the first trading day after two holidays (Good Friday, Super Bowl) and the second trading day after Thanksgiving are Mondays, in consonance with findings in “VIX Calendar Effects”.
Cautions regarding findings include:
- The subsamples for individual holidays since VIX inception are not large, limiting confidence in results.
- The sample of all holidays since VXX inception is not large, limiting confidence in results (although consistency in VIX behaviors for the overall sample and the recent subperiod obviate this concern).
See “Exploit Short-term VIX Reversion with VXX?” and “Short-term VIX Calendar Effects” for other examples of VIX tendencies apparently not exploitable via VXX.
Frequently Asked Questions
What is the VIX and what does it measure in investing?
The VIX is the S&P 500 implied volatility index, which reflects the market's expectation of near-term stock market volatility derived from S&P 500 option prices. In the article, VIX daily percentage changes are examined around eight annual holidays, with a sample-wide average daily change of 0.20% (January 1990 through November 2016).
Does the VIX predictably jump after holidays?
Yes, the VIX tends to decline leading up to holidays and then increase strongly the day after holidays, with an average jump of about 1.5% across 214 holidays from January 1990 through November 2016. The pattern holds for most of the eight holidays tested, though New Year's Day and Thanksgiving show pronounced differences.
How do you test whether VIX holiday patterns can be traded using VXX?
The test compares average daily percentage changes in the VIX with average daily returns of VXX, an exchange-traded note holding short-term VIX futures, from three trading days before to three trading days after each holiday. It covers eight holidays (New Year's Day, Super Bowl, Good Friday, Memorial Day, 4th of July, Labor Day, Thanksgiving and Christmas), using 62 holidays since VXX inception in February 2009 through November 2016. The VIX averaged 0.21% daily over this subperiod versus -0.27% for VXX.
Why does VXX not rise when the VIX jumps after a holiday?
VXX does not rise with the VIX after holidays because VIX futures traders apparently anticipate the post-holiday spike and price it in beforehand. VXX holds short-term VIX futures rather than the VIX itself, so it does not capture the VIX's day-after-holiday jump. Over the 62 holidays since February 2009, VIX behavior matched the full-sample pattern while VXX did not follow.
What are the limitations of the VIX holiday effect findings?
The subsamples for individual holidays are small (26-27 observations each), and the sample of 62 holidays since VXX inception is also small, limiting confidence in the results. The article notes that the consistency between VIX behavior in the full sample and the recent subperiod reduces the latter concern. The tests are also simple, based on daily closes and average changes.