
Is the value premium readily accessible for individual investors? Which value strategy works best? In his May 2009 article entitled “Can Individual Investors Capture The Value Premium?”, Patrick Larkin uses a ranking methodology to compare the performances of Joel Greenblatt’s magic formula and seven other one and two-factor growth at a reasonable price (GARP) and value strategies. The portfolios for the eight strategies derive from rankings on: (1) the magic formula, a combination of return on capital (ROC) and the ratio of earnings before interest and taxes to Enterprise Value ((EBIT/EV); (2) a combination of return on assets (ROA) and earnings yield (E/P); (3) a combination of return on equity (ROE) and E/P; (4) EBIT/EV alone; (5) E/P alone; (6) a combination of book-to-market ratio (B/M) and market capitalization (Size); (7) B/M alone; and, (8) Size alone. Each month, the author forms equally weighted portfolios of the 30 highest-ranking stocks for each of these eight strategies. Using monthly stock return and GARP-value metric data for a broad sample of firms with market capitalizations over $50 million during December 1998-2006 (97 months), he finds that:
- The GARP-value-size strategies tend to select small capitalization stocks.
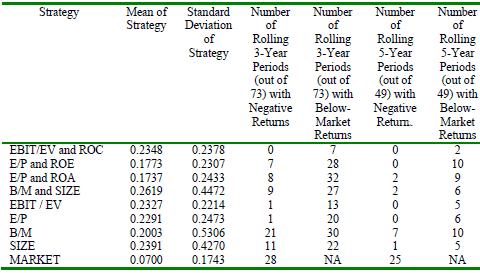
- All eight strategies substantially beat the broad stock market based on average returns over the 97 rolling one-year holding periods in the sample (see table below). Apparently, simple strategies can continue to work even after investors are broadly aware of them.
- While the eight strategies have higher standard deviations of returns across the 97 rolling one-year holding periods than the broad stock market, they are less likely to produce negative returns over any three-year or five-year period.
- To benefit from GARP-value-size strategies, it appears that investors must be able to resist bailing out during occasional intervals of underperformance.
The following table, extracted from the article, lists performance metrics for the eight GARP-value-size investment strategies as calculated from 97 rolling one-year holding periods. The magic formula (EBIT/EV and ROC combined), EBIT/EV alone and E/P alone have similar outstanding average returns and relatively low standard deviations of returns. The magic formula excels in risk management, never in the red for any three or five-year period and underperforming the broad stock market in only seven (two) of 73 rolling three-year (49 rolling five-year) periods. EBIT/EV alone and E/P alone also perform reasonably well on risk measures. B/M and Size combined have the highest average annual return (26.2%) but also a very high volatility.
Results do not address trading frictions or portfolio turnover. Including 97 monthly iterations of associated costs would materially reduce returns. Differences in these costs among strategies could affect their relative performance.
Note that the sample period for this study is relatively short, with effective sample size much smaller than 97, 73 or 49 because of the large overlap in rolling periods.
In summary, evidence from narrow portfolios (top 30 stocks) over a recent short test period indicate that GARP-value-size strategies perform well, with the magic formula (EBIT/EV and ROC combined), EBIT/EV alone and E/P alone excelling.
Frequently Asked Questions
What is Joel Greenblatt's magic formula for value investing?
Joel Greenblatt's magic formula is a stock-ranking strategy that combines return on capital (ROC) with the ratio of earnings before interest and taxes to enterprise value (EBIT/EV). Stocks ranking highest on the combination are selected as growth at a reasonable price (GARP) or value candidates. In the study, the formula was used to form equally weighted portfolios of the 30 highest-ranking stocks each month.
Do GARP and value strategies beat the stock market?
GARP and value strategies beat the broad stock market in one study of eight such strategies. All eight substantially outperformed on average returns over 97 rolling one-year holding periods during December 1998-2006. The magic formula, EBIT/EV alone and E/P alone had the strongest results, but the evidence comes from a short sample of narrow top-30 portfolios.
How are value and GARP stock portfolios built and tested using rankings?
The study ranked stocks each month on eight metrics or metric combinations: magic formula, ROA with E/P, ROE with E/P, EBIT/EV, E/P, B/M with size, B/M and size. Equally weighted portfolios of the 30 highest-ranking stocks were formed for each strategy from a broad sample of firms with market capitalizations over $50 million. Performance was measured over 97 rolling one-year holding periods during December 1998-2006.
How does the magic formula compare with simple value metrics like earnings yield or book-to-market?
The magic formula performed similarly to EBIT/EV alone and E/P alone, with all three showing outstanding average returns and relatively low standard deviations. The magic formula stood out on risk management, never losing money over any three or five-year period and underperforming the broad market in only seven of 73 rolling three-year and two of 49 rolling five-year periods. B/M combined with size had the highest average annual return (26.2%) but very high volatility.
What are the limitations of backtests of magic formula and value strategies?
The backtest of the magic formula and other value strategies ignores trading frictions and portfolio turnover, and including costs from 97 monthly rebalancings would materially reduce returns. The sample period is short, and the effective sample size is much smaller than 97, 73 or 49 because rolling periods overlap heavily. The strategies also had higher return volatility than the broad market, so investors must resist bailing out during underperformance.