
Are collectible (mint state, brilliant uncirculated or proof) U.S. coins attractive to investors as an alternative asset class? In their October 2019 paper entitled “U.S. Coins Market: Historical Performance and Anomalies”, Khaled Obaid, Kuntara Pukthuanthong and David Maslar measure historical returns within the multi-billion dollar collectible U. S. coins market and determine what investors should require and avoid when selecting coins. They also examine whether collectible coins are effective diversifiers of conventional asset classes and are useful as an inflation hedge. They construct their sample manually from bid and ask prices of U.S. penny, nickel, dime, quarter, half dollar and dollar coins as listed in the first CDN Publishing Greysheet of each calendar year. They assume that the average of bid and ask for a coin is a sale price. Using price data for 2,063 coins during 1967 through 2015, they find that:
- Average age of coins in the sample is 34.6 years, with average (median) price $1,333 (only $38.00). 22% are proofs, and 10% are part of special mint sets. Average bid-ask spread is 8%, increasing from 6.1% at the beginning of the sample period to 10.9% by the end.
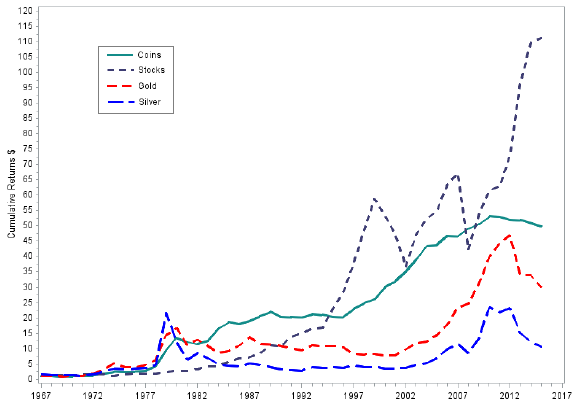
- Average annual nominal (real) return for coins is 9.7% (5.5%) with standard deviation 40.8%. Annual real returns range from -20.7% in 1981 to 105.3% in 1979 and are negative in 18 of 49 years. (See the chart below.)
- Older coins, proof sets and coins minted in smaller quantities tend to have higher prices, and higher-priced coins tend to have higher returns.
- Nominal coin market annual returns have high correlations with gold (0.72) and silver (0.72), moderate correlation with stamps (0.50), near zero correlation with the S&P 500 Index (-0.03) and negative correlation with corporate bonds (-0.27).
- Adding coins to an annually rebalanced mean-variance optimized portfolio of:
- Stocks and bonds indicates a 25% optimal weight for coins, boosting gross annual Sharpe ratio from 0.49 to 0.64.
- Stocks, bonds, gold and silver indicates a 28% optimal weight for coins, boosting gross annual Sharpe ratio from 0.59 to 0.68.
- Coins are generally effective at hedging against both expected and unexpected inflation.
- Coins exhibit cross-sectional and time series (intrinsic or absolute) momentum over intervals of one to five years.
- Newly issued coins materially underperform (for example, by -7.7% at age 2).
The following chart, taken from the paper, compares cumulative values of $1 investments at the beginning of 1967 in collectible coins, the S&P 500 Index, gold and silver. A dollar invested in coins grows to $49.90 by the end of 2015, compared to $30.00 for gold, $10.72 for silver and $111.22 for the S&P 500 Index.
In summary, evidence suggests that U.S. collectible coins may be an attractive long-term diversifier of conventional assets for portfolios of modest size.
Cautions regarding findings include:
- As noted, collectible coins have large bid-ask spreads, and reported returns are gross, not net. Moreover, the market may be thin (especially for rarer coins with strong returns), such that trading large positions would materially affect price. These coins may therefore be suitable only for small investors with very long investment horizons. In addition:
- The effort required to research and execute coin trades may be substantial.
- A coin collection requires physical storage with associated costs and risk of damage/loss.
- As noted in the paper, trading volume rises and returns fall over the sample period, suggesting that expected return should be materially lower than the full sample average. Also, the extraordinarily positive return for coins in 1979 may be an outlier that distorts expectations.
Browse the Aesthetic Investments category for analysis of other kinds of collectibles.
Frequently Asked Questions
What are collectible U.S. coins and how are they used as an alternative investment?
Collectible U.S. coins are mint state, brilliant uncirculated or proof pennies, nickels, dimes, quarters, half dollars and dollars that investors buy as an alternative asset class. The market is worth many billions of dollars. Coins are considered for diversification of conventional assets and as a possible inflation hedge, though trading them involves large bid-ask spreads and physical storage.
Do collectible U.S. coins outperform stocks, gold and silver over the long term?
Collectible U.S. coins did not outperform the S&P 500 Index over 1967-2015, but they beat gold and silver. A $1 investment in coins grew to $49.90, versus $111.22 for the S&P 500, $30.00 for gold and $10.72 for silver. Coins averaged 9.7% nominal (5.5% real) annual return, and the paper suggests they may be an attractive long-term diversifier for modest-sized portfolios.
How are historical returns on collectible coins measured?
Collectible coin returns are measured using bid and ask prices for U.S. penny, nickel, dime, quarter, half dollar and dollar coins from the first CDN Publishing Greysheet of each year. The researchers assume the average of bid and ask is the sale price. The sample covers 2,063 coins over 1967 through 2015, and the reported returns are gross of trading costs.
Are collectible coins a good portfolio diversifier compared with gold, silver, stamps and bonds?
Collectible coins are highly correlated with gold (0.72) and silver (0.72), moderately with stamps (0.50), and show near zero correlation with the S&P 500 Index (-0.03) and negative correlation with corporate bonds (-0.27). Adding coins to a mean-variance optimized portfolio of stocks and bonds suggests a 25% weight and raises gross annual Sharpe ratio from 0.49 to 0.64. With stocks, bonds, gold and silver, the optimal coin weight is 28%, lifting Sharpe ratio from 0.59 to 0.68.
What are the risks and drawbacks of investing in collectible coins?
Collectible coin investing is limited by large bid-ask spreads averaging 8% (rising from 6.1% to 10.9% over the sample), so reported returns are gross rather than net. The market may be thin, especially for rarer coins, so large trades could move prices, and research, execution and physical storage add effort, cost and risk of loss or damage. Returns fell and trading volume rose over the sample period, and the extreme 1979 return may be an outlier, so future expected returns are likely materially below the 9.7% full-sample average.