
Does a decade of underperformance by some widely followed stock value strategies mean it is time to throw in the towel? In their March 2020 paper entitled “Is (Systematic) Value Investing Dead?”, Ronen Israel, Kristoffer Laursen and Scott Richardson assess the value of (near-term, say two years) fundamental information as a driver of stock returns from both theoretical and empirical perspectives. They consider five widely used measures of value: (1) book value-to-price ratio (B/P); (2) earnings-to-price ratio (E/P); (3) forward earnings-to-price ratio (FEP); (4) sales-to-enterprise value ratio (S/EV); and, (5) cash flow-to-enterprise value ratio (CF/EV). They also investigate several recent arguments against value investing. Using data for large (small) capitalization stocks spanning 21 (25) countries with sample periods starting between 1984 and 2002 and all extending through 2019, they find that:
- Over available sample periods, based on portfolios that are long (short) the fifths of stocks with the highest (lowest) value measures, evidence is strongest for a gross value premium among small stocks and for E/P, S/EV and CF/EV measures of value.
- 24 of 30 possible global combinations (five measures of value, large and small stocks, three global regions) exhibit statistically significant gross value premiums over full sample periods. 15 of 30 premiums are highly significant.
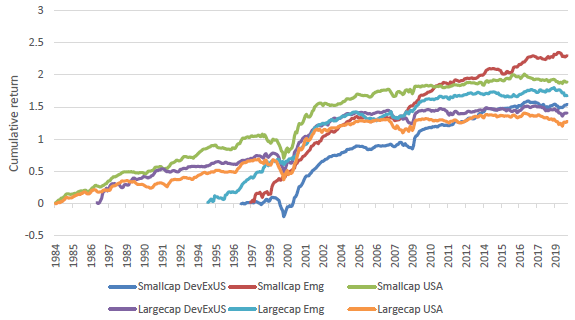
- An equal risk-weighted combination of the five value ratios that is country sector-adjusted, country rank-weighted/dollar-neutral and aggregated across countries by weighting each country by the square-root of its number of companies has done well on a gross basis over the last three decades across developed and emerging markets. However, over the last decade, large value and small U.S. value is weak (see the chart below).
- Controlling for sector or industry membership clearly improves value strategy gross Sharpe ratio. This approach essentially expands value breadth from a few sector/industry views to many stock-specific views.
- Evidence that share repurchase activity suppresses the value premium is mixed. For example, there is no evidence that B/P is a worse indicator of value for firms that repurchase the most.
- It is unlikely that growing importance of intangibles or changes in business models explains recent underperformance of value strategies.
- There is little empirical support for belief that low interest rates suppress the value premium.
- Value spreads (difference in average B/P between high-value and low-value stocks) have recently widened, making crowding an unlikely explanation for weakness of value strategies.
- There are times, such as recently, when stock prices become less connected with fundamentals and value strategies underperform.
The following chart, taken from the paper, tracks cumulative gross premiums for the combination value strategy (combining value measures) described above for large and small stocks separately for the U.S., global developed markets excluding the U.S., and global emerging markets as data become available. Premiums for large stocks and for small stocks in the U.S. are weak over the last decade.
In summary, widely used stock value strategies have not worked well in most markets over the past decade, but the overall body of evidence for value investing does not justify throwing in the towel on value investing.
Cautions regarding findings include:
- Reported performance data are gross, not net. Accounting for costs of periodic value portfolio reformation and shorting costs/constraints would reduce returns (making value even less attractive recently).
- Strategies described are beyond the reach of most investors, who pay fees for delegating to a fund manager.
- Different investors have different tolerances for when to throw in the towel.
See also the recent “Value Investing Dead?” and “Value Investing Not Dead?”.
Frequently Asked Questions
What is systematic value investing and which ratios are used to measure it?
Systematic value investing is a strategy that goes long stocks with the highest value measures and short those with the lowest, using near-term fundamental information as a driver of returns. The study uses five common measures: book value-to-price (B/P), earnings-to-price (E/P), forward earnings-to-price (FEP), sales-to-enterprise value (S/EV), and cash flow-to-enterprise value (CF/EV). Portfolios are long (short) the fifths of stocks with the highest (lowest) value measures.
Does value investing still work after a decade of underperformance?
Value investing still shows evidence of working over full sample periods, despite weakness over the last decade. 24 of 30 global combinations (five value measures, large and small stocks, three regions) show statistically significant gross value premiums, and 15 of 30 are highly significant. Evidence is strongest for small stocks and for E/P, S/EV and CF/EV, but large and small U.S. value have been weak over the last decade.
How is a combined value strategy built and tested across countries?
The combined value strategy is an equal risk-weighted blend of the five value ratios, adjusted for country sector, rank-weighted and dollar-neutral within each country. Countries are aggregated by weighting each by the square root of its number of companies. It was tested on large stocks (21 countries) and small stocks (25 countries), with sample periods starting between 1984 and 2002 and all ending in 2019. Controlling for sector or industry membership improved the gross Sharpe ratio by broadening value from a few sector views to many stock-specific views.
Do share buybacks, low interest rates, intangibles or crowding explain why value stocks have lagged?
The study finds little support for these explanations of recent value underperformance. Evidence that share repurchases suppress the value premium is mixed, and B/P is not a worse value indicator for firms that repurchase the most. Intangibles or business model changes are unlikely explanations, there is little support for low interest rates suppressing value, and widening value spreads make crowding unlikely. The authors instead say value underperforms at times when stock prices become less connected with fundamentals.
What are the limitations of the evidence supporting value investing returns?
The reported value premiums are gross, not net, so costs of periodically reforming value portfolios and shorting costs or constraints would reduce returns, making value even less attractive recently. The long-short strategies described are also beyond the reach of most investors, who pay fees for delegating to a fund manager. In addition, investors differ in how much underperformance they will tolerate before abandoning value.