
Do documented streaks of market outperformance occur more often than would be expected by chance, thereby supporting belief in investing skill? In their August 2010 paper entitled “Differentiating Skill and Luck in Financial Markets With Streaks”, Andrew Mauboussin and Samuel Arbesman compare actual streaks of mutual fund outperformance relative to the S&P 500 Index to results of 10,000 “no-skill” simulation trials to measure whether skill exists. The simulation assumes that both the number of fund-years per year and the probability that a fund would beat the S&P 500 Index during a year are the same as observed across a large sample of active mutual funds. Using monthly returns for 5,593 actively managed, large-capitalization U.S. mutual funds spanning 1962-2008 (50,693 fund-years), they find that:
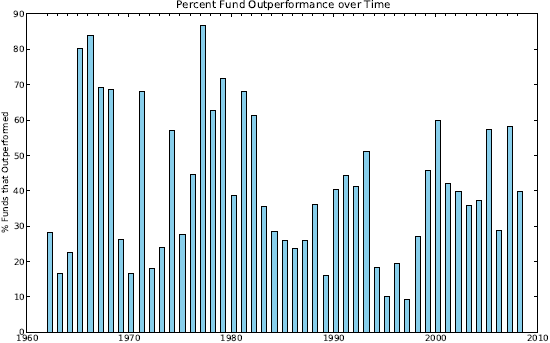
- Based on annual returns, sampled mutual funds beat the S&P 500 Index 38.2% of the time, with the frequency of outperformance varying considerably over time (see the first chart below).
- Over the entire sample there are 454 (3) outperformance streaks of at least five (ten) calendar years. The longest streak is 15 years.
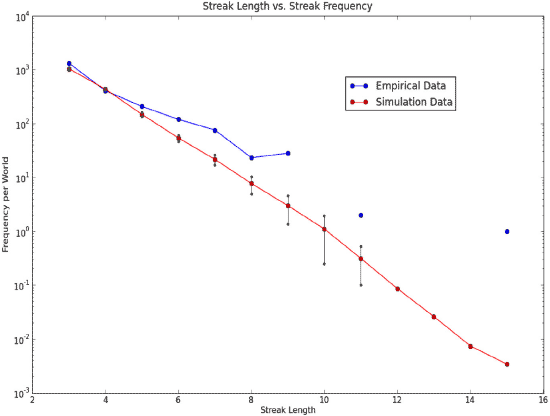
- Actual mutual fund performance exhibits significantly more streaks than generated by “no-skill” simulations (see the second chart below). Moreover, in aggregate, funds with outperformance streaks of at least seven years beat the S&P 500 Index 55.0% of the time, compared to 38.2% for all funds.
- Adding a skill component to the simulation based on a normal distribution of skill with a mean of 0% and a standard deviation of approximately 16% mimics empirical data.
- The empirical basis for the simulation, and the length of the longest outperformance streaks, make it unlikely that fund styles explain the indication of skill.
The following chart, taken from the paper, shows the frequency of outperformance by calendar year for all funds sampled. The average frequency of outperformance across all years is 38.2%. There is considerable variation in outperformance rates over the 1962-2008 sample period.
The next chart, also from the paper, compares the empirical and simulated frequencies of outperformance streaks (log scale) over the entire sample period, with one standard deviation variability ranges for simulation outcomes. It shows that outperformance streaks are systematically more prevalent in actual data than in 10,000 “no-skill” simulation trials. In other words, some factor other than pure luck is material in generating the distribution of outperformance streaks among mutual funds.
In summary, evidence from analysis of market outperformance streaks among actively managed U.S. mutual funds indicates that fund manager skill is material to fund performance.
The study does not address how to find outperformance streaks before they occur.
Frequently Asked Questions
What is an outperformance streak in mutual funds?
An outperformance streak in mutual funds is a run of consecutive calendar years in which a fund beats a benchmark such as the S&P 500 Index. In a study of 5,593 actively managed large-cap U.S. mutual funds (1962-2008), streaks were used to test whether manager skill exists rather than just luck. The sample contained 454 streaks of at least five years, and the longest lasted 15 years.
Do mutual fund outperformance streaks prove that fund managers have skill?
Mutual fund outperformance streaks suggest that manager skill is material, though they do not prove it with certainty. Actual funds from 1962-2008 produced significantly more streaks than 10,000 no-skill simulations, including 454 streaks of at least five years and 3 of at least ten years. Funds with streaks of at least seven years beat the S&P 500 Index 55.0% of the time, versus 38.2% for all funds.
How are Monte Carlo simulations used to separate skill from luck in mutual fund performance?
Monte Carlo simulations separate skill from luck by running 10,000 no-skill trials and comparing the resulting streak frequencies to actual fund data. The simulations assume the number of fund-years per year and the annual probability of beating the S&P 500 Index match those observed in the sample of 5,593 funds. Adding a skill component, normally distributed with a 0% mean and roughly 16% standard deviation, produces results that mimic the empirical data.
Could fund investment style explain mutual fund outperformance streaks instead of skill?
Fund investment style is unlikely to explain mutual fund outperformance streaks, according to the study's authors. The simulation is built on empirical outperformance rates, and the length of the longest streaks (up to 15 years) makes a style-based explanation improbable. Across 1962-2008, funds beat the S&P 500 Index in only 38.2% of fund-years, with considerable variation by calendar year.
What are the limitations of using outperformance streaks to identify skilled mutual fund managers?
Outperformance streaks have a key limitation: the study does not address how to identify streaks before they occur, so it offers no way to select future winners in advance. The evidence also covers only actively managed, large-cap U.S. mutual funds from 1962-2008, benchmarked against the S&P 500 Index. The finding indicates that skill is material in aggregate, not which specific managers are skilled.