
Is there information useful to investors in the “yield curves” of commodity futures? In their December 2009 paper entitled “Structural Properties of Commodity Futures Term Structures and Their Implications for Basic Trading Strategies”, Rolf Duerr and Matthias Voegeli investigate the informativeness of price progressions across commodity futures contracts with different maturities (term structures or yield curves) over rolling 12-month windows. Specifically, they focus on trading commodity futures contracts based on the current slopes of these curves and on the stabilities of the shapes of the curves over time (slope and curvature). Using weekly closing settlement prices for 23 energy, metals, agriculture and livestock commodities spanning January 1998 through July 2009, they find that:
- Over the entire sample period, term structures are on average:
- Upward sloping ( in contango) for aluminum, gold, silver, wheat, Kansas wheat, corn, cotton, coffee and cocoa).
- Downward sloping (in backwardation) for copper, lead, nickel, zinc and soybeans.
- Flat for energy, sugar and livestock.
- Investment strategies which exploit the following three aspects of information about individual commodity roll yields consistently outperform a long-only benchmark during January 2001 through July 2009 (see the charts below):
- Contango versus backwardation.
- Current variation in yield curve steepness with duration.
- Yield curve stability over the prior three years (persistent slope and curvature).
The following charts, taken from the paper, summarize cumulative gross returns for commodity roll return strategies based on the above three aspects of information from commodity yield curves. To test the value of information about contango versus backwardation and current yield curve slope variation:
- The Directional 1 (long-only) strategy buys the contracts of commodities in contango (backwardation) for which slopes on the respective current yield curves are smallest (largest) in magnitude.
- The Directional 2 (long-short) strategy sells (buys) the contracts of commodities in contango (backwardation) for which the slopes on the respective current yield curves are largest in magnitude.
- The benchmark strategy buys and holds the front contracts for all 23 commodities until expiration, iteratively rolling to the next contract.
To test the value of information about lagged stability of commodity yield curves:
- Portfolio 1 weights equally the 12 commodities with the most stable yield curves over the prior three years, reformed every three years.
- Portfolio 2 weights equally the 11 commodities with the least stable yield curves over the prior three years, reformed every three years.
Results indicate that both the Directional 1 and 2 strategies, when implemented via Portfolio 1 (2), consistently outperform (do not consistently outperform) the benchmark, suggesting that commodity yield curve lagged stability is informative.
Results ignore transaction costs since the Directional 1 and 2 strategies have the same number of roll dates per contract as the benchmark and therefore comparable transaction costs.
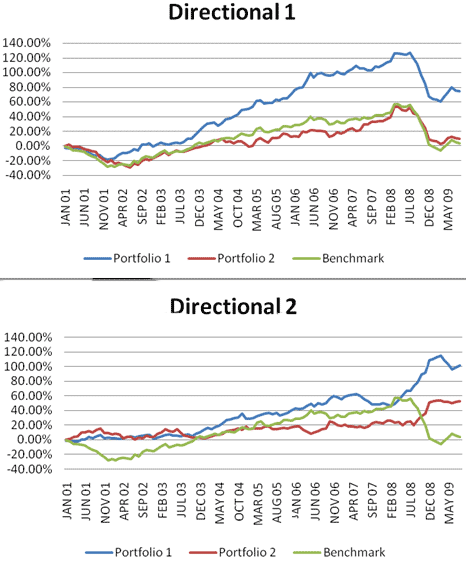
In summary, commodity traders may be able to enhance roll returns by focusing on those commodities for which term structures (yield curves) exhibit stability over recent years.
Frequently Asked Questions
What is a commodity futures yield curve and what does contango versus backwardation mean?
A commodity futures yield curve (term structure) is the pattern of futures prices across contracts with different maturities. The curve is in contango when it slopes upward and in backwardation when it slopes downward. In the study, aluminum, gold, silver, wheat, corn, cotton, coffee and cocoa were on average in contango, while copper, lead, nickel, zinc and soybeans were on average in backwardation.
Can commodity yield curve slope and stability be used to beat a long-only commodity benchmark?
Yes, strategies using commodity yield curve information consistently outperformed a long-only front-contract benchmark during January 2001 through July 2009, on a gross-return basis. The strategies exploited contango versus backwardation, current slope steepness, and yield curve stability over the prior three years. The outperformance held for the directional strategies applied to the most stable curves, but not consistently for the least stable ones.
How are commodity roll return strategies based on yield curve slope and stability constructed and tested?
The study used weekly settlement prices for 23 energy, metals, agriculture and livestock commodities (January 1998 to July 2009). Directional 1 is long-only, buying contango (backwardation) commodities with the smallest (largest) slopes, while Directional 2 is long-short, selling (buying) those with the largest slopes. Stability was tested by splitting commodities into Portfolio 1 (12 most stable curves over the prior three years) and Portfolio 2 (11 least stable), reformed every three years, and all were compared to a benchmark that holds and rolls front contracts.
How do stable-curve commodity portfolios compare with unstable-curve portfolios and a buy-and-hold front-contract benchmark?
Portfolio 1, holding the 12 commodities with the most stable yield curves over the prior three years, consistently outperformed the benchmark of buying and rolling front contracts in both directional strategies. Portfolio 2, holding the 11 least stable commodities, did not consistently outperform. This suggests that lagged yield curve stability is informative for enhancing roll returns.
What are the limitations of trading commodity futures based on yield curve information?
The reported results are gross returns that ignore transaction costs, which the study argues are comparable to the benchmark because the strategies have the same number of roll dates per contract. The evidence covers a single sample of 23 commodities over January 2001 through July 2009, and outperformance was not consistent for commodities with unstable yield curves. The conclusion that traders may enhance roll returns by focusing on stable-curve commodities is therefore limited to this period and approach.