
An investor can collar (bound) a long position in an asset by simultaneously purchasing a put option at one strike price (lower bound) and selling a call option at a higher strike price (upper bound) on the asset. How does this strategy perform? In the September 2009 version of their paper entitled “Loosening Your Collar: Alternative Implementations of QQQ Collars”, Edward Szado and Thomas Schneeweis evaluate the performances of passive and active collar strategies for the PowerShares QQQ (QQQQ) Exchange-Traded Fund (ETF) and for a small cap equity mutual fund. While a standard collar employs put and call options with the same expiration date, the study also considers puts with longer durations. The passive collar strategy follows a fixed set of rules regardless of market conditions. The active strategy varies collar specifications according to three market/economic conditions: (1) momentum of the underlying; (2) broad market volatility; and, (3) a macroeconomic measure combining unemployment and the business cycle. Using data covering the period from the introduction of QQQQ options on March 19, 1999 through May 31, 2009 (122 months), they conclude that:
- A passive collar outperforms (underperforms) QQQQ in the two bearish subperiods (one bullish subperiod) of the overall sample based on gross returns. Passive collar returns have lower volatilities than QQQQ returns during all three subperiods.
- The active collar strategy tends to outperform the passive collar.
- Results from collaring a small capitalization mutual fund with QQQQ options are similar to those from collaring QQQQ itself.
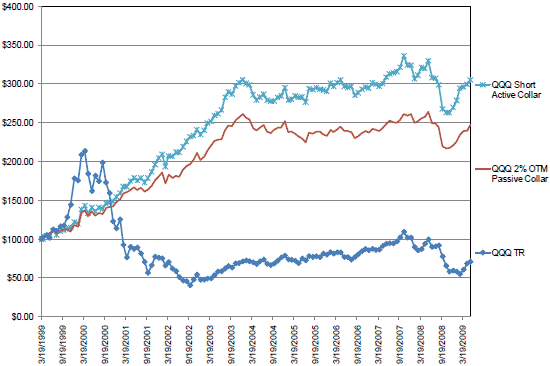
The following chart, taken from the paper, compares the gross cumulative values of $100 initial investments in QQQQ, a passive collar strategy for QQQQ and an active collar strategy for QQQQ over the entire sample period. Collar definitions/assumptions are as follows:
The passive collar strategy employs calls sold 2% out-of-the-money (OTM) with one month to expiration and puts bought 2% OTM with six months to expiration. At the close on each expiration Friday, the strategy settles the calls at intrinsic value and sells new 1-month calls, while holding the longer term put. The strategy invests the net proceeds from rolling the 1-month calls, rebalancing to maintain a 1:1:1 ratio of QQQQ, puts and calls. The strategy settles the 6-month puts at intrinsic value when they expire and buys new 6-month puts. To account for the bid-ask spread, all puts purchased (calls sold) are at the ask (bid).
The active collar strategy adjusts the collar according to momentum, volatility and economic conditions. Momentum specifies widening or tightening the collar by increasing or decreasing initial percent OTM. Volatility specifies increasing or decreasing the number of calls written per QQQQ and put. The economic signal specifies an upward or downward shift in the collar by increasing percent OTM of the calls and decreasing percent OTM of the puts, or vice versa.
The chart shows that both collar strategies outperform buying and holding QQQQ over the entire sample period, with most of the outperformance coming during the 2000-2002 bear market. The active strategy generally outperforms the passive strategy. Both collar strategies underperform QQQQ during the 2003-2007 bull market.
The paper offers more complete explanations of trading rules and results for different levels of initial moneyness and different initial put durations.
In summary, evidence indicates that option collars may substantially improve the performance of ETFs and mutual funds over fairly long periods that include bear markets.
Cautions regarding findings include:
- As indicated, the sample period arguably entails a “lucky start” for index collar strategies.
- Reported performances are gross, not net. Including reasonable trading frictions, which are generally material for options, would reduce returns for modeled strategies.
- The active collar strategy involves multiple parameter settings and may impound substantial data snooping bias.
Frequently Asked Questions
What is an options collar strategy and how does it limit risk on a stock or ETF?
An options collar bounds a long position in an asset by simultaneously buying a put option at a lower strike price and selling a call option at a higher strike price. The put sets a floor on losses, while the call caps gains. A passive collar follows fixed rules regardless of market conditions, whereas an active collar varies its specifications with market and economic conditions.
Do collar strategies outperform buying and holding the QQQ ETF?
Collar strategies outperformed buy-and-hold QQQQ over the full March 1999 to May 2009 sample (122 months, gross returns), mostly during the 2000-2002 bear market. A passive collar outperformed QQQQ in the two bearish subperiods but underperformed in the bullish one, and had lower volatility in all three subperiods. The active collar generally beat the passive collar.
How is a passive or active QQQ collar built and rebalanced?
The passive QQQQ collar sells 1-month calls 2% out-of-the-money and buys 6-month puts 2% out-of-the-money, keeping a 1:1:1 ratio of QQQQ, puts and calls. On each expiration Friday, calls are settled at intrinsic value and new 1-month calls are sold, while 6-month puts are held until expiry and then replaced. Puts are bought at the ask and calls sold at the bid. The active collar adjusts the strikes and number of calls using three signals: momentum of the underlying, broad market volatility, and a macroeconomic measure combining unemployment and the business cycle.
How does an active collar compare to a passive collar, and does it work for mutual funds too?
An active collar tends to outperform a passive collar because it adjusts strikes and call quantities for momentum, volatility and economic conditions rather than following fixed rules. Both collars lag QQQQ in the 2003-2007 bull market, but both beat it over the full period. Collaring a small capitalization equity mutual fund with QQQQ options produced results similar to collaring QQQQ itself.
What are the limitations and risks of backtested collar strategy results?
The collar results are gross returns, so realistic trading frictions, which are generally material for options, would reduce performance. The 1999-2009 sample period arguably gives index collar strategies a "lucky start" because it includes major bear markets. The active collar uses multiple parameter settings and may carry substantial data snooping bias.