
Does widespread investor acceptance of the capital asset pricing model (CAPM) of stock returns drive undervaluation of stocks with low past alphas? In his February 2019 paper entitled “The Unintended Impact of Academic Research on Asset Returns: The CAPM Alpha”, Alex Horenstein examines whether such acceptance distorts the U.S. stock market. Specifically, he each year at the beginning of January reforms a betting against alpha (BAA) hedge portfolio that is long (short) stocks with alphas lower (higher) than the median based on monthly returns over the past five years. He then weights stocks according to their respective alpha ranks, rescales the long and short sides separately to have market beta 1.0 and holds for one year. He analyzes performance of this portfolio and eight widely accepted equity factors (size, value, momentum, profitability, investment, short-term reversal, long-term reversion and betting against beta) during three subperiods: (1) pre-CAPM era (1932-1964); (2) CAPM era (1965-1992); and, (3) smart beta era (1993-2015). Using total returns for a broad sample of U.S. common stocks and returns for eight accepted equity factors during January 1927 through December 2015, he finds that:
- The BAA hedge portfolio delivers -0.04% gross monthly CAPM alpha during the pre-CAPM era, 0.54% during the CAPM era and 0.88% during the smart beta era. Regarding CAPM alphas of other factors:
- During the pre-CAPM era, size, value and long-term reversion factors perform poorly. Momentum, short-term reversal (especially) and betting against beta perform well.
- During the CAPM era, momentum, short-term reversal and betting against beta continue to perform well. Value also performs well, with size and long-term reversion relatively weak.
- During the smart beta era, momentum and betting against beta (especially) continue to perform well, but all other factors are relatively weak.
- This BAA performance evolution is present but weaker for a sample restricted to NYSE stocks.
- The growing CAPM alpha of BAA comes predominantly from the low alpha side, which contains stocks neglected by fund managers (see the chart below).
- Low-alpha and high-alpha sides of the BAA portfolio have volatilities similarly greater than average and are therefore sensitive to market liquidity shocks. Sensitivity of the low-alpha side is twice that of the high-alpha side.
- The publication rate of new CAPM-related academic work parallels acceleration of BAA performance, increasing steadily during the CAPM era and much faster during the smart beta era.
The following chart, taken from the paper, tracks cumulative excess returns (relative to the risk-free rate) of the short and long sides of BAA separately for the full sample of stocks across the three eras. Results show that BAA return comes mostly from the long (low-alpha) side, becoming substantial only after the introduction of CAPM in the mid-1960s.
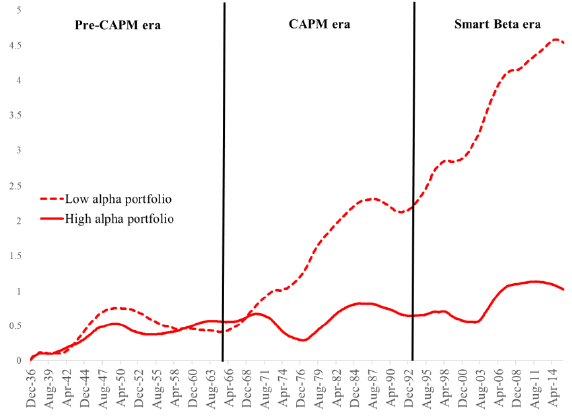
In summary, evidence suggests that academic research on CAPM has created an attractive betting against alpha anomaly and perturbed anomalies correlated with the overall market.
Cautions regarding findings include:
- Findings are gross, not net. Accounting for annual BAA portfolio reformation and costs of continuously shorting high-alpha stocks would reduce performance. Shorting of some stocks as specified may be costly/impractical due to lack of shares to borrow.
- Similarly, returns for other factors are gross and involve varying levels of portfolio reformation frictions and shorting costs.
- In particular, BAA and betting against beta portfolio formation process is unconventional and complicated. See “Back Doors in Betting Against Beta?” for a critique of the approach, arguing that it creates portfolios with close to equal weighting (especially difficult/costly-to-implement).
- Allowing one day for collection/processing of final data for BAA portfolio reformation is optimistic for much of the sample period.
See also the closely related “Just Bet Against Everything?”.
Frequently Asked Questions
What is a betting against alpha strategy in investing?
A betting against alpha (BAA) strategy is a hedge portfolio that goes long stocks with low past CAPM alphas and shorts stocks with high past CAPM alphas. Alpha is estimated from monthly returns over the past five years. The long and short sides are each rescaled to a market beta of 1.0, so the portfolio is designed to be market neutral.
Does widespread acceptance of the CAPM create a betting against alpha anomaly in stock returns?
Evidence in the study suggests that academic acceptance of the CAPM created a betting against alpha anomaly in U.S. stocks. The BAA portfolio's gross monthly CAPM alpha rose from -0.04% in the pre-CAPM era (1932–1964) to 0.54% in the CAPM era (1965–1992) and 0.88% in the smart beta era (1993–2015). The effect is present but weaker in a sample restricted to NYSE stocks.
How is a betting against alpha portfolio constructed and tested across different eras?
Each January, stocks are ranked on CAPM alpha from the prior five years of monthly returns. The portfolio goes long stocks with below-median alpha and short those with above-median alpha, weights them by alpha rank, rescales each side to beta 1.0 and holds for one year. Performance is tested on broad U.S. common stocks from January 1927 to December 2015, split into pre-CAPM (1932–1964), CAPM (1965–1992) and smart beta (1993–2015) eras, and compared with eight accepted equity factors.
How does betting against alpha compare with other equity factors like momentum, value and betting against beta?
Betting against alpha strengthened steadily across eras, while other factors were more mixed. In the smart beta era (1993–2015), momentum and betting against beta continued to perform well, but size, value, profitability, investment, short-term reversal and long-term reversion were relatively weak. In the study, BAA's gains came mostly from the long, low-alpha side, which holds stocks neglected by fund managers.
What are the limitations and implementation risks of a betting against alpha strategy?
The reported BAA results are gross, not net, so annual portfolio reformation and the cost of continuously shorting high-alpha stocks would reduce performance. Some shorts may be impractical because shares are hard to borrow. The portfolio construction is also unconventional and complicated, and critics argue it produces near equal-weighted portfolios that are costly to implement. Allowing only one day to process final data for reformation is optimistic for much of the sample period.