
Is there some better predictor of long-term stock market return than the widely cited cyclically adjusted price-earnings ratio (P/E10 or CAPE)? In the July 2014 version of his paper entitled “Forecasting Equity Returns: An Analysis of Macro vs. Micro Earnings and an Introduction of a Composite Valuation Model”, Stephen Jones compares how well several fundamental and economic factors predict real long-term (10-year) equity market total return, with focus on Market Value/Gross Domestic Product (MV/GDP). He compares the predictive power of MV/GDP to those of P/E10 and Tobin’s q. He then constructs a multi-variable forecasting model that includes MV/GDP, a demographic metric and personal income-related variables. Using U.S. data since 1954 for different input variables, he finds that:
- MV/GDP is theoretically and, over the available sample period, empirically better than P/E10 for predicting in-sample real long-term equity market return.
- Valuation methods for individual firms do not make economic sense when aggregated across all firms.
- A linear relationship between MV/GDP (P/E10) and real 10-year future stock market return has an in-sample R-squared statistic of 0.52 (0.38), meaning that MV/GDP (P/E10) explains 52% (38%) of the variation in future return.
- The number of years used in P/E10 is arbitrary. Increasing the number of years (X) in P/EX increases its in-sample effectiveness towards that of MV/GDP.
- Unlike GDP, the denominator of P/E10 ratio does not distinguish between sustainable and unsustainable aggregate earnings. Aggregate earnings/GDP has generally risen over the sample period, driven by unsustainable increases in government and personal debt. For example, this ratio has an annual average of 17.5% over the past decade, 13.6% during the 1990s, 13.2% over the 1980s, 12.9% over the 1970s, 12.1% over the 1960s and 10.9% over the 1950s.
- Constructing a composite model of real 10-year stock market return involves:
- Combining MV/GDP with a demographic variable related to investment and consumption (optimally the ratio of the age 55-64 population to the age 35-44 population) to produce an in-sample adjusted R-squared of 0.86.
- Adding to this combination two economic growth potential indicators, personal income/book value and change in personal consumption/personal income, to boost predictive power further.
- Finally adding historical GDP growth as a predictive variable to create a composite model with an in-sample adjusted R-squared of 0.91, compared to 0.52 for MV/GDP alone, 0.49 for Tobin’s q alone and 0.38 for P/E10 alone.
- Out-of-sample tests since December 1972 confirm that MV/GDP is the best individual predictor of real 10-year equity market return and that the composite model is far superior to any individual predictor.
- Based on data as of 7/3/2014 (S&P 500 Index at 1985), with the assumption that dividends offset inflation, the composite model projects an annualized real return of -10.5% over the next decade and an index near 650 in 2024.
The following chart, taken from the paper, compares the S&P 500 Index actual annualized real 10-year total return (Actual) to the in-sample forecasts generated by P/E10, MV/GDP and Tobin’s q individually and by the composite model described above. The composite model clearly has the lowest in-sample tracking error. The average annualized real 10-year total return projected by the composite model ranges from -10.2% to 15.1%, with average 4.5%. The current projection (as of early July 2014) is the most bearish ever.
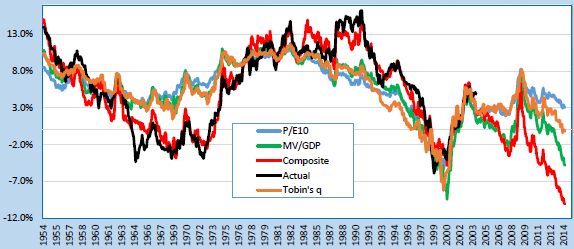
In summary, evidence from a U.S. stock market valuation model that encompasses sustainable growth, demographics and consumer potential indicates that the market is extremely overvalued as of July 2014.
Cautions regarding findings include:
- Even though comprised of many years, samples are short relative to a ten-year return measurement interval and a 12-year demographic cohort measurement interval.
- As noted, much of the analysis is in-sample, with associated look-ahead bias.
- Applying different models to the same data in search of the best one incorporates a form of snooping bias (luck), such that the historical accuracy of the best model likely overstates its expected predictive power. Snooping bias can be large when applied to effectively small samples.
- Snooping of the optimal demographic cohorts incorporates additional bias.
- Statistics do not correct for overlap of annual measurement of multi-year variables, which tends to inflate correlation.
- Historical economic data may not be completely stable due to retroactive revisions (as-released data may be different from curated historical series).
Frequently Asked Questions
What is the MV/GDP ratio and how is it used in stock market valuation?
The MV/GDP ratio is the total market value of equities divided by gross domestic product, used as an aggregate (macro) measure of stock market valuation. In Stephen Jones's July 2014 paper, MV/GDP is used to forecast real 10-year equity market total return using U.S. data since 1954. He argues it is better suited to the whole market than valuation methods designed for individual firms.
Does MV/GDP predict long-term stock market returns better than P/E10 or CAPE?
MV/GDP predicted real 10-year U.S. equity market return better than P/E10 in Jones's analysis, with an in-sample R-squared of 0.52 versus 0.38 for P/E10 and 0.49 for Tobin's q. Out-of-sample tests since December 1972 also found MV/GDP the best individual predictor. A composite model adding demographics, personal income variables and historical GDP growth reached an in-sample adjusted R-squared of 0.91.
How is a composite stock market valuation model built to forecast 10-year returns?
Jones's composite model forecasts real 10-year stock market return by combining MV/GDP with a demographic variable, optimally the ratio of the age 55-64 population to the age 35-44 population, giving an in-sample adjusted R-squared of 0.86. He then adds two economic growth indicators (personal income/book value and change in personal consumption/personal income) and historical GDP growth, raising adjusted R-squared to 0.91. As of 7/3/2014, with the S&P 500 at 1985 and dividends assumed to offset inflation, the model projected an annualized real return of -10.5% over the next decade.
Why might MV/GDP be a better valuation measure than P/E10 for the whole stock market?
MV/GDP may be better than P/E10 because, per Jones, firm-level valuation methods do not make economic sense when aggregated across all firms, and the P/E10 denominator (earnings) does not distinguish sustainable from unsustainable aggregate earnings. Aggregate earnings/GDP rose from 10.9% in the 1950s to an average of 17.5% over the past decade, driven by unsustainable increases in government and personal debt. The number of years in P/E10 is also arbitrary, and increasing it toward P/EX with a larger X moves its in-sample effectiveness closer to MV/GDP.
What are the limitations and biases of the composite stock market valuation model?
The composite valuation model's high R-squared likely overstates its true predictive power because most analysis is in-sample (look-ahead bias) and testing many models and demographic cohorts on the same data adds snooping bias. The samples are short relative to the 10-year return and 12-year demographic cohort measurement intervals, and statistics do not correct for overlapping annual observations of multi-year variables, which inflates correlation. Historical economic data may also differ from as-released figures because of retroactive revisions.