
Are stocks so attractive over the long run that they crowd bonds and cash out of the optimal portfolio? In their September 2013 paper entitled “Optimal Portfolios for the Long Run”, David Blanchett, Michael Finke and Wade Pfau relate optimal portfolio equity allocation to investment horizon worldwide to determine whether stocks universally exhibit time diversification (whereby mean reversion of returns causes equity risk to decrease as investment horizon lengthens). In calculating optimal equity allocation, they employ a utility function to model how investors feel about the risk of good and bad outcomes (not volatility as measured by standard deviation of returns). They consider different levels of investor risk aversion on a scale of 1 to 20, with 20 extremely risk averse. They measure returns for both overlapping and independent investment intervals of 1 to 20 years. They constrain portfolios to long-only positions in three assets: government bills (cash), government bonds and stock indexes. Using annual real returns to local investors in bills, bonds and stock indexes for 20 countries during 1900 through 2012, they find that:
- In general across countries and levels of investor risk aversion, the longer the investment horizon, the higher the optimal allocation to equities (see the charts below). Specifically, based on overlapping return intervals, the optimal equity allocation across the 20 countries increases as investment horizon lengthens by an average:
- 1.3% per year for low risk aversion (2).
- 2.1% per year for moderate risk aversion (4).
- 2.5% per year for high risk aversion (8).
- 2.7% per year for very high risk aversion (16).
- A modest tendency for two-year mean reversion in stock index returns is a key reason why equity risk falls as investment horizon lengthens (time diversifies equities).
- The value of time diversification for equities increases during the 20th century, despite a declining equity risk premium.
- As long as the equity risk premium is positive, there is some time diversification value.
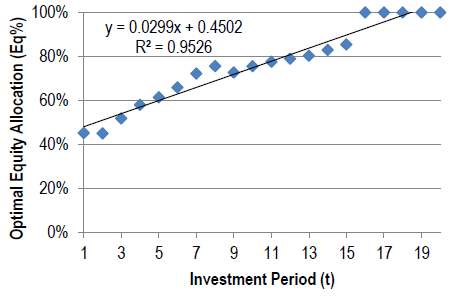
The following chart, taken from the paper, shows the relationship between optimal portfolio equity allocation and investment horizon (Investment Period) for moderately risk averse U.S. investors (risk aversion level 4). Return calculations involve overlapping investment intervals. The best-fit line has a positive slope, indicating that the allocation to stocks should increase as investment horizon lengthens. Raw calculations indicate that the optimal allocation to equities is 100% for investment horizons longer than 15 years.
Across 20 countries and risk aversion levels 2, 4, 8 and 16, similar analyses generate positive slopes (time diversification) for over 90% of scenarios.
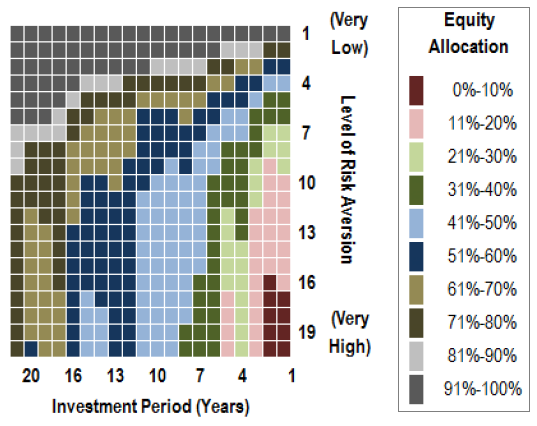
The next chart, also from the paper, summarizes optimal equity allocations for U.S. investors across levels of risk aversion from 1 to 20 and investment horizons of 1 to 20 years (400 scenarios) for overlapping return intervals. The optimal equity allocation increases as investment horizon lengthens and decreases as risk aversion increases.
Optimal U.S. equity allocations are similar to 20-country averages.
In summary, evidence generally supports belief in time diversification of equities, such that the optimal portfolio allocation to stocks increases as investment horizon lengthens.
Cautions regarding findings include:
- Even a 113-year sample has only about 5.6 independent 20-year investment intervals. The sample is especially short for analysis of any trend in time diversification value.
- The study uses stock indexes, not accounting for the costs of creating and maintaining tradable assets to track them. Incorporating these costs could affect findings.
- The study does not account for the costs of implied annual rebalancing of portfolio components to target weights.
See also “Long-term Investors: Focus on Terminal Wealth?”.
Frequently Asked Questions
What is time diversification of stocks?
Time diversification of stocks is the idea that mean reversion of returns causes equity risk to decrease as the investment horizon lengthens. If it holds, longer-horizon investors should rationally hold more equities. A modest tendency toward two-year mean reversion in stock index returns is a key reason it appears in the data.
Does a longer investment horizon increase the optimal allocation to stocks?
Yes, the optimal allocation to stocks generally rises as the investment horizon lengthens, across countries and risk aversion levels. Using 20 countries from 1900 through 2012, optimal equity allocation increased by an average of 1.3% per year of horizon for low risk aversion and 2.7% for very high risk aversion. Over 90% of scenarios showed a positive slope, and raw U.S. calculations for moderate risk aversion indicated 100% equities for horizons beyond 15 years.
How is the optimal equity allocation for a given investment horizon calculated?
The optimal equity allocation is calculated by using a utility function that models how investors feel about good and bad outcomes, rather than volatility measured by standard deviation. The study applied risk aversion levels from 1 to 20 to annual real returns on government bills, government bonds and stock indexes for 20 countries during 1900-2012, with long-only positions. Returns were measured over overlapping and independent investment intervals of 1 to 20 years.
How does optimal stock allocation differ between more and less risk-averse investors?
Optimal stock allocation decreases as investor risk aversion increases, but the horizon effect is stronger for more risk-averse investors. Based on overlapping intervals, optimal equity allocation rises by an average of 1.3% per year of horizon at risk aversion 2, 2.1% at level 4, 2.5% at level 8 and 2.7% at level 16. U.S. results across risk aversion levels 1 to 20 and horizons of 1 to 20 years are similar to the 20-country averages.
What are the limitations of the evidence for time diversification of equities?
The evidence for time diversification of equities is limited by sample length, since even 113 years of data contain only about 5.6 independent 20-year intervals, which is especially short for analyzing trends in time diversification value. The study also uses stock indexes without accounting for the costs of creating and maintaining tradable assets that track them. It also ignores the costs of the annual rebalancing implied by target portfolio weights, and incorporating these costs could affect the findings.