
“SACEMS-SACEVS for Value-Momentum Diversification” finds that the “Simple Asset Class ETF Value Strategy” (SACEVS) and the “Simple Asset Class ETF Momentum Strategy” (SACEMS) are mutually diversifying. Do longer samples available from “SACEVS Applied to Mutual Funds” and “SACEMS Applied to Mutual Funds” confirm this finding? To check, we look at the following three equal-weighted (50-50) combinations of the two strategies, rebalanced monthly:
- SACEVS Best Value paired with SACEMS Top 1 (aggressive value and aggressive momentum).
- SACEVS Best Value paired with SACEMS Equally Weighted (EW) Top 3 (aggressive value and diversified momentum).
- SACEVS Weighted paired with SACEMS EW Top 3 (diversified value and diversified momentum).
Using monthly gross returns for SACEVS and SACEMS mutual fund portfolios during September 1997 through July 2019, we find that:
First, we look at SACEVS Best Value-SACEMS Top 1, aggressive value and aggressive momentum. The correlation of monthly returns between these strategies over the available sample period is 0.10, indicating that they substantially diversify each other.
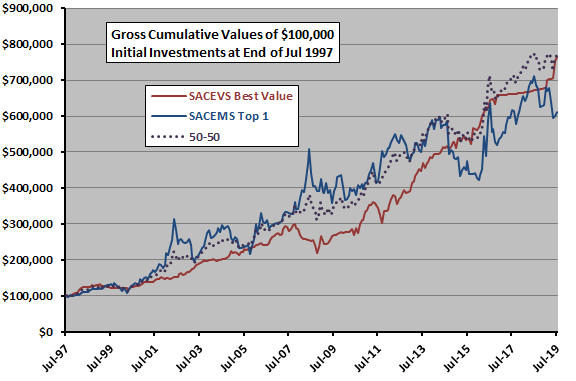
The following chart plots gross cumulative values of $100,000 initial investments in each of SACEVS Best Value, SACEMS Top 1 and 50-50 over the available sample period. Visual inspection suggests that 50-50 is attractively smooth. Quantitatively:
- Average gross monthly returns (standard deviations of monthly returns) for SACEVS Best Value, SACEMS Top 1 and 50-50 are 0.8% (2.7%), 0.9% (5.7%) and 0.8% (3.3%), respectively, translating to rough monthly Sharpe ratios of 0.30, 0.15 and 0.26.
- Compound annual growth rates (CAGR) are 10.8%, 9.8% and 10.9%, respectively.
- Maximum drawdowns (MaxDD) based on monthly data are -27%, -37% and -19%, respectively.
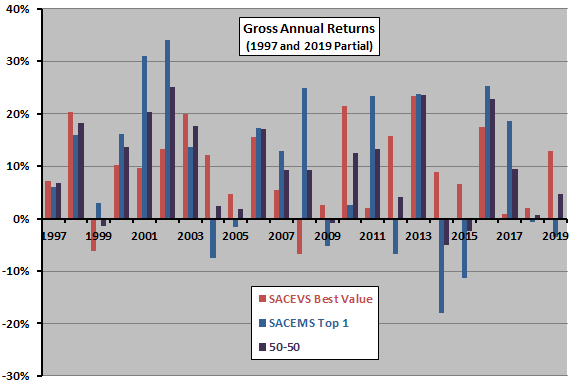
For another perspective, we look at calendar year returns.
The next chart summarizes gross annual returns for SACEVS Best Value, SACEMS Top 1 and 50-50 during 1997 through 2019, with 1997 and 2019 partial. Average annual returns (standard deviations of annual returns) for full years 1998 through 2018 are 9.5% (8.7%), 10.1% (15.0%) and 10.1% (9.4%), respectively. Using average monthly yield on 3-month Treasury bills (T-bill) during a year as the risk-free rate for that year, corresponding gross annual Sharpe ratios are 0.83, 0.56 and 0.87. The 50-50 strategy has negative returns in 2014 and 2015.
Next, we look at SACEVS Best Value-SACEMS EW Top 3, aggressive value and cautious momentum.
The correlation of monthly returns between SACEVS Best Value and SACEMS EW Top 3 over the available sample period is 0.36, indicating that they materially diversify each other.
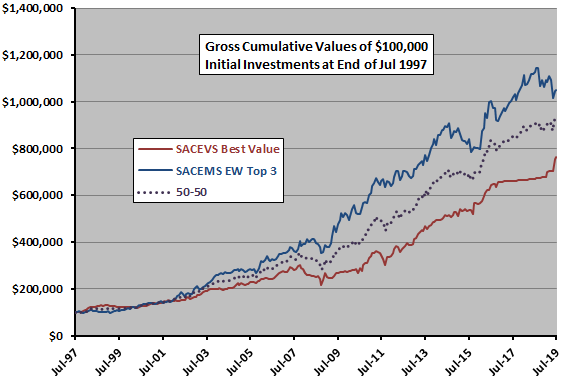
The following chart plots gross cumulative values of $100,000 initial investments in SACEVS Best Value, SACEMS EW Top 3 and 50-50 over the available sample period. Visual inspection suggests that 50-50 is attractively smooth. Quantitatively:
- Average gross monthly returns (standard deviations of monthly returns) for SACEVS Best Value, SACEMS EW Top 3 and 50-50 are 0.8% (2.7%), 1.0% (3.4%) and 0.9% (2.5%), respectively, translating to rough monthly Sharpe ratios of 0.30, 0.28 and 0.35.
- CAGRs are 10.8%, 12.6% and 11.9%, respectively.
- MaxDDs based on monthly data are -27%, -15% and -20%, respectively.
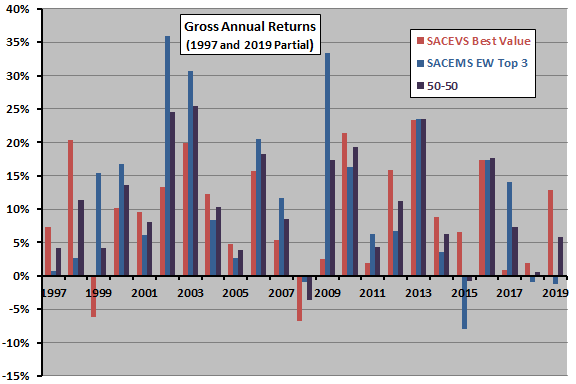
For another perspective, we look at calendar year returns.
The next chart summarizes gross annual returns for each of SACEVS Best Value, SACEMS EW Top 3 and 50-50 over the available sample period, with 1997 and 2019 partial. Average annual returns (standard deviations of annual returns) for full years 1998 through 2018 are 9.5% (8.7%), 12.5% (11.7%) and 11.0% (8.4%), respectively. Using average monthly T-bill yield during a year as the risk-free rate for that year, corresponding gross annual Sharpe ratios are 0.83, 0.88 and 1.04. The 50-50 strategy has negative returns in 2008 and 2015.
Finally, we look at SACEVS Weighted-SACEMS EW Top 3, cautious value and cautious momentum.
The correlation of monthly returns between SACEVS Weighted and SACEMS EW Top 3 over the available sample period is 0.43, indicating that they materially diversify each other.
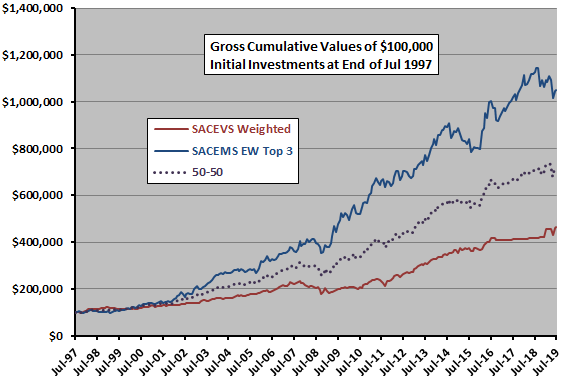
The following chart plots gross cumulative values of $100,000 investments in each of SACEVS Weighted, SACEMS EW Top 3 and 50-50 over the available sample period. Visual inspection suggests that 50-50 is attractively smooth. Quantitatively:
- Average gross monthly returns (standard deviations of monthly returns) for SACEVS Weighted, SACEMS EW Top 3 and 50-50 are 0.6% (2.4%), 1.0% (3.4%) and 0.8% (2.4%), respectively, translating to rough monthly Sharpe ratios 0.26, 0.28 and 0.32.
- CAGRs are 8.0%, 12.6% and 10.5%, respectively.
- MaxDDs based on monthly data are -24%, -15% and -18%, respectively.
For another perspective, we look at calendar year returns.
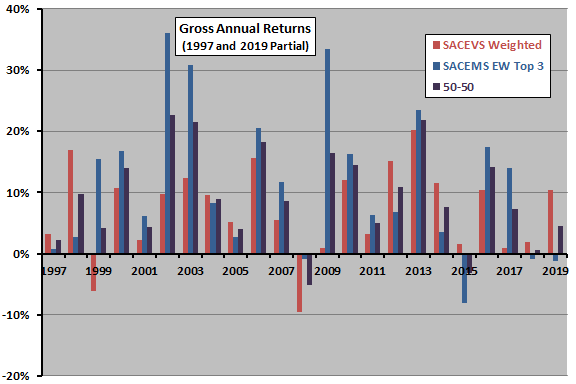
The final chart summarizes gross annual returns for SACEVS Weighted, SACEMS EW Top 3 and 50-50 over the available sample period, with 1997 and 2019 partial. Average annual returns (standard deviations of annual returns) for full years 1998 through 2018 are 7.2% (7.6%), 12.5% (11.7%) and 9.8% (7.8%), respectively. Using average monthly T-bill yield during a year as the risk-free rate for that year, corresponding gross annual Sharpe ratios are 0.67, 0.88 and 0.97. The 50-50 strategy has negative returns in 2008 and 2015.
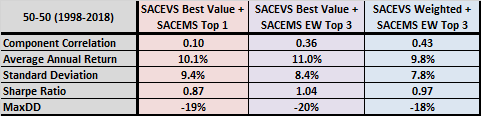
The following table summarizes key gross annual performance statistics for the SACEVS-SACEMS diversified portfolios over the available full-year sample period. Results suggest the aggressive value and cautious momentum alternative is preferable.
In summary, evidence from the available sample period suggests that SACEMS and SACEVS as applied to mutual funds usefully diversify each other.
Cautions regarding findings include:
- Analyses ignore any costs/constraints (mutual fund loads and penalties for early withdrawals) associated with the base strategies and with rebalancing the 50-50 combination each month. Constraints may be stronger for diversified versions of SACEVS and SACEMS pair than for the aggressive versions.
- Available sample periods are modest for analysis of annual returns.
- Cautions outlined in “SACEVS Applied to Mutual Funds” and “SACEMS Applied to Mutual Funds” also apply.
Frequently Asked Questions
What are the Simple Asset Class ETF Value Strategy (SACEVS) and Momentum Strategy (SACEMS)?
The Simple Asset Class ETF Value Strategy (SACEVS) and Simple Asset Class ETF Momentum Strategy (SACEMS) are two asset class allocation strategies, one based on value and the other on momentum. In this analysis they are applied to mutual funds rather than ETFs to allow longer sample periods. The article variants include SACEVS Best Value and Weighted, and SACEMS Top 1 and Equally Weighted (EW) Top 3.
Do value and momentum asset class strategies diversify each other when applied to mutual funds?
Yes, SACEVS and SACEMS applied to mutual funds usefully diversify each other over September 1997 through July 2019. Monthly return correlations for the three 50-50 combinations are 0.10, 0.36 and 0.43. The combination of SACEVS Best Value with SACEMS EW Top 3 looked preferable, with a CAGR of 11.9%, a maximum drawdown of -20% and a gross annual Sharpe ratio of 1.04.
How do you test a 50-50 combination of a value strategy and a momentum strategy?
The 50-50 combinations of SACEVS and SACEMS were tested by equally weighting the two strategies and rebalancing monthly, using gross monthly mutual fund returns from September 1997 through July 2019. Three pairings were examined: Best Value with Top 1, Best Value with EW Top 3, and Weighted with EW Top 3. Performance was assessed using return correlations, average returns, standard deviations, Sharpe ratios, CAGR, maximum drawdown and calendar year returns, with annual Sharpe ratios using average 3-month T-bill yield as the risk-free rate.
Is combining aggressive value with diversified momentum better than combining aggressive value with aggressive momentum?
In this analysis, aggressive value with diversified momentum (SACEVS Best Value with SACEMS EW Top 3) outperformed aggressive value with aggressive momentum (SACEVS Best Value with SACEMS Top 1) on risk-adjusted measures. The former had a monthly Sharpe ratio of 0.35, CAGR of 11.9% and annual Sharpe ratio of 1.04, versus 0.26, 10.9% and 0.87 for the latter. The aggressive-aggressive pairing did have the lowest return correlation (0.10) and a smaller maximum drawdown (-19%) than the other pairing (-20%) was close, but the article judged aggressive value with cautious momentum preferable.
What are the limitations of combining value and momentum mutual fund strategies with monthly rebalancing?
The analysis ignores costs and constraints such as mutual fund loads and penalties for early withdrawals, both for the base strategies and for monthly rebalancing of the 50-50 combination. These constraints may be stronger for the diversified versions of the SACEVS and SACEMS pair than for the aggressive versions. The sample period (September 1997 through July 2019) is also modest for analyzing annual returns, and cautions from the underlying SACEVS and SACEMS mutual fund studies also apply.