
Does strong (weak) past growth in a company’s total assets predict high (low) future stock returns? Or, does investor overreaction to past data predict the opposite? In the July 2007 update of their paper entitled “Asset Growth and the Cross-Section of Stock Returns”, flagged by a reader, Michael Cooper, Huseyin Gulen and Michael Schill examine the relationship between firm asset growth (year-on-year percentage change in total assets) and subsequent stock returns. Using firm fundamentals and stock return data for all non-financial U.S. public companies over the period 1968-2003, they conclude that:
- There is a strong negative correlation between past asset growth and subsequent abnormal stock returns. Raw value-weighted returns for the 10% of firms with the lowest (highest) past asset growth rates average 18% (5%) annually. (See the chart below.)
- With standard risk adjustments, equal-weighted portfolios of firms with low (high) past asset growth rates earn future average returns of 9.1% (-10.4%), a highly significant spread of 19.5%. Capitalization weighting reduces the average spread to 8.4% per year.
- This asset growth effect persists well beyond the next year, offering abnormal returns
up to five years after the sorting year. - The effect is consistent, with low asset growth stocks beating high asset growth stocks in 91% (71%) of sample years on an equal-weighted (value-weighted) basis.
- Although the effect is particularly strong for small companies, it is also significant among large-capitalization firms.
- The asset growth effect is generally stronger than book-to-market, firm capitalization, momentum and other growth measure effects (especially for large-capitalization firms). The Sharpe ratio of annual returns for a value-weighted hedge portfolio is 1.07 for asset growth, 0.37 for book-to-market, 0.13 for firm size and 0.73 for momentum.
- The components of total assets that drive the effect most strongly are changes in operating assets and changes in debt and stock financing. Growth in debt (stock) financing has the strongest effect form small and medium-size (large) firms. The asset growth effect partially explains the secondary issuance/repurchase anomaly.
- Investors appear to overreact to past firm growth rates.
The following chart, taken from the paper, shows 12-month returns for equal-weighted and value-weighted portfolios constructed annually based on past asset growth rates for 1968-2002. Decile 1 (10) consists of firms among the 10% lowest (highest) asset growth rates. The spread is the return for low-growth stocks minus the return for high-growth stocks. It shows that low-growth beats high-growth in all but three (1984: -1%; 1985: -5%; 1996: -2%) of 35 years for equal-weighted portfolios.
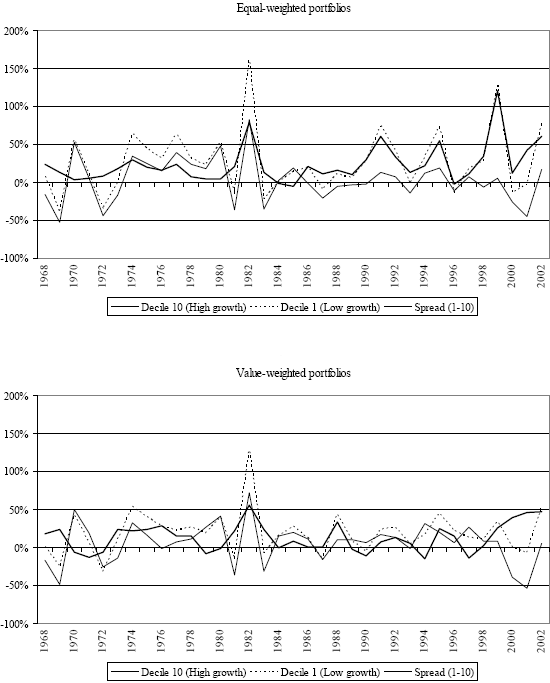
In summary, consistent with the interpretation that investors over-extrapolate past trends, last-year change in firm assets is among the most economically and statistically significant predictors of next-year returns for individual U.S. stocks. On average, stocks of companies with low growth last year consistently outperform stocks of companies with high growth last year.
Frequently Asked Questions
What is the asset growth effect in stock returns?
The asset growth effect is the tendency of stocks with low year-over-year growth in total assets to outperform stocks with high asset growth. Asset growth is measured as the year-on-year percentage change in a firm's total assets. In a study of U.S. non-financial firms from 1968 to 2003, past asset growth was strongly negatively correlated with subsequent abnormal stock returns.
Does past asset growth predict future stock returns?
Past asset growth predicts future stock returns negatively: low asset growth stocks outperform high asset growth stocks. For U.S. non-financial firms in 1968-2003, equal-weighted risk-adjusted returns averaged 9.1% for low growth versus -10.4% for high growth, a 19.5% spread. The effect persists up to five years after the sorting year and was consistent, with low growth beating high growth in 91% of sample years on an equal-weighted basis.
How is the asset growth anomaly tested using portfolio sorts?
The asset growth anomaly is tested by sorting U.S. non-financial public companies annually into deciles based on year-over-year percentage change in total assets, then measuring subsequent 12-month returns. Decile 1 holds the 10% of firms with the lowest asset growth and decile 10 the 10% with the highest, and the spread is low-growth minus high-growth returns. Portfolios are formed on both equal-weighted and value-weighted bases, with standard risk adjustments applied, over 1968-2003.
How does the asset growth effect compare to book-to-market, size and momentum?
The asset growth effect is generally stronger than the book-to-market, firm size, momentum and other growth measure effects, especially among large-capitalization firms. The Sharpe ratio of annual returns for a value-weighted hedge portfolio is 1.07 for asset growth, versus 0.73 for momentum, 0.37 for book-to-market and 0.13 for firm size. The effect also partially explains the secondary issuance/repurchase anomaly.
What are the limitations of the asset growth effect as a stock return predictor?
The asset growth effect is weaker under capitalization weighting, where the average spread falls from 19.5% to 8.4% per year, and it is particularly strong among small companies. It does not work every year: low growth lagged high growth in three of 35 years for equal-weighted portfolios (1984, 1985 and 1996), and in about 71% of years low growth won on a value-weighted basis. The findings cover only U.S. non-financial firms from 1968 to 2003, and the investor-overreaction explanation is an interpretation rather than a proven cause.