
Given the conflicting evidence about the import of the size effect, is there a way investors can extract a reliable premium from small stocks? In their January 2015 draft paper entitled “Size Matters, If You Control Your Junk”, Clifford Asness, Andrea Frazzini, Ronen Israel, Tobas Moskowitz and Lasse Pedersen examine whether controlling for firm quality mitigates the following seven unfavorable empirical findings that the size effect:
- Is weak overall in the U.S.
- Has not worked out-of-sample and varies significantly over time.
- Only works for extremely small stocks.
- Only works in January.
- Only works for market capitalization-based measures of size.
- Is subsumed by illiquidity.
- Is weak internationally.
They control for quality using a Quality-Minus-Junk (QMJ) factor based on profitability, profit growth, safety and payout. They use a portfolio test approach, ranking stocks into value-weighted tenths (deciles) each month to examine differences among stocks sorted by factor. Focusing on returns and factor metrics for a broad sample of U.S. common stocks during July 1957 (when quality metrics become available) through December 2012 and for 23 other developed country stock markets during January 1983 through December 2012, they find that:
- Over an extended sample period from July 1926 through December 2012, the size effect is moderately significant (the average month gross return spread between extreme small-big deciles is 0.55%) but derives entirely from returns in January and varies substantially over time.
- During July 1957 through December 2012:
- Stocks with very low quality are typically very small, have low average returns and are distressed and illiquid. This negative size-quality relationship largely explains unfavorable findings for the size effect.
- Controlling for quality via the QMJ factor, the gross size effect is:
- Economically large and statistically significant (about double the uncontrolled size effect).
- Stable over time and across different measures of size, calendar seasons, U.S. industries and international markets.
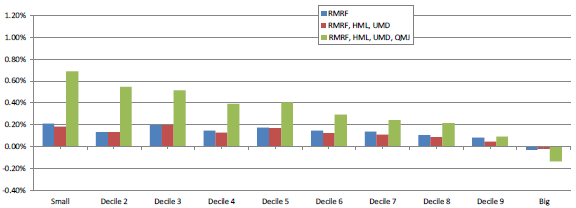
- Systematic across size deciles rather than concentrated among tiny firms (see the chart below).
- Less exposed to liquidity measures, implying practical exploitability.
- Controlling for quality also explains interactions between size and other factors such as value and momentum. Specifically, controlling for quality explains why conventional factor models overstate (understate) expected returns for small growth (value) stocks.
The following chart, taken from the paper, summarizes gross alphas of stock size deciles with respect to three factor models of U.S. stock returns during July 1957 through December 2012:
- Adjusted for broad stock market return minus the risk-free interest rate (RMRF)
- Adjusted also for short-term reversion, value and momentum factors (RMRF, HML, UMD).
- Even further adjusted for the quality factor (RMRF, HML, UMD, QMJ).
Results indicate that adjustment for the quality factor gives a large boost to the size effect and makes it much more systematic across size deciles.
In summary, evidence indicates that controlling for quality produces a robust size effect that is on roughly equal footing with value and momentum, and potentially exploitable.
Investors may want to consider screening for small, high-quality stocks.
Cautions regarding findings include:
- As noted, portfolio/factor returns are gross, not net. Accounting for the costs of monthly portfolio reformation and shorting costs for long-short portfolios would reduce returns. Shorting of some stocks in long-short portfolios may not be feasible.
- Snooping many factors and factor combinations introduces snooping bias, such that the best models likely overstate predictive power.
- The study does not demonstrate that the quality-controlled size effect is exploitable, but the strong performance of the first decile in the chart above is promising for a long-only approach.
Frequently Asked Questions
What is the size effect in investing and what is the Quality-Minus-Junk (QMJ) factor?
The size effect is the tendency for small-capitalization stocks to earn higher average returns than large-capitalization stocks. The Quality-Minus-Junk (QMJ) factor measures the return spread between high-quality and low-quality (junk) stocks, with quality based on profitability, profit growth, safety and payout. Researchers use QMJ to control for firm quality when testing whether small stocks earn a reliable premium.
Does controlling for quality make the small-stock size effect work?
Controlling for quality makes the size effect much stronger and more reliable. During July 1957 through December 2012, the quality-controlled gross size effect was about double the uncontrolled effect (uncontrolled gross spread between extreme small and big deciles: 0.55% per month over July 1926 to December 2012). It was also stable over time, across size measures, calendar seasons, U.S. industries and international markets.
How do researchers test the size effect while controlling for quality?
Researchers rank stocks each month into value-weighted deciles by size and compare returns across the deciles. They then adjust the returns with factor models: market (RMRF); market plus value, momentum and short-term reversion (HML, UMD); and those plus the Quality-Minus-Junk (QMJ) factor. The tests used a broad U.S. stock sample from July 1957 through December 2012 and 23 other developed markets from January 1983 through December 2012.
Why do very small stocks look weak in size studies, and how does the quality-controlled size effect compare to value and momentum?
Very small stocks often look weak because stocks with very low quality tend to be extremely small, distressed and illiquid, with low average returns. This negative size-quality relationship largely explains the unfavorable findings about the size effect. After controlling for quality, the size effect appears roughly on equal footing with value and momentum and is systematic across size deciles rather than concentrated in tiny firms.
What are the limitations of the quality-controlled size effect for investors?
The reported quality-controlled size effect is based on gross returns, so monthly portfolio reformation costs and shorting costs would reduce returns. Shorting some stocks in long-short portfolios may not be feasible. Testing many factors and combinations introduces snooping bias that likely overstates predictive power, so the study does not demonstrate that the effect is exploitable, though the strong first-decile performance is promising for a long-only approach.