
How well do commonly used valuation multiples align with actual stock prices? In their January 2007 paper entitled “Multiples and Their Valuation Accuracy in European Equity Markets”, Andreas Schreiner and Klaus Spremann investigate the accuracy of the valuation multiple method in general and the properties of 50 different multiples (see the figure below). They define a valuation multiple as a market price variable (e.g., stock price) divided by a particular value driver (e.g., earnings). Using stock price and firm financial data over the period 1996-2005 primarily for the Dow Jones STOXX 600 (ten industries, 18 supersectors, 39 sectors, and 104 subsectors) and secondarily for the S&P 500 index, they find that:
- Valuation multiples align with market value fairly well, with median absolute valuation errors less than 30%.
- Equity value (market capitalization) multiples outperform enterprise value multiples due to noise in the enterprise value data.
- In science/technology-based industries, knowledge-related multiples (which augment earnings by adding research and development costs and intangible asset amortization) outperform multiples using unadjusted earnings.
- Forward-looking multiples (using projections of a driver variable, such as earnings), in particular the two-year forward-looking price-earnings ratio (P/E), outperform multiples using trailing data.
- Multiples based on value drivers closer to bottom line income outperform multiples based on value drivers further up in the income statement.
- Multiples based on earnings clearly outperform those based on book value and cash flow.
- U.S. results are similar, with valuation multiples even more accurate than elsewhere, indicating that: (1) the widespread use of P/E and the price-book value ratio (P/B) influences U.S. stock prices; and, (2) analyst earnings forecasts better reflect firm value for U.S. stocks than for European stocks.
The following table, taken from the paper, summarizes the valuation multiples that the authors investigate, with definitions as follows: P = stock price; EV = enterprise value; SA = sales or revenues; GI = gross income; EBITDA = earnings before interest, taxes, depreciation and amortization; EBIT = earnings before interest and taxes; EBT = earnings before taxes; E = earnings available to common shareholders; TA = total assets; IC = invested capital; B = book value of common equity; OCF = operating cash flow; D = ordinary cash dividend; R&D = research & development expenditures; AIA = amortization of intangible assets; and, KC = knowledge costs (R&D + AIA). Forward-looking multiples use mean analyst forecasts for the next one (1) or two (2) years.
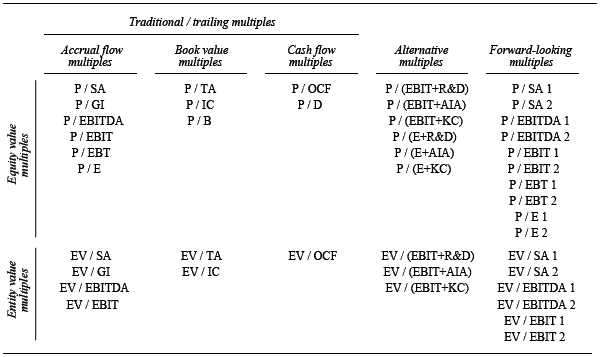
In summary, P/E using two-year forward earnings estimates is among the best indicators of firm market value. For technology firms, adjusting earnings to include investments in intellectual property enhances valuation accuracy.
Frequently Asked Questions
What is a valuation multiple in investing?
A valuation multiple is a market price variable, such as stock price or enterprise value, divided by a particular value driver, such as earnings, sales, book value, or cash flow. The valuation multiple method uses these ratios to estimate a firm's value relative to its fundamentals. Examples include the price-earnings ratio (P/E) and the price-book value ratio (P/B).
How accurate are valuation multiples at estimating stock values?
Valuation multiples align with market value fairly well, with median absolute valuation errors below 30% in a 1996-2005 study of 50 multiples, primarily on the Dow Jones STOXX 600 and secondarily on the S&P 500. The two-year forward-looking P/E, based on mean analyst earnings forecasts, was among the best indicators of firm market value. Accuracy varies by multiple type.
How is the accuracy of a valuation multiple tested?
Valuation multiple accuracy was tested by comparing multiple-based valuations with actual market values, using stock price and firm financial data for 1996-2005. The study covered 50 multiples across the Dow Jones STOXX 600 (ten industries, 18 supersectors, 39 sectors, and 104 subsectors) and the S&P 500. Forward-looking multiples used mean analyst forecasts for the next one or two years, and accuracy was summarized by median absolute valuation error.
Are forward P/E ratios better than trailing P/E ratios for valuing stocks?
Forward-looking multiples, particularly the two-year forward P/E, outperformed multiples based on trailing data in the 1996-2005 study. Earnings-based multiples also clearly outperformed those based on book value and cash flow, and equity value multiples outperformed enterprise value multiples. Multiples built on value drivers closer to bottom-line income did better than those using drivers higher up the income statement.
What are the limitations of using valuation multiples to value stocks?
Valuation multiples still carry errors, with median absolute valuation errors approaching 30% in the study of 1996-2005 data. Enterprise value multiples underperformed because of noise in enterprise value data, and forward multiples depend on analyst forecasts, which reflected firm value better for U.S. stocks than for European stocks. For science and technology firms, unadjusted earnings were less accurate than knowledge-adjusted earnings that add back R&D and intangible amortization.