
How are the asset allocations of the largest university endowments, conventionally accepted as among the best investors, evolving? In their December 2016 paper entitled “The Evolution of Asset Classes: Lessons from University Endowments”, John Mulvey and Margaret Holen summarize recent public reports from large U.S. university endowments, focusing on asset category definitions and allocations. Using public disclosures of 50 large university endowments for 2015, they find that:
- Approaches to categorization of asset classes are diverse. The typical breakdown is: public equity (with geographic subcategories), private equity, real assets (real estate and natural resources), absolute return (hedge funds) and fixed income.
- There is a broad shift to alternative investments, from 23% in 2000 to 51% in 2014, and 57% for endowments over $1 billion (see the table below for a 2016 update).
- Common top-down requirements are growth, inflation protection, manager quality, exploitation of less efficient markets and balance between liquid and illiquid investments.
- There is some movement toward defining asset categories by target performance or underlying return drivers rather than traditional classes.
The following chart, taken from the 2016 Study of Endowment Reports, summarizes university endowment asset allocations as of June 30 2016. Alternative strategies include: private equity; hedge funds of various types; venture capital; non-campus real estate; natural resources (oil, gas, timber, commodities and managed futures); and, distressed debt. Results show that allocations to traditional asset classes (alternative strategies) tend to decrease (increase) with fund size.
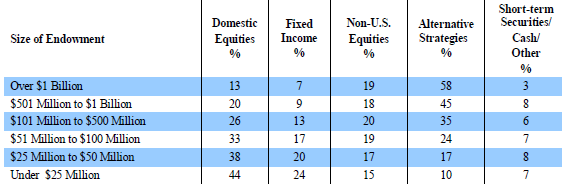
In summary, recent reports of university endowments indicate continuation of a shift away from traditional asset classes and toward alternative strategies.
Cautions regarding findings include
- The paper does not address endowment/asset class performance.
- As noted in the paper, source material is self-reported and therefore varying in conventions and depth.
- Many of the alternative strategies employed by university endowments are impractical for most investors.
See also:
- “Mimicking University Endowment Asset Allocations”
- “University Endowment Research Summary”
- “University Endowment Performance: Strategic versus Tactical Allocation”
- “A Few Notes on The Ivy Portfolio: How to Invest Like the Top Endowments and Avoid Bear Markets”
Frequently Asked Questions
What are alternative investments in a university endowment portfolio?
Alternative investments in a university endowment portfolio are strategies outside traditional stocks and bonds. They include private equity, various hedge funds, venture capital, non-campus real estate, natural resources (oil, gas, timber, commodities and managed futures) and distressed debt. A study of 50 large U.S. university endowments using 2015 disclosures found these strategies now make up a large share of endowment assets.
Have large university endowments shifted toward alternative investments over time?
Large university endowments have shifted broadly toward alternative investments, from 23% of assets in 2000 to 51% in 2014, and 57% for endowments over $1 billion. A review of 50 large endowments' 2015 public disclosures found this shift continuing away from traditional asset classes. Allocations to alternatives tend to increase with fund size, while allocations to traditional asset classes tend to decrease.
How are university endowment asset allocations categorized and compared?
University endowment asset allocations are typically categorized from public reports into public equity (with geographic subcategories), private equity, real assets (real estate and natural resources), absolute return (hedge funds) and fixed income. The study summarized public disclosures of 50 large U.S. endowments for 2015, though categorization approaches vary across endowments. Some endowments are moving toward defining categories by target performance or underlying return drivers rather than traditional asset classes.
How do the asset allocations of larger university endowments differ from smaller ones?
Larger university endowments hold more alternative investments and fewer traditional assets than smaller ones. Endowments over $1 billion had 57% in alternatives, compared with an average of 51% for large endowments in 2014. Across the study, allocations to traditional asset classes tend to decrease and allocations to alternatives tend to increase with fund size.
What are the limitations of copying university endowment investment strategies?
Copying university endowment strategies has limits: the study does not address endowment or asset class performance, so it does not show that the allocations pay off. The source material is self-reported, so conventions and depth of disclosure vary across endowments. Many of the alternative strategies endowments use are also impractical for most investors.