
We occasionally select for retrospective review an all-time “best selling” research paper from the past few years from the General Financial Markets category of the Social Science Research Network (SSRN). Here we summarize the June 2007 paper entitled “The Fundamentals of Commodity Futures Returns” (download count over 2,500) by Gary Gorton, Fumio Hayashi and Geert Rouwenhorst. Commodity futures are derivative, short-maturity claims on real assets. In this paper, the authors apply the theory of storage to investigate relationships between the physical inventories of these assets and the returns to traders in the associated commodity futures. Using monthly data for over 30 commodity futures and associated physical inventories as available between 1969 and 2006 and data from the weekly Commodity Futures Trading Commission Commitments of Traders (COT) reports, they conclude that:
- Of the 33 commodity futures examined, 26 (21) earn positive arithmetic (geometric) average excess returns. An equally weighted index of these futures earns an average annual excess return of 5.48%.
- The correlations among returns for commodity futures are positive but generally small.
- Commodity futures prices mostly exceed contemporaneous spot prices (are in contango).
- Spot returns, futures basis (percentage difference between the current spot price and current nearest-to-maturity futures price, also called “roll yield” or “roll return”) and past futures returns reflect inventory levels and are informative about commodity futures risk premiums. Specifically, low inventories indicate high commodity futures risk premiums.
- Low commodity inventory levels are associated with futures prices in backwardation (positive roll return), while high inventories are associated with futures prices in contango (negative roll return).
- Over the entire sample period, a portfolio of commodities in backwardation (contango) outperforms (underperforms) an equally weighted index by an average 5.4% (4.8%) per year. A hedge portfolio that is long (short) commodity futures with high (low) basis generates positive returns in 58% of sample months with an average annual return of 10.2%. (See the chart below.)
- A hedge portfolio that is long (short) commodity futures with high (low) momentum also generates positive returns in 58% of sample months with an average annual return of 13.4%. Momentum returns may derive from the slow recovery of commodity inventories from shocks.
- Backwardation and momentum strategy returns stem from selecting commodities subject to high price volatility due to low inventories and thereby earning a premium for bearing volatility risk.
- Aggregate positions of commodity futures traders correlate with both contemporaneous inventories and contemporaneous futures prices. Commercial traders increase short positions after prices spike and when inventories are high. Non-commercial traders increase long positions in commodities with high momentum and, to a lesser extent, positive roll return. However, there is no evidence that net positions (hedging pressure) independently correlate with futures risk premiums.
The following chart, taken from the paper, plots average annualized futures risk premium versus average annualized futures basis (roll return) for individual commodity futures from December 1990 through December 2006. The basis compares futures prices to contemporaneous spot prices, while the risk premium is the difference between futures prices and expected future spot prices. A positive (negative) basis indicates commodity futures in backwardation (contango). A simple linear regression has an R-squared statistic of 0.52, indicating that variation in basis explains 52% of the risk premium. In general, futures prices must exceed contemporaneous spot prices to compensate inventory holders for the cost of storage. Only when inventories are unusually low can the spot price exceed the futures price corrected for storage cost.
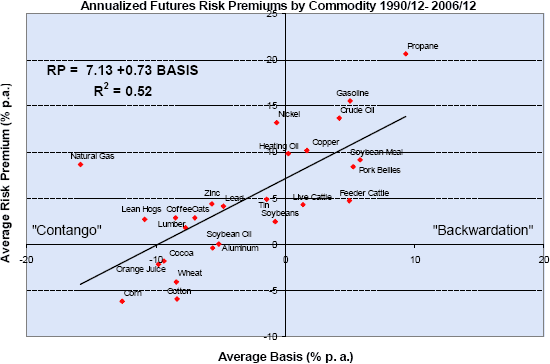
In summary, physical inventory levels are the critical determinants of commodity future price variations and returns, intermediating both backwardation (positive roll) returns and momentum returns. After accounting for inventory effects, there is no evidence that the aggregate position of traders (hedging pressure) predicts commodity futures risk premiums.
Frequently Asked Questions
What is the theory of storage in commodity futures markets?
The theory of storage links the physical inventories of real assets to the pricing and returns of the associated commodity futures. Futures prices must generally exceed contemporaneous spot prices (contango) to compensate inventory holders for storage costs. Only when inventories are unusually low can the spot price exceed the futures price corrected for storage cost (backwardation).
Do low commodity inventories predict higher commodity futures returns?
Low commodity inventories do indicate high commodity futures risk premiums, based on 33 commodity futures studied from 1969 to 2006. Over that period, a portfolio of commodities in backwardation outperformed an equally weighted index by an average 5.4% per year, while a contango portfolio underperformed by 4.8% per year. The equally weighted index itself earned an average annual excess return of 5.48%.
How is the futures basis or roll return measured and used to build commodity trading strategies?
The futures basis (roll return) is the percentage difference between the current spot price and the current nearest-to-maturity futures price, with a positive basis indicating backwardation and a negative basis indicating contango. A hedge portfolio long high-basis and short low-basis commodity futures generated positive returns in 58% of sample months, averaging 10.2% per year. The study used monthly data on over 30 futures and their physical inventories from 1969 to 2006, plus weekly Commitments of Traders reports.
Is hedging pressure a better predictor of commodity futures risk premiums than inventory levels or momentum?
No, hedging pressure (aggregate net trader positions) is not a better predictor; after accounting for inventory effects, the study found no evidence that it independently predicts commodity futures risk premiums. Inventory-linked signals performed better: a long-high/short-low momentum hedge portfolio averaged 13.4% per year and a basis hedge portfolio averaged 10.2% per year, each positive in 58% of months. Momentum returns may derive from the slow recovery of inventories from shocks.
What are the limitations of using futures basis to explain commodity risk premiums?
The futures basis does not explain all variation in commodity futures risk premiums. In a regression of average annualized risk premium on average annualized basis for individual commodities from December 1990 to December 2006, the R-squared was 0.52, so basis explained 52% of the variation. Results also rest on a 1969–2006 sample, and inventory data were available only as available for each commodity.